3 min read
The Chicago multifamily market has been resilient in 2026, outperforming national trends. The average vacancy rate at Class B and C properties was 4.1% in the second quarter, compared with 5.4% nationwide, according to Moody’s. As of June, Chicago recorded seven consecutive months of asking rent gains.
Chicago’s measured approach to construction, consistent renter demand and challenging homebuying market have supported solid performance despite elevated interest rates and potential regulatory headwinds.
“Limited new supply continues to support rent growth, setting the market apart from many others facing greater supply pressures,” said Alicia Pickens, Regional Sales Manager at Chase.
Asking rents increased in 23 of Chicago’s 25 submarkets during the second quarter, according to Moody’s.
Supply growth ahead, but workforce housing is insulated
Chicago gained about 3,200 new units in 2025, the fewest since 2012. Supply is expected to return to more typical levels in 2026, with roughly 7,000 units completed—slightly above the 6,800 units delivered on average over the past decade, according to Moody’s. The stronger construction pipeline is expected to lift Chicago’s vacancy rate across all units to 5.6% by the end of the year, up 30 basis points from the end of 2025. Even with the increased construction, Moody’s projects effective rent growth of 3.7% in 2026.
Historically, Class B and C properties, often workforce and affordable housing, have been a source of consistent demand from renters—and durable cash flow for Chicago multifamily investors.
“It’s still too expensive to build housing that competes with these more affordable properties,” Pickens said.
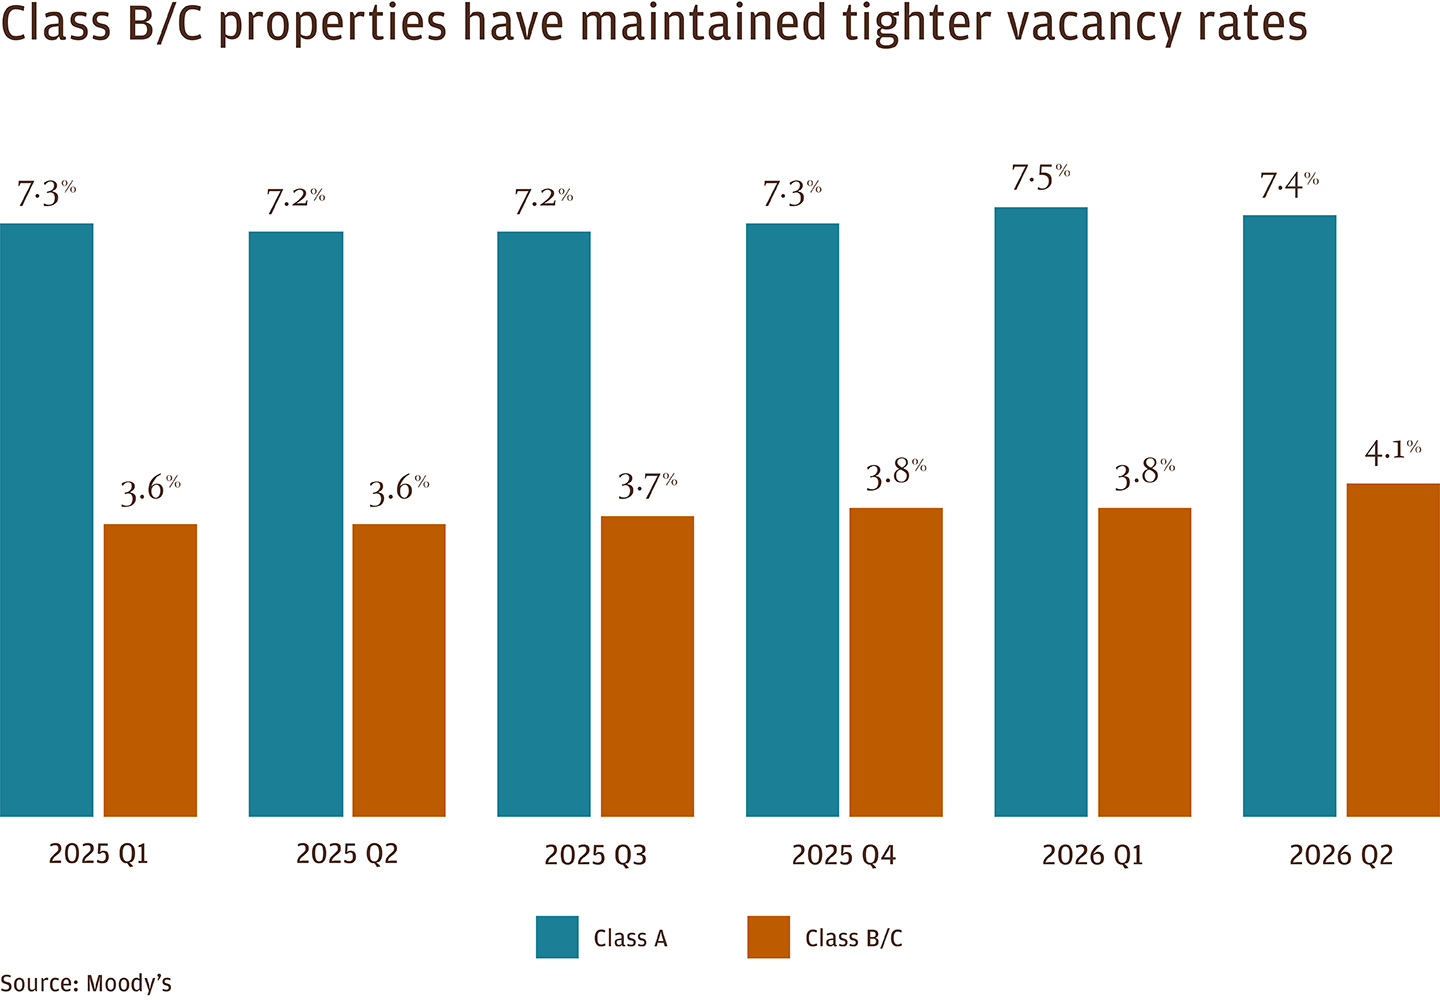
A grouped bar chart shows quarterly multifamily vacancy rates for Class A versus Class B/C properties in Chicago from Q1 2025 through Q2 2026. Class A vacancy holds relatively flat in the low-7% range across the period, with a slight uptick to 7.5% in Q1 2026 before easing slightly to 7.4% in Q2 2026. Class B/C vacancy stays consistently lower, starting in the mid-3% range and trending gradually upward to 4.1% in Q2 2026.
Source: Moody's.
At Class B and C properties, opportunistic renovations can help increase renter demand and cash flow. For some, that may mean updating finishes, such as replacing carpet with laminate flooring that mimics wood. Others may adjust floor plans that have fallen out of step with renter preferences. Formal dining rooms, for instance, may have more value if converted into an additional bedroom, home office or larger kitchen with a breakfast nook.
“As units turn, we’re seeing clients take advantage of the chance to make updates and bring rents in line with the market,” Pickens said.
Managing rising property costs
Inflation hasn’t spared property management costs. Rising insurance and repairs and maintenance expenses continue to pressure margins.
Deferring repairs can lead to more expensive problems down the road, so maintaining consistent property upkeep—despite cost pressures—remains critical.
Creating or reviewing a liquidity management plan with your banking team can help you make the most of your cash and potentially help offset rising costs. Choosing fast, frictionless payment systems can aid cash positioning, and even short-term cash reserves can earn interest.
Uncertainty for interest rates
As the Federal Reserve balances efforts to stabilize prices and maximize employment, the timeline for any interest rate cuts remains unclear. While higher rates present challenges for multifamily investors, opportunities exist throughout the market cycle, Pickens said.
“With each investor, we focus on understanding what they need and finding the structure that works best for them,” she said.
Many multifamily owners seeking or refinancing apartment loans are exploring loan structures that provide flexibility as rates shift. Options for tailoring structures to an owner’s strategy can include:
- ARM loans up to a 15-year term, with rate and payment adjustments every six months
- A flexible stepdown prepayment premium
- Shorter hybrid- or fixed-rate terms
- Interest-only periods
Whether you’re ready for financing or looking to streamline your operations, reach out to our Chicago lending, payments and liquidity team.
JPMorgan Chase Bank, N.A. Member FDIC. Visit jpmorgan.com/commercial-banking/legal-disclaimer for disclosures and disclaimers related to this content.