Version 1 - Primary Nav Search

Investing in
reindustrialization
and economic
security 

From energy and critical minerals to advanced manufacturing
and defense, the first year of the Security and Resiliency
Initiative has underscored what it takes to turn investment into
long-term capacity and resilience.

October 20, 2026

Executive summary

The first year of the Security and Resiliency Initiative underscored four clear lessons:

  • Capital is essential — but impact also stems from execution. Success requires transforming capital into capacity by moving projects from financing to buildout, scale and sustained operations.
  • Public-private partnerships can accelerate strategically critical outcomes. When timelines are long, risks are complex or national priorities are involved, shared-risk structures can unlock projects that conventional financing may not support.
  • Resilience is built across end-to-end supply chains, not single assets. Advancing economic security requires investment across multiple stages of production — from inputs and processing to manufacturing and delivery — so bottlenecks do not shift downstream.
  • Workforce and infrastructure are binding constraints on reindustrialization. New facilities and technologies depend on skilled talent, permitting pathways, grid and logistics readiness and community capacity to support long-term growth.
01

Building a new era for economic security 

In its first year, JPMorganChase’s Security and Resiliency Initiative (SRI) facilitated and financed capital to advance U.S. reindustrialization and economic security against a backdrop of heightened geopolitical and macroeconomic uncertainty. International trade tensions and armed conflicts in the Middle East and Ukraine have put pressure on trade and driven increased investment in global defense budgets. Critical resource security and supply have become a primary focus to support continued advancement in energy resiliency, defense manufacturing and technology. Meanwhile, the AI race continues at a rapid pace, with knock-on effects for critical mineral supply chains and energy grids.

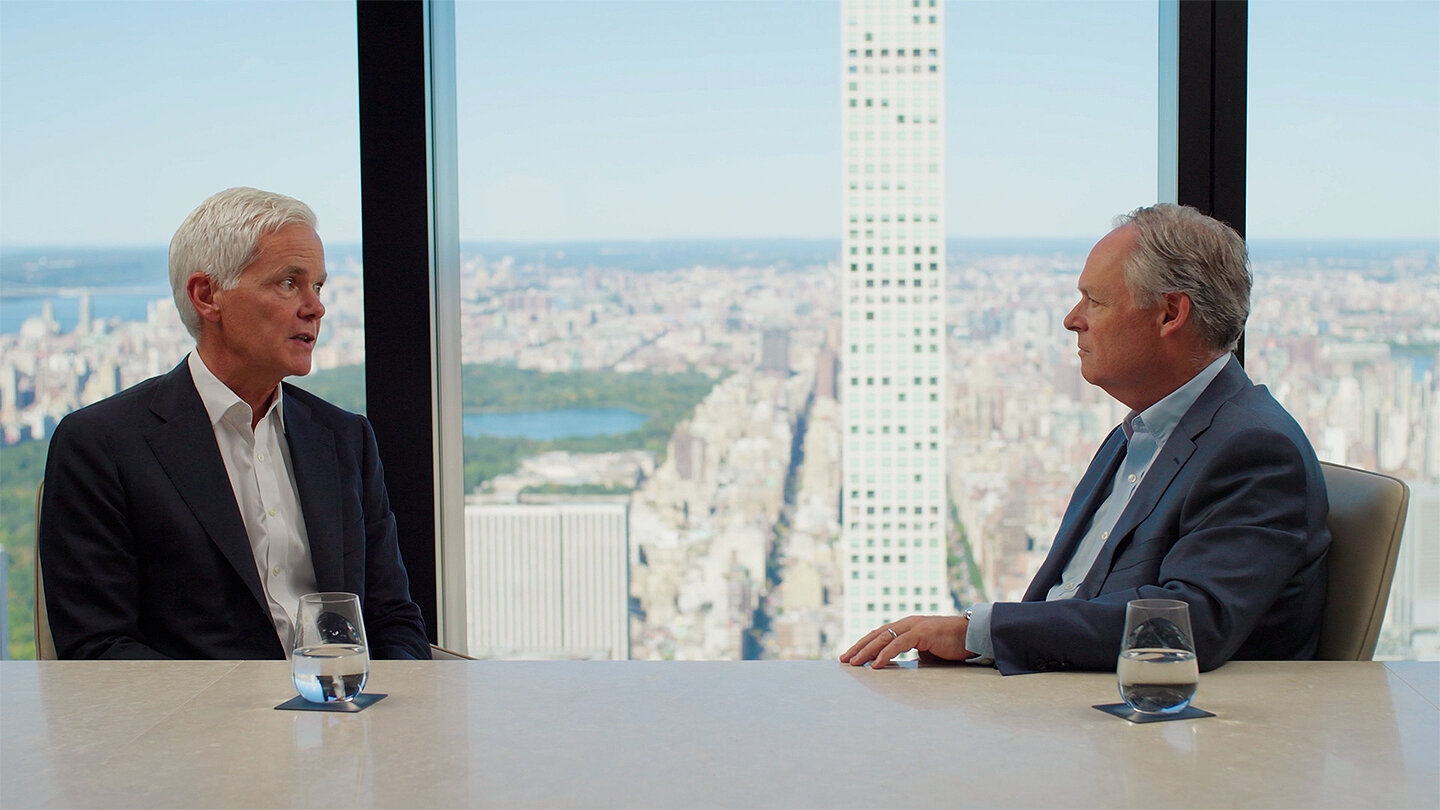
As a result, economic security has become a top priority for governments and businesses around the world. “Issues once viewed primarily through a government or geopolitical lens — energy security, critical minerals, supply chains, technology and manufacturing capacity — are now CEO and board-level business issues,” said Doug Petno, CEO of the Commercial & Investment Bank and co-president of JPMorganChase. “Helping clients navigate these issues is a primary priority.”

The SRI launched in October 2025 to help address these challenges. The $1.5 trillion, 10-year initiative is focused on facilitating, financing and investing in industries critical to economic security and resilience.

In its first year, approximately $230 billion has been facilitated and financed across roughly 380 transactions. That activity spans energy, critical minerals, advanced manufacturing, defense, strategic technologies and healthcare. It has also provided a view into some of the challenges companies face as they invest in new capacity.

One lesson stands out: capital is essential, but capital alone is not enough.
| 11:46

Building an Ecosystem for Economic Security

Doug Petno explains why progress depends on policymakers, industrialists, investors and innovators collaborating, and how JPMorganChase helps bring them together.

| 11:46

Building an Ecosystem for Economic Security

Doug Petno explains why progress depends on policymakers, industrialists, investors and innovators collaborating, and how JPMorganChase helps bring them together.

02

Turning capital to capacity: Building energy independence and grid resilience


Investment needs across critical industries are significant, but it’s not enough to deploy capital indiscriminately. To make a measurable impact, funds must be allocated strategically to projects that can be built quickly, scaled effectively and meet a defined need. 

The energy sector shows clear examples. Global energy markets face a dual challenge: geopolitical volatility and surging electricity demand driven partly by widespread electrification and AI. Energy prices have been unstable in 2026, largely due to the conflict between the U.S. and Iran and fewer oil tankers traveling through the Strait of Hormuz as a result. Simultaneously, demand has skyrocketed. Data centers alone are adding electricity demand at a rate five times faster than a decade ago.1

Consequently, capital is increasingly flowing into renewables and power production to accelerate the deployment of adaptive energy infrastructure and scale energy generation capabilities.

The recent take-private of global power provider AES illustrates the scale of that investment. In the first quarter of 2026, AES executed the largest infrastructure take-private and largest power transaction of all time, valued at $46.1 billion (consolidated). The deal, in which J.P. Morgan served as lead financial advisor, provides access to new capital that AES will use to invest in innovative technologies and expand its development pipeline.

  • $46.1B

    total consolidated value of AES’s landmark take-private transaction 

  • $1.89B

    total raised by Fervo in its U.S. IPO


Beyond infrastructure, industry leaders are pioneering innovative power generation techniques. In geothermal projects, for example, water is pumped into the Earth’s crust, where hot rock transforms it into steam to drive turbines that generate electricity.

Fervo Energy expands the opportunity for geothermal by leveraging existing drilling capabilities to access hot rock significantly farther below the surface. Investor demand has followed. Fervo raised $1.89 billion2 in its initial public offering (IPO) in May 2026, with J.P. Morgan among the joint lead bookrunners. This capital will help fuel the company’s goal to build scalable geothermal technology that is reliable, affordable and sustainable.

Developing new technologies for energy generation is one crucial piece of the larger energy investment cycle. Nuclear, renewables, battery storage, transmission and conventional energy sources all play a role as economies seek to meet growing  demand while strengthening energy security.

With record-breaking transactions in the past year, the challenge for the industry is not simply attracting more capital. Projects need robust infrastructure, permitting, technology and commercial conditions to move from planning through production to make a meaningful impact.  

“This is a profound moment for us to do what we do best as a bank, bring together the broad-based capabilities of JPMorgan Chase, and see if we can really make a difference and do it at scale.”

Doug Pento

CEO of the Commercial & Investment Bank and co-president of JPMorganChase

03

Public-private partnerships rebuild supply chains for US economic security

The private sector is a powerful force for change in these priority areas, but it can’t solve every issue alone. “Addressing these challenges holistically has required new approaches in the first year of the initiative, including public-private partnerships that are setting the precedent for future deals,” Petno said.


Critical minerals are an important test case for this approach. Minerals such as rare earths, copper, lithium and antimony are inputs for numerous industries including defense systems, green energy and technology manufacturing. But supply chains for critical minerals remain highly concentrated, with 91% of refined rare earths and up to 94% of rare earth magnets coming from China.3

This concentration creates downstream vulnerabilities, which have jumpstarted public sector focus on critical minerals. In 2025, the U.S. Defense Logistics Agency announced that it will aim to create a $1 billion stockpile of critical minerals connected to the development of defense systems.4  Then, in February 2026, the Critical Minerals Dominance Act5 was passed in the House of Representatives to streamline permitting for priority mining projects.The effort to rebuild critical mineral supply chains across mining and refinement has led to notable deals. This includes the public-private partnership between the U.S. Department of Defense and MP Materials.

 J.P. Morgan was the sole financial advisor and lead left arranger on $1 billion of committed financing for the deal, which was announced in October 2025. MP Materials is expected to build an additional manufacturing facility in Texas, which will help increase its magnet production to 10,000 metric tons to address the Pentagon’s rare earth magnet requirements.

Additional public-private partnerships soon followed. In December 2025, Korea Zinc announced plans for a large-scale, integrated refinery and smelter project in Tennessee. The project establishes a production hub for Korea Zinc in the U.S., with commercial operations expected to begin in 2029. 

The U.S. Department of Commerce and the Pentagon contributed $2.15 billion in direct equity to the deal, underscoring the federal government’s focus on strengthening production and refinement capabilities. In addition, J.P. Morgan and the Pentagon have provided commitment letters for debt financing of up to $4.7 billion. The firm served as exclusive financial advisor to Korea Zinc as well as placement agent for the equity financing and lead arranger and bookrunner for the debt financing. 

The importance of these structures extends beyond any single transaction. “Government support can provide greater certainty around strategically important projects, while private capital and financial expertise can help companies fund and scale them,” Petno said.

Similar approaches are emerging across energy, advanced manufacturing and defense, where long development timelines, technology risk and the need for significant new infrastructure can make conventional financing more challenging. The result is a broader range of financing structures being used to support strategically important investment.

  • $1B

    of committed financing for MP Materials to increase manufacturing capacity

  • $4.7B

    in commitment letters for debt financing for Korea Zinc 

04

Expediting innovation and industrial readiness 

Ensuring long-term U.S. defense capabilities requires investment in both established defense manufacturers and newly emerged technology companies, domestically and in allied nations. 


The defense industry increasingly intersects with frontier technology firms that may not self-identify as defense companies. As focus on technology increases, investment is flowing toward capabilities that can be fielded and adapted quickly. This includes both improvements in traditional defense capabilities as well as frontier technologies like space-based defense systems. 

To close the gap between legacy production and the speed the current environment demands, established defense manufacturers must be equipped to move faster and more efficiently.

This was the case for L3Harris, a global aerospace and defense technology company. In early January, the Pentagon made a $1 billion convertible preferred equity investment into L3Harris’ Missile Solutions business.6 The deal helps reinforce L3Harris’ role as a key U.S. government partner and aligns with the Pentagon’s new acquisition transformation strategy.

The investment, where J.P. Morgan acted as financial advisor to L3Harris, will be used to expand and modernize facilities, accelerate research and development, increase production capacity and rebuild munitions supplies. 

“Public and private sectors have been somewhat independent, and now we see them starting to work together to tackle things that governments might not be able to do alone.”

Jay Horine

J.P. Morgan, Global Banking and head of SRI 

  • $1B

    convertible preferred security investment by the Pentagon in L3Harris

05

SRI’s expanding global mission

Security and resiliency are not confined by national borders: vulnerabilities exposed across critical minerals, energy, supply chain resiliency and defense are shared challenges. 


This is the case for defense companies in Europe, where rising investment is supporting growth among companies serving both domestic and allied markets. For example, Czechoslovak Group (CSG) completed the largest defense IPO in history in January 2026, with J.P. Morgan serving as joint global coordinator and stabilization manager. The EUR 3.8 billion ($4.4 billion) deal saw books fully covered within four minutes of launch, indicating significant demand and interest in the asset. 

“Success depends on strengthening domestic capacity in strategically important areas, diversifying concentrated supply chains and building reliable relationships with trading partners,” said Jay Horine, head of the Security and Resiliency Initiative. “That’s particularly relevant for global companies deciding where to manufacture, source critical inputs and invest in new capacity.” 

To address the global nature of these challenges, SRI expanded in year one into Europe and Canada, applying the same deployment approach — named capital into critical industries — to economies facing similar structural pressures.

The shift in focus from domestic to international is broadening the definition of economic security — one that encompasses not only traditional defense, but also energy, manufacturing, technology, infrastructure, healthcare and the supply chains connecting them.

  • €3.8B

    CSG’s record-breaking IPO, the largest defense IPO globally (equivalent value $4.4 billion) 

06

Workforce development and building tomorrow’s talent


Securing necessary funds isn’t enough; companies investing in new factories, energy infrastructure and advanced technologies also need workers with the skills to build and operate them. 

Across critical industries, demand is outpacing availability for engineers, technicians, electricians, welders, cybersecurity professionals and other specialized workers. 47% of U.S. manufacturers cited the inability to attract and retain employees as a primary challenge facing their business.7

The existing workforce also skews older, with 50% of U.S. mining workers expected to retire by 2029.8 In aerospace and defense, only 7% of U.S. employees are under 25 years old and 25% are aged 56 or older.9  Within the scope of SRI, workforce availability is an important consideration in decisions about where and how quickly new capacity can be developed.

A case in point is shipbuilding. In July 2026, JPMorganChase announced $24 million in loans, investments and philanthropic funding to support Philadelphia’s shipbuilding and maritime manufacturing industry. The effort includes financing for expanded manufacturing capacity alongside workforce training, apprenticeship opportunities and support for up to 100 maritime small-business suppliers.

  • $24M

    in loans, investments and funding for shipbuilding in Philadelphia

  • 215%

    increase in workforce by 2030 at CesiumAstro’s new Texas headquarters 


While upskilling initiatives like the shipbuilding program are imperative, job opportunity and growth must be prioritized to incentivize workforce development. This means onshoring where possible and expanding existing footprints. 

CesiumAstro Inc is one example. In early 2026, the global leader in space and defense communications systems and satellites announced a $200 million financing package from the Export-Import Bank of the United States. The public-private financing package is intended to accelerate domestic manufacturing in space and defense capabilities, reaffirming the importance of these emerging technologies for the industry.  

CesiumAstro is expected to  establish a new U.S. manufacturing headquarters in Texas in 2027, where its workforce is expected to increase by 215% by 2030, adding more than 500 high-skill jobs .10

Over the 10-year horizon of the SRI, workforce the need for specialized workforces will likely continue to grow. “Investing in industrial capacity means investing in the people and communities that support it,” Horine said. “We’re creating opportunities for our clients to build the talent of the future.” 

07

What comes next 

Over the next decade, the Security and Resiliency Initiative will remain grounded in a core lesson from year one: deploying capital is necessary, but converting investment into durable capacity is the real measure of progress. 


The path forward will require more than incremental financing. Many of the most strategically important buildouts — across critical minerals, power generation and grid resilience, advanced manufacturing and defense readiness — will demand new approaches to risk sharing and public-private partnership structures. Resilience also depends on strength at every stage of the supply chain, from upstream inputs to downstream manufacturing, and on the workforce and community investments that make growth sustainable over time.

These priorities are converging, not operating in isolation. AI-driven demand is accelerating the need for reliable power and modernized infrastructure; energy and advanced manufacturing are constrained by mineral and equipment supply; and defense modernization increasingly blends traditional industrial capacity with emerging technologies — across both the U.S. and in international markets.

The next chapter for SRI is to continue translating complexity into action: turning today’s investment momentum into long-term capability, stronger supply chains and greater economic security and resilience.

This material is for informational purposes only, is not intended as an offer or solicitation for the purchase, sale or tender of any financial instrument and does not constitute a commitment, undertaking, offer or solicitation by any JPMorgan Chase entity to extend or arrange credit or provide any other products or services to any person or entity.  This material is not a product of the Research Department of J.P. Morgan Securities LLC.

Related insights