Key takeaways
- In dealmaking, activism, sponsor dry powder and AI-led transaction flow are driving M&A activity in Asia Pacific.
- In FX and rates, central banks are diverging across Asia Pacific — reshaping how companies borrow, invest and hedge.
- In tech, VC funding is rotating from pure software into "physical AI" such as robotics and automation.
- In energy, the Middle East conflict triggered a record oil supply shock, keeping prices higher for longer.
Dealmaking and the path from startup to multinational
Global M&A volumes grew 45% in the first half of the year, while volumes in Asia Pacific (APAC) fell roughly 10% over the same period — numbers that tell only part of the story.
“That headline figure belies an actual intensity of conversations that we are having with clients on a number of strategic initiatives,” said Rohit Chatterji, Head of M&A, Asia Pacific at J.P. Morgan.
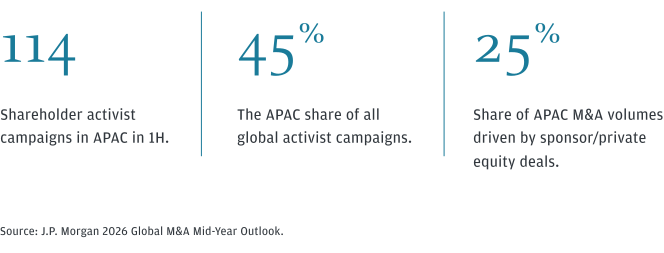
Several themes stand out in what's driving APAC deal activity. Shareholder activism is surging — 114 campaigns in Asia in the first half of the year, representing 45% of all global campaigns, concentrated in Japan but spreading into Korea and Australia.
Sponsor-driven deals are also contributing a meaningful share, accounting for roughly 25% of APAC M&A volumes, as private equity firms that delivered strong exits in recent years return to market with large new funds and capital to deploy.
Dealmaking in APAC by the numbers
114 — Shareholder activist campaigns in APAC in 1H.
45% — The APAC share of all global activist campaigns.
25% — Share of APAC M&A volumes driven by sponsor/private equity deals.
Source :J.P. Morgan 2026 Global M&A Mid-Year Outlook
At the same time, corporates are pursuing strategic moves into adjacent capabilities or new markets closer to customers and demand, while AI-led transactions are gathering pace as hyperscaler capital expenditure (capex) exerts a gravitational pull on deals across networks, components and the broader AI supply chain.
“All four of those themes we are seeing with companies of all sizes,” said Kerwin Clayton, Co-Head, Global Corporate Banking, Asia Pacific at J.P. Morgan.
Growth versus profitability remains a sector-by-sector calculation, with many corporates asking whether a transaction is needed to build scale and profitability, particularly in sectors where consolidation is now the dominant theme.
That calculation often plays out over the long arc of a client relationship. “From the conversations the corporate bank has with clients from the time they were much smaller companies to bigger scale, it's a natural corollary to come in and discuss whether they're ready for a strategic move — raising capital privately, publicly or through an IPO,” Chatterji said.
“Most of the time we're speaking to CEOs or founders, and having that relationship where you can introduce them to someone else from the team for a more pointed strategic discussion is pretty natural,” added Clayton.
How are corporates managing FX and rate risks?
After more than a decade of stable policy rates and abundant liquidity, 2026 brought a decisive shift: central banks across Asia Pacific (APAC) are pulling in different directions, reshaping how companies borrow, refinance, invest and hedge.
Japan, Korea, Indonesia and the Philippines are hiking, while China could be cutting, varying the cost of funding from market by market and company by company across the region.
“After years of a very low rate environment, corporates expected the recent rise to be temporary in nature. Instead, we find ourselves in a higher-for-longer rate environment. Large corporates with sophisticated treasuries can absorb those swings, versus small and medium-sized companies that have less hedging in place and more margin pressure,” said Oliver Brinkmann, Co-Head, Global Corporate Banking, Asia Pacific at J.P. Morgan.
Japan and Korea have intervened directly to steady their currencies this year; Japan spent around $100 billion in coordination with the U.S. to support the yen, materially reshaping how corporate Japan funds and hedges.
“We find ourselves in a higher-for-longer rate environment. Large corporates with sophisticated treasuries can absorb those swings, versus small and medium-sized companies that have less hedging in place and more margin pressure.”

Oliver Brinkmann
Co-Head, Global Corporate Banking, Asia Pacific, J.P. Morgan
“In the case of the yen, hedging costs have fallen materially — to four-year lows — and are likely to go lower still. We're currently around 2.8%, and could head toward 2.5%,” said Rahul Deora, Head of Corporate FX & Rates, Asia Pacific and Head of Local Markets Sales, South Asia, at J.P. Morgan.
Technology and high-growth companies are the most rate-sensitive — higher rates compress forward multiples and lift the cost of capital, reshaping how projects are funded and how founders plan for exits. Nowhere is that clearer than in the hyperscalers and AI infrastructure driving the region's next investment wave.
The new funding landscape for tech and AI
Global AI-related capital expenditure is projected to approach $870 billion by the end of 2026 — a 77% year-over-year climb, on top of around $5.5 trillion in data center spending over the five years to 2030. Asia Pacific's semiconductor makers, cloud infrastructure providers and high growth startups are among the biggest beneficiaries, though the opportunity remains complex for founders navigating it.
“We’re at the precipice of a platform transition that creates an unbridled opportunity in AI. At the same time, there are crosswinds — whether geopolitical, macroeconomic or supply chain-related. Founders need to build for both growth and resilience,” said Mark Fiteny, head of TMT and New Economy Investment Banking, Asia Pacific at J.P. Morgan.
Venture capital is shifting accordingly: while value still accrues at the application layer, funding increasingly flows toward "physical AI" — robotics, automation, edge computing and quantum computing.
“Investors are looking to see how companies are going to use AI to drive innovation — and whether it translates into a scalable, resilient business model.”

Amy Tan
Head of Tech and Innovation, Global Corporate Banking, Asia Pacific, J.P. Morgan
What the oil supply shock means for companies
While tech sector investment is looking ahead, energy markets are grappling with a more immediate challenge. Crude oil markets are facing one of the most severe supply shocks on record, driven by the Middle East conflict and its cascading effects across global trade routes.
“Headline fatigue is setting in. But don’t mistake the price moves for stability. The real impact is being felt on the product side — gasoline, diesel, liquefied petroleum gas (LPG), jet fuel. That’s where the real stress is,” said Raman Walia, head of Commodities Sales for Asia Pacific at J.P. Morgan.
Airlines, refineries and industrials are among the hardest hit, grappling with cash flow disruption, counterparty credit risk and margin compression. For treasurers, the priority is liquidity visibility — knowing what cash is available, where it sits and how fast it can move.
“Crude oil and petrochemicals are inputs for manufacturers across Asia Pacific. Increased costs are cascading across industries — from plastics and polymers to packaging,” said Amalia Lazarus, head of Subsidiary Banking for Asia Pacific at J.P. Morgan.
Contact us
Learn more about J.P. Morgan Global Corporate Banking.
Related insights
Banking
Perspectives from Asia Pacific
Jul 15, 2026
Explore Global Corporate Banking's Asia Pacific market outlook.
Learn more
Banking
The CFO View: Asia Pacific Outlook 2026
Nov 26, 2025
CFOs and treasurers in APAC share their views on the economy and business priorities for 2026 in a new J.P. Morgan survey.
Read more
Banking
Powering for Growth: APAC CFO & Treasurers Forum
The annual forum brings together insightful perspectives and peer-to-peer exchange on the macro forces and trends shaping opportunities ahead.
Read moreDisclaimer
This material (including market commentary, market data, observations or the like) has been prepared by personnel in the Global Corporate Banking Group of JPMorgan Chase & Co. It has not been reviewed, endorsed or otherwise approved by, and is not a work product of, any research department of JPMorgan Chase & Co. and/or its affiliates (“J.P. Morgan”).
Any views or opinions expressed herein are solely those of the individual authors and may differ from the views and opinions expressed by other departments or divisions of J.P. Morgan. This material is for the general information of our clients only.
RESTRICTED DISTRIBUTION: This material is distributed by the relevant J.P. Morgan entities that possess the necessary licenses to distribute the material in the respective countries. This material is proprietary and confidential to J.P. Morgan and is for your personal use only. Any distribution, copy, reprints and/or forward to others is strictly prohibited.
This material is intended merely to highlight market developments and is not intended to be comprehensive and does not constitute investment, legal or tax advice, nor does it constitute an offer or solicitation for the purchase or sale of any financial instrument or a recommendation for any investment product or strategy.
Information contained in this material has been obtained from sources believed to be reliable but no representation or warranty is made by J.P. Morgan as to the quality, completeness, accuracy, fitness for a particular purpose or noninfringement of such information. In no event shall J.P. Morgan be liable (whether in contract, tort, equity or otherwise) for any use by any party of, for any decision made or action taken by any party in reliance upon, or for any inaccuracies or errors in, or omissions from, the information contained herein and such information may not be relied upon by you in evaluating the merits of participating in any transaction. All information contained herein is as of the date referenced and is subject to change without notice. All market statistics are based on announced transactions. Numbers in various tables may not sum due to rounding.
J.P. Morgan may have positions (long or short), effect transactions, or make markets in securities or financial instruments mentioned herein (or options with respect thereto), or provide advice or loans to, or participate in the underwriting or restructuring of the obligations of, issuers mentioned herein. Any examples used are generic, hypothetical and for illustration purposes only. J.P. Morgan does not make representations or warranties as to the legal, tax, credit, or accounting treatment of any such transactions, or any other effects similar transactions may have on you or your affiliates. You should consult with your own advisors as to such matters.
The use of any third-party trademarks or brand names is for informational purposes only and does not imply an endorsement by JPMorgan Chase & Co. or that such trademark owner has authorized JPMorgan Chase & Co. to promote its products or services.
© 2026 JPMorgan Chase & Co. All rights reserved. J.P. Morgan is a marketing name for businesses of JPMorgan Chase & Co. and its subsidiaries and affiliates worldwide. JPMorgan Chase Bank N.A. (member of FDIC), J.P. Morgan Securities LLC (member of FINRA, NYSE and SIPC), J.P. Morgan Securities plc (member of the London Stock Exchange and authorized by the Prudential Regulation Authority (PRA) and regulated by the Financial Conduct Authority and the PRA) and J.P. Morgan SE (authorised by the BaFin and regulated by the BaFin, the German Central Bank and the European Central Bank) are principal subsidiaries of JPMorgan Chase & Co. For legal entity and regulatory disclosures, visit: www.jpmorgan.com/disclosures. For additional regulatory disclosures, please consult: www.jpmorgan.com/disclosures.