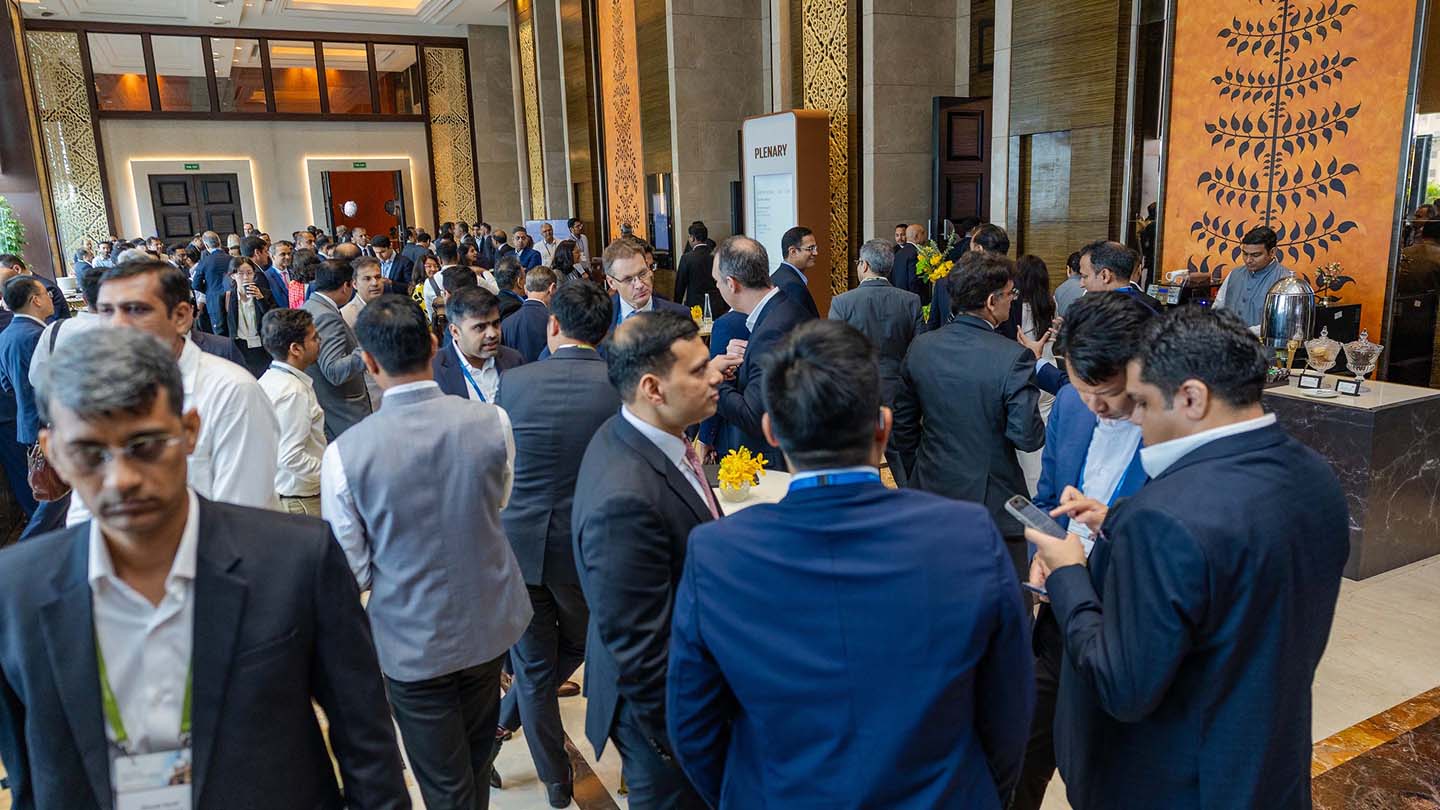
The 11th annual J.P. Morgan India Conference returns to Mumbai on September 21-22, 2026. The event brings together over 1,000 global investors, c-suite executives, policymakers and thought leaders to engage in meaningful dialogue and collaboration. Delegates will explore pivotal themes shaping India and the global economy through CEO tracks, one-on-one meetings and plenary sessions. The conference remains a premier platform for forging connections and uncovering new opportunities as India's role in the global marketplace continues to evolve.
Is India’s equity market the best AI hedge?
As global investors trim or diversify away from crowded AI trades, India’s equity market is emerging as the world's largest, liquid non-AI hedge. What is the outlook for stocks as earnings rebound?
India's growth outlook
A conversation with Sajjid Chinoy, head of Asia Economic Research at J.P. Morgan, on the macro forces shaping the decade ahead.
There’s been a big debate about the recently released GDP print within the country. What are your thoughts?
The recent debate around the GDP print is a storm in a teacup. There should be no doubt about the sanctity of the new GDP print. The methodology has improved significantly. Furthermore, the number itself should not be a surprise. The high-frequency data for the last three months has been very strong: autos, credit, earnings, exports have all been buoyant. We had therefore forecast GDP growth at 8% for the quarter, which was between the gross value added (GVA) print of 8.2% and the GDP print of 7.8%. Therefore, it came as no surprise to us.
Instead of debating the sanctity of the GDP print, the debate needs to be about its sustainability. What we are seeing is a sharp cyclical upswing, underpinned by (i) the fiscal, monetary, regulatory easing in 2025; (ii) the impact of the sharp depreciation of the real exchange rate that can be expected to be expansionary (importantly: net exports was a huge driver of the recent GDP print); and (iii) very adept handling by policymakers during the Middle East crisis wherein energy imports were quickly diversified to prevent widespread shortages.
But for growth to continue at this pace, the cyclical will have to morph into the structural. This will entail crowding in the private capex cycle which, in turn, will require sustained demand visibility. That will require continued focus on job creation to boost consumption and improving export competitiveness.
The Foreign Currency Non-Resident (FCNR) scheme has been a huge success. But, as you have written, it has left a liquidity overhang. What are the RBI’s options?
The deluge of FCNR inflows gives a lot of near-term ammunition to the Reserve Bank of India (RBI), but the collateral impact is a significant easing of monetary conditions that the RBI will need to respond to. At some level, none of this should be a surprise. Back in July we had written a piece “The Good, The Big and the Tricky” anticipating these dynamics. Markets were skeptical of large inflows. But, as we had shown in that note, the dollar return to Non Resident Indians, after the subsidized swap, was in the 13% to 15% range, a substantial pick-up over risk free dollar returns. Therefore we were anticipating large flows, though the eventual number exceeded even our expectations.
This provides important firepower to the central bank, at a time when the global environment is becoming more hostile. Crude prices have flared up and developed market bond yields are on a tear. The collateral benefit has been dollar hedging seems to have moderated.
The tricky element is the liquidity hangover. The deluge of FCNR flows has created an equivalent Rupee quantum in the banking system. At last count, the core liquidity surplus in the banking system was above ₹13 trillion and the headline surplus was ₹10 trillion. Weighted average overnight rates were therefore substantially below the 5.25% policy rate, resulting in a de facto easing of monetary policy.
This is at odds with the signal from the August Monetary Policy Committee (MPC) minutes that the RBI may need to hike rates in the coming months. The central bank will therefore have to aggressively sterilize these inflows.
Of course, these FCNR inflows need to eventually be repaid. So they buy India time. What we do with that time to generate balance of payment surpluses will be crucial.
India's 2047 developed-economy ambition requires sustained high growth over two decades. What are the two or three reforms or investments most critical to staying on that trajectory?
For India’s per-capita income to reach $15,000 by 2047, per-capita dollar growth will have to accelerate from about 6% over the last decade to almost 8% over the next two decades. This will not be easy in a world of increased economic balkanization, rampant Chinese capacity and AI that could be as labor-displacing as labor-augmenting. To grow at higher rates against this global backdrop, India needs to become structurally more competitive and use its greatest assets – its people – more effectively. This will involve sustained factor market reform (land, labor, power), deregulation, more trade liberalization and, most of all, deep investments in human capital (education, health, skilling) so that labor can compete more effectively with capital.
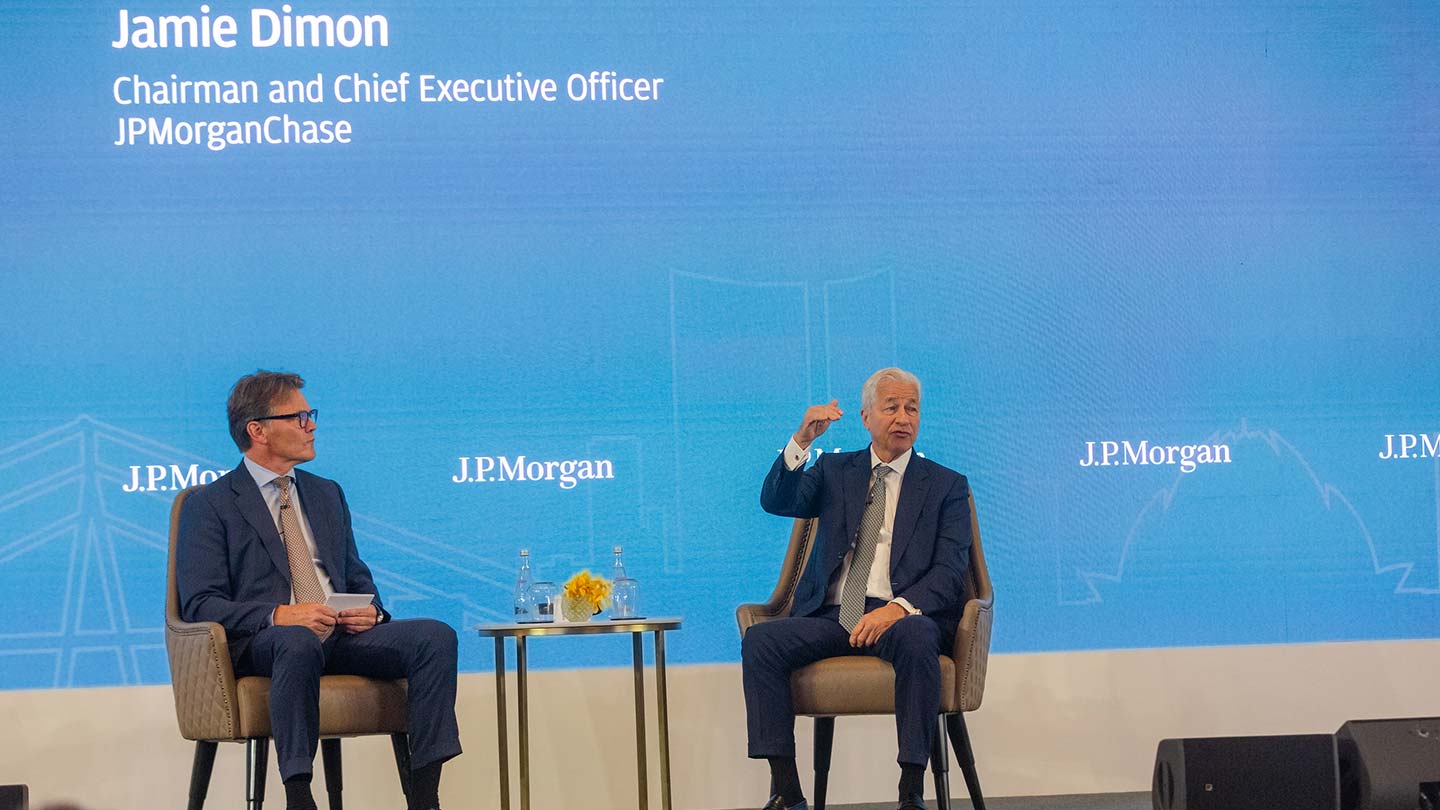
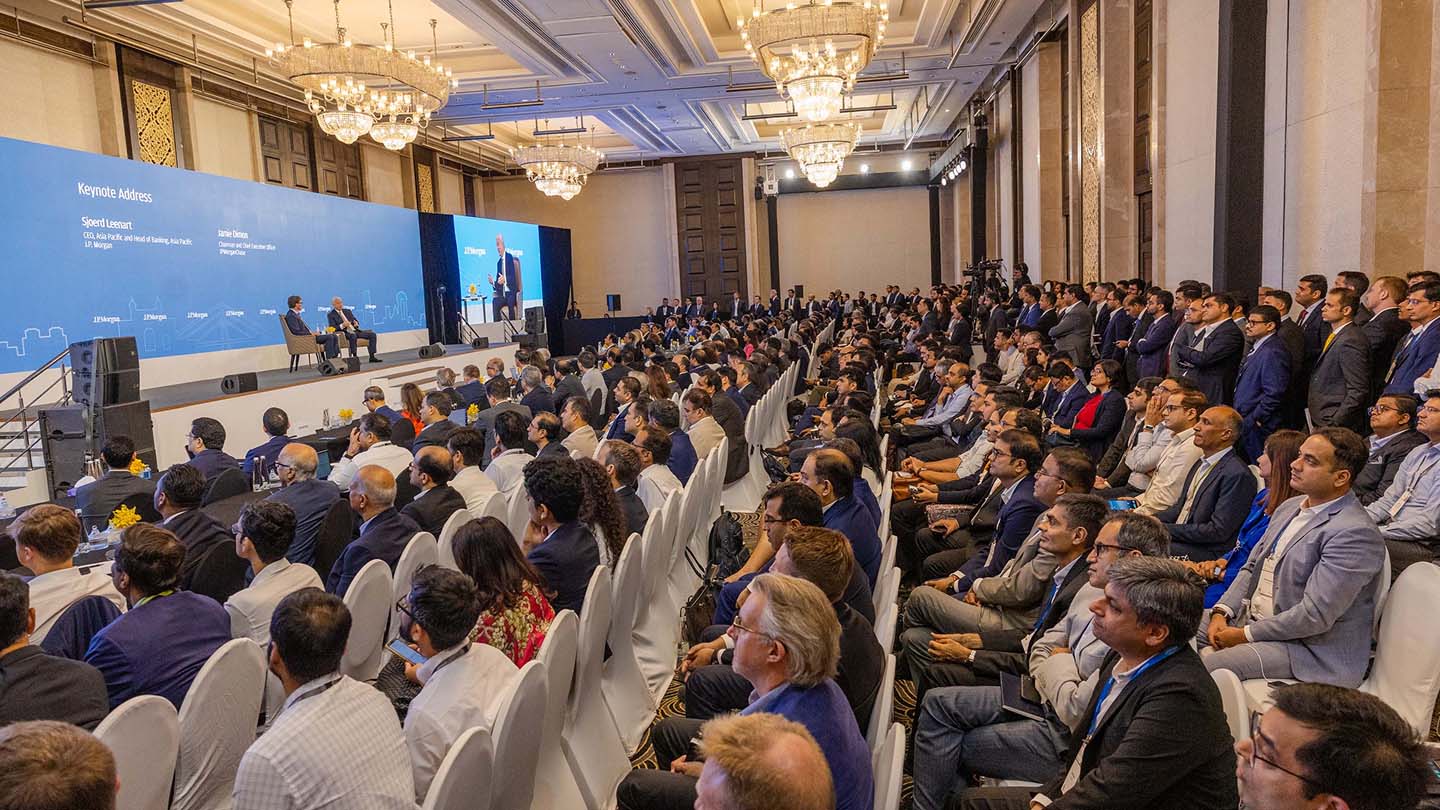
Conference photos
Making an impact
JPMorganChase has been making an impact in India since 1945.
$80B+
in credit and capital provided to clients across various industries since 2019
1.3M+
volunteer hours completed since 2018
$90M
in philanthropic contributions since 2015
331K+
Instances of improved financial health due to philanthropic programs
100,000+
people assisted in accessing promising career pathways since 2019
BANKING
Market signals and what they mean for companies in Asia Pacific
From diverging central bank policy to the AI investment boom and higher-for-longer energy prices,
GLOBAL CORPORATE BANKING
Perspectives from Asia Pacific
Explore Global Corporate Banking's Asia Pacific market outlook.
PAYMENTS
J.P. Morgan Payments in Asia-Pacific
At J.P. Morgan, we’re thinking differently about the power of payments. Let us help you rethink what payments can do for you.
This conference is by invitation only and is not transferable. The conference is not open to the media.