Key takeaways
- India's equity market is starting to emerge as an “AI hedge” — a liquid, large-weight market that global investors can rotate into when they trim or diversify away from volatile AI cycles.
- Earnings have been the missing engine for two years but are finally picking up, with large caps joining the recovery in mid and small caps.
- Oil prices, global bond yields and El Niño are the key macroeconomic factors that will likely shape the outlook not only for the second half of 2026 but also into 2027.
Why India is becoming the world’s AI hedge
Several factors make India’s stock market the natural non-AI hedge. India’s market thrives on foundational growth engines. It is large and liquid, with a weight of around 12% in the MSCI EM benchmark, while the main alternative — domestic China, at roughly 25% — is contending with a softer growth backdrop. Other non-AI havens, such as Southeast Asia, Latin America and emerging Europe, are too small to absorb large allocations.
India also benefits from fiscal and monetary policy that remain supportive of its economy. AI-driven markets such as Korea, Taiwan and Japan are delivering earnings growth ranging from 40% to more than 100% — levels India is in no position to match. The country’s appeal to global investors, however, is increasingly of a different kind. Rather than competing on AI earnings power, India is emerging as a safe haven for those looking to diversify away from, or trim, crowded AI exposures.
“When investors go looking for non-AI exposure, India increasingly becomes the default choice.”

Rajiv Batra
Head of Asia & co-head of Global Emerging Markets Equity Strategy at J.P. Morgan
“When global markets take a hit because investors are trimming or diversifying out of the AI story, India comes out as one of the bigger hedges — partly because of its sheer size in the benchmark and partly because fiscal and monetary policy are still working to support the domestic economy,” said Rajiv Batra, head of Asia and co-head of Global Emerging Markets Equity Strategy at J.P. Morgan.
While India does have AI-linked names spanning tech hardware, data centers, chips and power, these have rallied on valuation re-rating rather than on AI-driven earnings, which have yet to come through.
“When investors go looking for non-AI exposure, India increasingly becomes the default choice,” added Batra.
Are India’s earnings finally turning a corner?
For two years, India’s equity market lacked momentum. Growth was slowing, the benefits of twin easing had yet to materialize and earnings — the engine that ultimately drives returns — were simply not delivering. Now, earnings are finally coming through.
The recovery started in mid- and small-cap companies, which have delivered earnings growth of 25% or more for six to seven consecutive quarters. The bigger shift is that large caps have now joined them, posting double-digit growth over the past two quarters — or high-teens once oil marketing companies (OMCs), squeezed by higher oil prices, are stripped out.
Earnings have picked up across the board, led by small and mid-caps
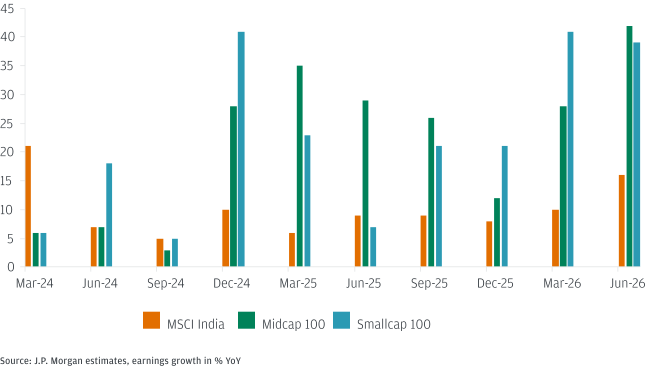
Earnings have picked up across the board, with small- and mid-caps’ earnings continuing to outpace those of large-caps.
“This is the missing piece we have been waiting for. After two years in which earnings were the one thing India lacked, growth is now broadening — and the fact that it is reaching large caps tells us the easing cycle is working,” said Batra.
Despite the large-cap momentum, J.P. Morgan Global Research is maintaining its full year (FY) 2027 earnings growth forecast at around 10.4–11%. Last year’s tax-cut tailwinds are starting to fade and oil prices remain high — both of which are expected to weigh on growth later next year.
Global investors are expressing the trade through mid and small caps
Investor positioning has yet to catch up with the earnings recovery, and the gap is clearest in the flow and ownership data. Over the past two years, India slipped from a long-standing overweight for emerging market (EM) and Asia ex-Japan funds to an underweight, held back by high valuations and, until recently, weak earnings. As a result, most major global funds still hold less exposure to Indian equities than their benchmarks imply — and closing that gap could translate into potential net inflows of around $115 billion.
That shift is now tentatively beginning. Foreign investors have turned net buyers for a second consecutive month, with inflows of around $3 billion in August, drawn by India’s improving earnings, a stabilizing currency and a rotation of global capital toward the non-AI cohort. Most of that buying has gone into consumer services, including e-commerce and hotels, along with metals, mining and healthcare.
But this return is not yet broad-based. Foreign ownership in large caps has fallen from a peak of around 24% in December 2020 to 17.6% in mid-2026, the lowest in over a decade, while mid- and small-cap holdings have held steady. Large caps, where the earnings recovery is now most visible, have yet to see foreign positioning turn — a gap that could close as the profit cycle broadens.
“India’s growth story looks most attractive on a sector-specific or thematic basis. On valuation versus growth alone, in relative terms it takes a backseat — which is why foreign investors are finding their exposure through the mid- and small-cap space,” said Batra.
Foreign buying has resumed in recent months amid AI uncertainty
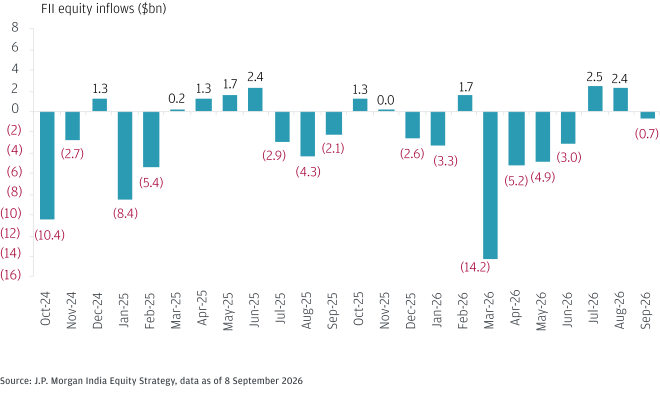
Foreign investors have turned net buyers in recent months, with inflows of $2.5 billion in July and $3 billion in August 2026, following a prolonged stretch of selling.
Domestic institutional investors (DIIs) continue to play a stabilizing role, having been net buyers for 37 consecutive months, with inflows of around $6 billion in August alone. Domestic investors now own more of the market than their foreign counterparts — a reversal of the picture a decade ago and a key reason why Indian stocks can serve as a reliable non-AI hedge even when foreign flows turn volatile.
Issuance is another factor. There is significant activity in the primary market:IPOs, share placements and stake sales continue to divert capital from the secondary market. August alone saw a record $12.7 billion of fundraising, with a strong pipeline of large issuances expected to keep absorbing liquidity.
Three macroeconomic factors that could shape the outlook
Beyond flows and earnings, three macro variables will likely shape India’s path from here — not just for the rest of the year, but into 2027 and beyond.
Oil is the biggest swing factor
India’s twin deficits, its currency and its inflation all move with the price of oil, which makes it the single most important variable to watch. J.P. Morgan Global Research forecasts assume Brent averages roughly $80–85 a barrel (bbl). Below that level, the picture improves; above it, the pressure on growth and the deficits builds quickly.
The relationship is direct: every $10/bbl rise in the price of oil worsens India’s current account deficit by around 0.5% of GDP. J.P. Morgan Global Research’s base case already sees the deficit widening to $55 billion (1.4% of GDP) in FY27, from $25 billion the year before, largely on higher oil. A sustained move well above $90/bbl would force those numbers wider and growth forecasts lower.
Global interest rates
Rising global bond yields are narrowing the gap between Indian and U.S. rates, adding pressure on the Reserve Bank of India (RBI). Even before any homegrown inflation shock, a tighter global backdrop limits how much room the RBI has to keep supporting growth — and any shift in policy tends to feed through to the economy with a lag of several quarters.
El Niño
The third variable is climate patterns. Growth has so far proved resilient despite El Niño conditions — the economy grew a strong 7.8% in the first quarter of 2026 — but the risk is building. A strengthening El Niño could disrupt the monsoon, and because food is a large share of India’s inflation basket, any price spike would quickly feed through to headline inflation.
Average sector returns during the previous two Super El Niño years
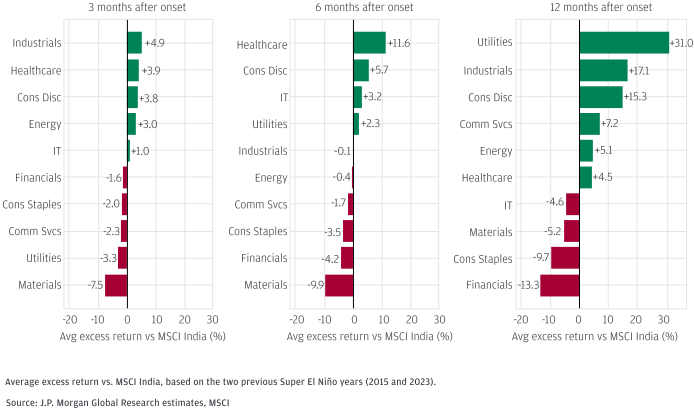
In the two previous Super El Niño years (2015 and 2023), defensive and consumption-linked sectors led in the early months, before cyclicals and utilities took over.
That could prompt the RBI to raise rates sooner than markets expect, eventually slowing the recovery now underway. J.P. Morgan Global Research sees FY27 growth of 6.5–7%, which already factors in a modest El Niño downgrade.
El Niño typically weighs on rural- and agriculture-linked sectors, while companies tied to irrigation, water management and agricultural infrastructure can benefit from the investment it spurs. The market response, though, tends to be more nuanced. In the two previous Super El Niño years (2015 and 2023), defensive and consumption-linked sectors led early, before a broader cyclical and utilities-led rotation took over in the following year.
"Oil, global rates and the monsoon are what I’d watch from here — they’ll set the direction not just for the coming months, but well into 2027 and beyond," added Batra.
Related insights
-

Global Research
The 11th annual J.P. Morgan India Conference returns to Mumbai on September 21-22, 2026.
-
Banking
Market signals and what they mean for companies in Asia Pacific
September 16, 2026
From diverging central bank policy to the AI investment boom and higher-for-longer energy prices, J.P. Morgan's Global Corporate Banking leaders unpack the macro forces reshaping the region — and what they mean for companies.
-
Global Research
From tariffs to capex to geopolitics, here are the forces shaping price formation for industrial metals.
This communication is provided for information purposes only. Please read J.P. Morgan research reports related to its contents for more information, including important disclosures. JPMorgan Chase & Co. or its affiliates and/or subsidiaries (collectively, J.P. Morgan) normally make a market and trade as principal in securities, other financial products and other asset classes that may be discussed in this communication.This communication has been prepared based upon information, including market prices, data and other information, from sources believed to be reliable, but J.P. Morgan does not warrant its completeness or accuracy except with respect to any disclosures relative to J.P. Morgan and/or its affiliates and an analyst's involvement with any company (or security, other financial product or other asset class) that may be the subject of this communication. Any opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice. Past performance is not indicative of future results. This communication is not intended as an offer or solicitation for the purchase or sale of any financial instrument. J.P. Morgan Research does not provide individually tailored investment advice. Any opinions and recommendations herein do not take into account individual client circumstances, objectives, or needs and are not intended as recommendations of particular securities, financial instruments or strategies to particular clients. You must make your own independent decisions regarding any securities, financial instruments or strategies mentioned or related to the information herein. Periodic updates may be provided on companies, issuers or industries based on specific developments or announcements, market conditions or any other publicly available information. However, J.P. Morgan may be restricted from updating information contained in this communication for regulatory or other reasons. Clients should contact analysts and execute transactions through a J.P. Morgan subsidiary or affiliate in their home jurisdiction unless governing law permits otherwise.This communication may not be redistributed or retransmitted, in whole or in part, or in any form or manner, without the express written consent of J.P. Morgan. Any unauthorized use or disclosure is prohibited. Receipt and review of this information constitutes your agreement not to redistribute or retransmit the contents and information contained in this communication without first obtaining express permission from an authorized officer of J.P. Morgan.