Version 1 - Primary Nav Search

Key takeaways

  • The Iran war’s estimated cost in 2026 was about $2,000 per U.S. household, according to an analysis by Moody’s. That includes energy-related costs, the impact of higher interest rates and military spending.
  • Fuel prices have risen sharply in 2026. From the war’s start in February through early November, regular gasoline prices rose 31% and diesel prices surged 66%.
  • Costs extend beyond the pump: Higher diesel and freight expenses raise costs for businesses that produce and deliver goods, putting pressure on consumer prices and contributing to inflation.
  • J.P. Morgan Wealth Management’s investment strategists expect annual inflation to moderate to a range of 2.3% to 2.5% by the end of 2027 as energy pressures fade.

Contributors

Sergei Klebnikov

Editorial Staff, J.P. Morgan Wealth Management


The Iran war has taken a bite out of American household budgets – and the cost goes well beyond the gas pump. Higher fuel and shipping costs have made it more expensive to produce and deliver everyday goods, while the energy shock has pushed up inflation and borrowing costs.

Moody’s estimated in October that the war had cost about $2,000 per U.S. household on average. That figure covers the broader economic burden: higher energy-related costs, the effects of higher interest rates and a share of military spending. It doesn't mean every family paid an extra $2,000 directly, and the broader economy has held up better than those costs might suggest.

The recent decline in oil prices might suggest that relief is on the way. Brent crude oil was down to $94 on November 12, just a few weeks after it peaked at roughly $118 per barrel in October. But cheaper oil does not immediately bring down diesel and freight costs, much less reverse price increases that have already reached consumers.

According to J.P. Morgan Wealth Management investment strategists, much of this year’s inflation has come from the Iran conflict and energy price shock that followed.

“The material move higher in energy prices resulting from the U.S.-Iran conflict has had a profound effect on the incremental costs for the U.S. consumer as well as the reaction function from the Federal Reserve to adapt to higher than expected inflation rates in 2026,” J.P. Morgan Wealth Management’s Chief Investment Strategist Phil Camporeale said. “At the same time, there have been very important shock absorbers for the US economy that have kept growth and earnings on track.”

For households and investors, the question now isn’t just how much the war has cost, but how long those costs will linger. In this article, we break down what’s in the household-cost estimate, why the impact reaches beyond gasoline and what could determine how long cost pressures last.

How much has the Iran war cost U.S. households?

Energy makes up the largest part of Moody’s roughly $2,000-per-household cost estimate, with about $1,100 of that coming from higher fuel prices. And that covers more than what drivers pay at the gas pump – it also includes the higher cost of goods and services that rely on trucking, shipping and air freight.

Another $540 per household reflects the impact of higher interest rates across the economy, and about $360 is each household’s share of the cost of U.S. military operations.

While the overall figure measures the economic drag on American households, it does not list the bills they paid. Most families didn't pay a separate charge for higher interest rates or military operations. But those costs still reach household finances through more expensive borrowing and federal spending that taxpayers fund. From the start of the war in February through late October, the U.S. military has spent more than $47 billion, according to Pentagon estimates.4

Fuel-cost trackers give a narrower, more recent view. Brown University’s Iran War Energy Cost Tracker estimates that Americans have in total paid $158 billion more for gasoline and diesel since the war began than they likely would have without it. As of November 12, that comes to about $1,206 per household.5

The Institute on Taxation and Economic Policy (ITEP), meanwhile, puts the fuel cost from the war at $1,006 per household. That amount is split between $501 paid directly at the gas pump and $505 paid for higher prices elsewhere, as trucking companies, farmers and other businesses pass along their own higher fuel bills.6

Nationwide, drivers have paid only about half of the roughly $134.5 billion in added fuel costs, according to ITEP. Businesses have absorbed 47.5%, and governments have covered 2.6%. Those costs don't disappear. When trucking companies, farmers and local governments pay more for fuel, the costs often show up as higher grocery prices, lower business profits and reduced local services.7

How higher energy prices reach beyond the gas pump

The war’s most visible cost showed up at the gas station. The national average price of regular gasoline has risen 31% since the war began. It cost an average of $3.90 a gallon on November 12, up from $2.98 in late February.8

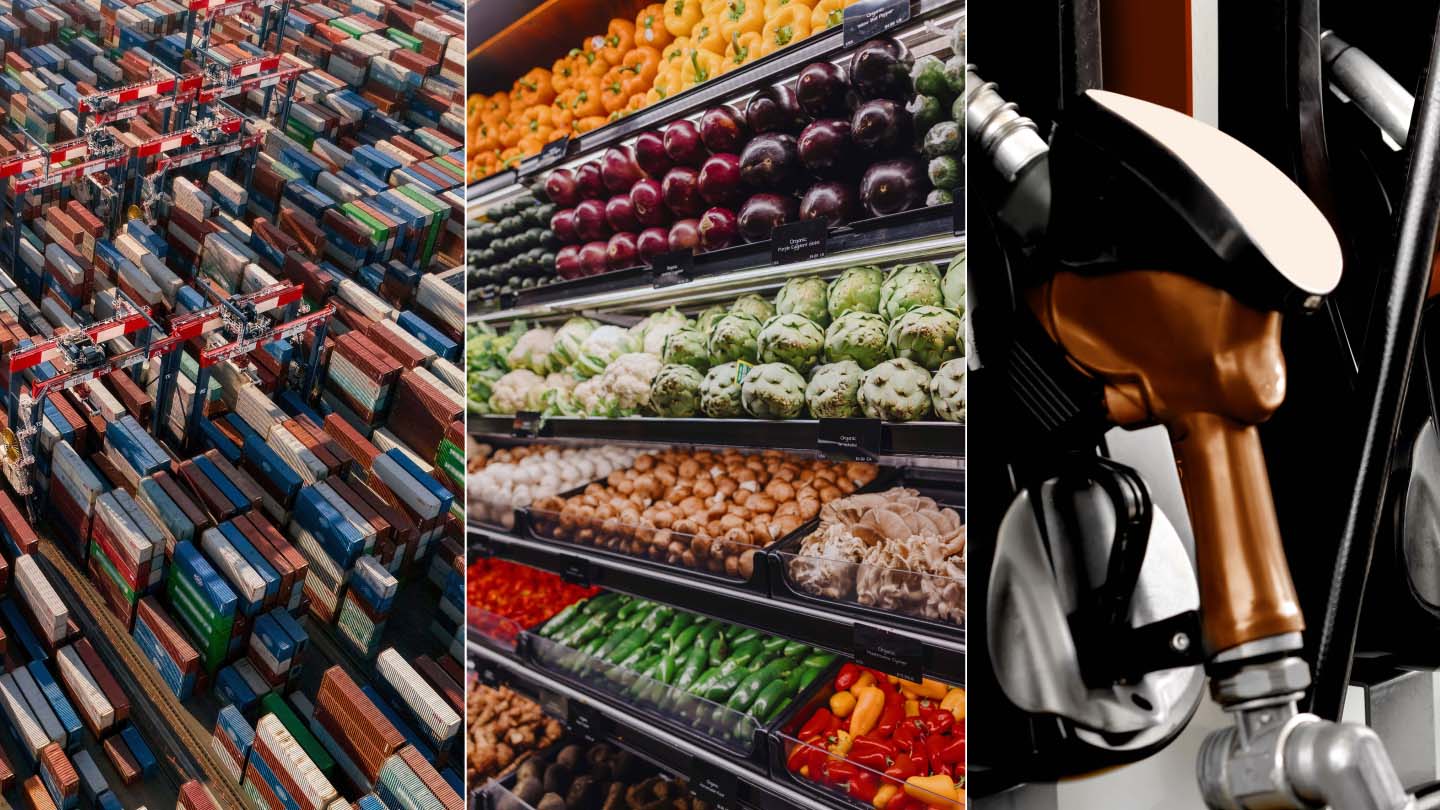
But the larger story is what happened next. As the conflict disrupted energy supplies and shipping routes in the Middle East, fuel and freight costs rose for the businesses that grow, make and deliver everyday goods. Those businesses then had to decide how much of those costs to absorb and how much to pass on to consumers in the form of higher prices.

Diesel is the clearest example of these hidden costs. Its price has climbed about 66% since the war began, to about $6.10 a gallon, up from $3.67. Few households fill up with diesel, but essential industries like trucking, farming, construction and distribution depend on it. That cost is built into the price of groceries, home deliveries and almost anything that travels by truck before it reaches a store shelf.

Those costs are now showing up in what companies charge, with several consumer goods companies mentioning this on recent earnings calls. Procter & Gamble, for instance, said higher energy, freight and raw material costs were among the contributing factors to an estimated $1.4 billion decline in profit for fiscal year 2027, even as its sales have held steady. Coca-Cola also cited higher logistics and transportation costs, while its executives said pressure on consumers could extend into 2027.

Not every company passes costs along the same way or at the same speed, though. Some absorb part of the hit through lower profit margins. PepsiCo, for example, took a margin hit last quarter and has gone back and forth between price increases and cuts in 2026 to support sluggish sales.12 Others may adjust promotions or raise prices gradually to keep customers. Nestle's chief financial officer said on an earnings call in October that the company will raise prices “to the extent we can without damaging medium-term consumer penetration.”13

What has the Iran war meant for inflation and interest rates?

Higher gasoline prices show up directly in household budgets. The broader effect comes as elevated energy and transportation costs put pressure on businesses’ expenses – and, in turn, on the prices of goods and services. J.P. Morgan Wealth Management investment strategists view the Iran conflict and the related energy shock as major contributors to U.S. inflation this year.

That inflation pressure has helped keep central banks hawkish and contributed to higher bond yields. The U.S. 10-year Treasury yield surged to over 5% in fall 2026 – from just over 4% at the start of 2026, with the conflict’s inflationary impact one factor among several. Higher yields can feed into borrowing costs, including mortgage rates, making home purchases and other interest-sensitive purchases more expensive.

The U.S. economy has proven to be resilient in the face of higher energy costs

Despite the shock of higher energy costs, U.S. GDP growth has been above trend in 2026 and probabilities of recession remain low into 2027, according to J.P. Morgan Wealth Management investment strategists. Part of the reason is who does most of the spending. Higher-income households account for a large share of U.S. consumer spending, and fuel takes up a smaller portion of their budgets, leaving them better insulated from the spike in oil and gas prices.

Stock market gains have helped, too. Our strategists say rising stock prices have supported consumer spending, more than offsetting the aggregate drag from higher rates and energy costs. Stocks have broadly moved higher in 2026, with the S&P 500 posting a year-to-date price return of nearly 12% by early November.15

Fiscal policy has provided another cushion. Tax provisions in the One Big Beautiful Bill Act (OBBBA), signed into law in July 2025, have put more money in many households' pockets this year, offsetting much of the hit from higher gas prices.16

Why falling oil prices may not bring immediate relief

Lower oil prices can ease some pressure, but they do not immediately lower the cost of diesel, shipping or goods already affected by higher fuel expenses. In early November, U.S. diesel futures fell less than Brent crude, while diesel refining margins remained well above their levels at the start of the year. Tanker rates also remained elevated, reflecting the cost of transporting energy through disrupted routes.

The year-over-year inflation rate was 3.7% in September (note: there is no annual inflation rate for October 2026 due to the 2025 government shutdown).17 J.P. Morgan Wealth Management investment strategists anticipate a softening in oil prices and inflation next year, expecting a phased agreement over the Strait of Hormuz to help bring Brent crude toward $75 a barrel by year-end 2027. Our strategists forecast that inflation will ease to roughly 2.3% to 2.5% by then as energy pressures ease.

That outlook depends on diminishing disruptions in the energy market. Even if crude prices fall, relief may reach fuel, freight, goods and borrowing costs at different speeds. Lower oil prices could ease future pressure on household budgets, but they cannot reverse costs families have already incurred.

References

1.

The Hill, “Iran War Costing U.S. Households Average of $2K Each: Moody’s.” (October 13, 2026)

2.

U.S. Energy Information Administration (EIA), “Spot Prices for Crude Oil and Petroleum Products.” (Accessed November 12, 2026)

3.

The Hill, “Iran War Costing U.S. Households Average of $2K each: Moody’s.” (October 13, 2026)

4.

Reuters, “U.S. Costs of Iran War Rise to Over $47 Billion, According to Pentagon Estimate.” (October 27, 2026)

5.

Brown University Watson School of International and Public Affairs, “Iran War Energy Cost Tracker.” (Accessed November 12, 2026)

6.

Institute on Taxation and Economic Policy (ITEP), “What Higher Fuel Prices Are Really Costing You.” (Accessed November 12, 2026)

7.

ITEP, “What Higher Fuel Prices Are Really Costing You.” (Accessed November 12, 2026)

8.

Brown University Watson School of International and Public Affairs, “Iran War Energy Cost Tracker.” (Accessed November 12, 2026)

9.

Brown University Watson School of International and Public Affairs, “Iran War Energy Cost Tracker.” (Accessed November 12, 2026)

10.

Reuters, “P&G Warns of Bigger Cost Hit From Oil Prices, Even as Consumer Demand Holds Up.” (October 22, 2026)

11.

Reuters, “Coca-Cola Lifts Profit Forecast on International Soda Demand, Flags Higher Costs.” (October 27, 2026)

12.

Reuters, “PepsiCo Slashes Forecast, Deepens Cost Cuts as North America Recovery Drags.” (October 8, 2026)

13.

Reuters, “Food and Household Brands Warn of More Price Hikes as Iran War Costs Bite.” (October 28, 2026)

14.

CNBC, “U.S. 10 Year Treasury.” (Accessed November 12, 2026)

15.

S&P Dow Jones Indices, “S&P 500.” (Accessed November 12, 2026)

16.

IRS, “Working Families Tax Cuts.” (Accessed November 13, 2026)

17.

Bureau of Labor Statistics, “Consumer Price Index – September 2026.” (October 14, 2026)

Connect with a Wealth Advisor

Reach out to your Wealth Advisor to discuss any considerations for your current portfolio. If you don’t have a Wealth Advisor, click here to tell us about your needs and we’ll reach out to you.

Connect now


IMPORTANT INFORMATION

This material is for informational purposes only, and may inform you of certain products and services offered by J.P. Morgan’s wealth management businesses, part of JPMorgan Chase & Co. (“JPM”). Products and services described, as well as associated fees, charges and interest rates, are subject to change in accordance with the applicable account agreements and may differ among geographic locations. Not all products and services are offered at all locations. If you are a person with a disability and need additional support accessing this material, please contact your J.P. Morgan team or email us at accessibility.support@jpmorgan.com for assistance. Please read all Important Information.

The S&P 500 Index is widely regarded as the best single gauge of large-cap U.S. equities and serves as the foundation for a wide range of investment products. The index includes 500 leading U.S. companies and captures approximately 80% coverage of available market capitalization. 

Equities: The price of equity securities may rise or fall due to the changes in the broad market or changes in a company's financial condition, sometimes rapidly or unpredictably. Equity securities are subject to 'stock market risk' meaning that stock prices in general may decline over short or extended periods of time. 

Bonds: In general, the bond market is volatile and bond prices rise when interest rates fall and vice versa. Longer term securities are more prone to price fluctuation than shorter term securities. Any fixed income security sold or redeemed prior to maturity may be subject to substantial gain or loss. Dependable income is subject to the credit risk of the issuer of the bond. If an issuer defaults no future income payments will be made. 

Commodities: Changes in economic and market conditions, interest rate risk, and lack of liquidity may affect equity performance. Investments in equity structures entail certain risk factors and investments in commodities may have greater volatility than investments in traditional securities. The value of commodities may be affected by changes in overall market movements, commodity index volatility, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. Investing in commodities creates an opportunity for increased return but, at the same time, creates the possibility for greater loss. 


GENERAL RISKS & CONSIDERATIONS
. 
Any views, strategies or products discussed in this material may not be appropriate for all individuals and are subject to risks. Investors may get back less than they invested, and past performance is not a reliable indicator of future results. Asset allocation/diversification does not guarantee a profit or protect against loss. Nothing in this material should be relied upon in isolation for the purpose of making an investment decision. You are urged to consider carefully whether the services, products, asset classes (e.g. equities, fixed income, alternative investments, commodities, etc.) or strategies discussed are suitable to your needs. You must also consider the objectives, risks, charges, and expenses associated with an investment service, product or strategy prior to making an investment decision. For this and more complete information, including discussion of your goals/situation, contact your J.P. Morgan representative.

NON-RELIANCE. Certain information contained in this material is believed to be reliable; however, JPM does not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which are provided for illustration/reference purposes only. The views, opinions, estimates and strategies expressed in this material constitute our judgment based on current market conditions and are subject to change without notice. JPM assumes no duty to update any information in this material in the event that such information changes. Views, opinions, estimates and strategies expressed herein may differ from those expressed by other areas of JPM, views expressed for other purposes or in other contexts, and this material should not be regarded as a research report. Any projected results and risks are based solely on hypothetical examples cited, and actual results and risks will vary depending on specific circumstances. Forward-looking statements should not be considered as guarantees or predictions of future events.

Nothing in this document shall be construed as giving rise to any duty of care owed to, or advisory relationship with, you or any third party. Nothing in this document shall be regarded as an offer, solicitation, recommendation or advice (whether financial, accounting, legal, tax or other) given by J.P. Morgan and/or its officers or employees, irrespective of whether or not such communication was given at your request. J.P. Morgan and its affiliates and employees do not provide tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transactions.

Legal Entity and Regulatory Information.

J.P. Morgan Wealth Management is a business of JPMorgan Chase & Co., which offers investment products and services through J.P. Morgan Securities LLC (JPMS), a registered broker-dealer and investment adviser, member FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. Certain custody and other services are provided by JPMorgan Chase Bank, N.A. (JPMCB). JPMS, CIA and JPMCB are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.

Bank deposit accounts and related services, such as checking, savings and bank lending, are offered by JPMorgan Chase Bank, N.A. Member FDIC.

This document may provide information about the brokerage and investment advisory services provided by J.P. Morgan Securities LLC (“JPMS”). The agreements entered into with JPMS, and corresponding disclosures provided with respect to the different products and services provided by JPMS (including our Form ADV disclosure brochure, if and when applicable), contain important information about the capacity in which we will be acting. You should read them all carefully. We encourage clients to speak to their JPMS representative regarding the nature of the products and services and to ask any questions they may have about the difference between brokerage and investment advisory services, including the obligation to disclose conflicts of interests and to act in the best interests of our clients.

J.P. Morgan may hold a position for itself or our other clients which may not be consistent with the information, opinions, estimates, investment strategies or views expressed in this document. JPMorgan Chase & Co. or its affiliates may hold a position or act as market maker in the financial instruments of any issuer discussed herein or act as an underwriter, placement agent, advisor or lender to such issuer.