Version 1 - Primary Nav Search

Key takeaways

  • Diesel prices hit several new records, surging to over $6 per gallon in September. They are rising faster than gasoline prices, and that matters disproportionately because diesel is a core input for freight, heavy industry, agriculture and construction.
  • Higher diesel prices can show up in inflation through business costs first, then potentially affect consumer prices over time depending on pass-through and demand.
  • For investor portfolios, the main issues are inflation expectations, rate sensitivity and which sectors have pricing power versus thin margins.

Contributors

Sergei Klebnikov

Editorial Staff, J.P. Morgan Wealth Management

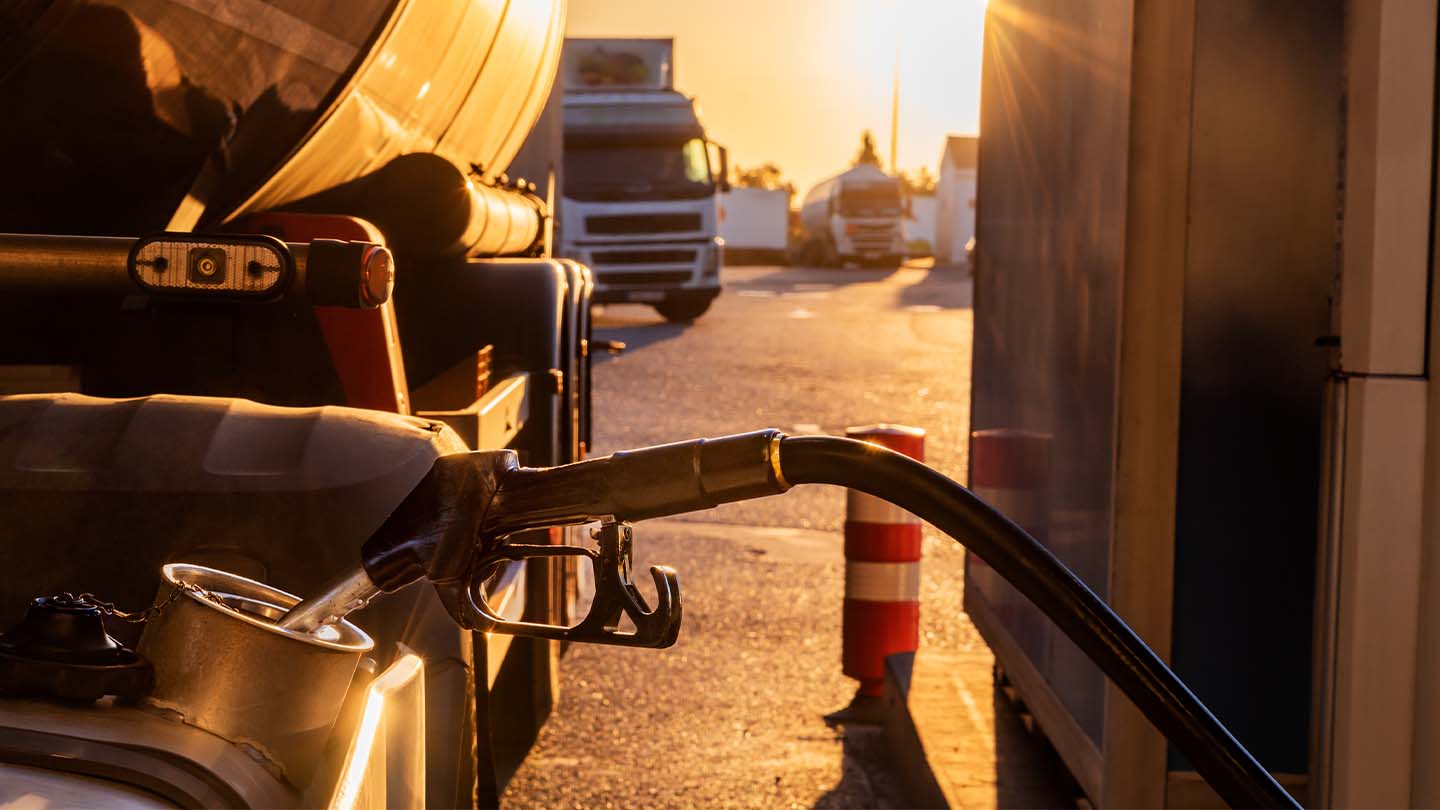
Gas prices may be all over the headlines, but diesel prices set several new record highs in early September as geopolitical disruptions and refinery outages tightened global supply. The average price of diesel hit $6.23 per gallon on September 14, the highest level on record, according to AAA. That’s a nearly 69% increase from this time last year, when prices averaged $3.69 a gallon.1

Diesel prices have also risen more than gasoline prices – and that difference matters. Diesel is the fuel that moves goods, powers heavy equipment and supports key parts of the industrial economy, so price spikes can travel quickly from energy markets into business costs, inflation and, ultimately, investor portfolios.2

What’s driving diesel prices higher right now?

Diesel and gasoline are both refined from crude oil, but they don’t always move in lockstep. Gasoline prices tend to be driven by consumer driving patterns. Diesel is more tightly linked to commercial demand such as freight, construction, agriculture and industrial activity. So, when diesel supply tightens, the price impact can be broader and faster to reach businesses.

A big part of the run-up in prices is geopolitical disruption. Two pressure points have been front and center recently: the ongoing conflict involving Iran – which has raised risks around energy flows through key Middle East routes – and Russia – where refinery disruptions and policy responses have reduced the availability of products for export.3 What’s more, Iran-related risks have pushed crude oil above $100 per barrel several times this year, adding broad pressure to energy markets.4

Diesel can also behave differently than gasoline because it comes from a different part of the barrel and competes for the same refinery capacity as other distillates, such as jet fuel and heating oil.5 That matters because refiners can’t instantly make more diesel without trade-offs, and diesel inventories can be less forgiving when they’re already lean. Add in seasonal demand – like farmers pulling more diesel during harvest season or demand for heating fuels rising later in the year – and the setup can amplify price swings.6

Here are some things investors may want to watch next:

  • Refinery operations: Outages, utilization and seasonal maintenance that can tighten distillate supply quickly.
  • Distillate inventories: Whether diesel stockpiles are rebuilding or staying thin.
  • Geopolitical risk: Developments tied to the Middle East (shipping routes/flows) and Russia (refining/export availability).
  • Demand signals: Freight and industrial activity, which can either reinforce tightness or cool pricing if growth slows.

How diesel impacts inflation and isn't just an energy headline

When people think about energy-driven inflation, they often focus on gasoline. But diesel can matter just as much, if not more, because it’s a behind-the-scenes cost for businesses. Diesel powers freight and heavy equipment, so when prices jump, that may raise the cost of making and delivering everyday goods.

The ripple effect is usually straightforward. Costs rise first in diesel-heavy parts of the economy such as shipping, farming, construction and manufacturing. Businesses then decide how to respond: Absorb the hit (lower profits), pass it through (institute higher prices or fees, including fuel surcharges) or cut costs elsewhere. How much consumers feel depends on demand and how much pricing power companies have.

Diesel can feed inflation directly through higher fuel costs, but more often the effect is indirect – through transportation and delivery costs that move through supply chains. And because many firms hedge fuel, lock in shipping contracts or compete in markets where price hikes are tough, the impact can be delayed or uneven.

A helpful way to track the story is to consider producer prices as an early signal. The Producer Price Index (PPI) reflects what businesses receive for goods and services, and it also tends to reveal cost pressures earlier in the supply chain. The Consumer Price Index (CPI), meanwhile, shows what households ultimately pay. In other words, diesel can show up in producer cost data before it becomes a consumer inflation story.

Shipping and freight: Where diesel shows up most clearly

One of the places higher diesel prices can show up sooner than later is in shipping and logistics. Shipping costs are broadly defined as several moving pieces: trucking and freight rates, fuel surcharges, and last-mile delivery, as well as other behind-the-scenes expenses like storing, routing, and moving inventory from factories to warehouses to store shelves.

Fuel surcharges are the key link. Many freight contracts separate the base shipping rate from a fuel add-on that rises and falls with diesel price benchmarks. That structure can shift who bears the cost. Sometimes carriers absorb more of the fuel move, sometimes shippers pay it directly and sometimes it eventually shows up in consumer prices – especially when cost pressures last long enough to be renegotiated into contracts.7

The impact tends to be most visible in goods that are transport-heavy or operationally sensitive. These include categories like food distribution, building materials and retail replenishment, all of which can be exposed because they move frequently, ship in bulk or rely on tight delivery windows. Indeed, time-sensitive supply chains often feel the effects first because there is less flexibility to slow shipments, consolidate loads or reroute efficiently.

One myth worth debunking is that when diesel prices rise, everything gets more expensive immediately. This is not true: Diesel is a meaningful input, but the pass-through effects typically depend on factors like delivery routes, contract terms and pricing power.

What higher diesel prices can mean for investors and portfolios

For investors, the key isn’t predicting where prices go next; rather, it’s understanding what sustained cost pressures could mean for inflation, interest rates and corporate profits. Diesel spikes don’t automatically change the long-term outlook, but they can shift the conversation if they start feeding into broader prices and expectations.

Higher diesel prices can affect portfolios by raising costs for the companies that investors own. Businesses that rely on transportation, delivery, construction, manufacturing or agriculture may see expenses rise, and if they cannot pass those costs on, profit margins and stock prices could come under pressure. If diesel also contributes to stickier inflation, it may influence interest-rate expectations, which can affect both stocks and bonds.

Here’s a practical checklist for investors to consider:

  • Revisit diversification and check for concentrated exposure to transport-intensive or margin-sensitive areas.
  • Stress-test your financial plan. How would it hold up if inflation stays firmer for longer (compared to a temporary fuel spike)?
  • Focus on goals and time horizons, not short-term moves.

References

1.

AAA, “Fuel Prices.” (Accessed September 14, 2026)

2.

U.S. Energy Information Administration (EIA), “Diesel Fuel Explained.” (Accessed September 10, 2026)

3.

Reuters, “U.S. Diesel Prices Hit Record High as Conflicts Intensify Supply Crunch.” (September 3, 2026)

4.

EIA, “Petroleum & Other Liquids – Spot Prices.” (Accessed September 10, 2026)

5.

EIA, “Petroleum & Other Liquids – Refinery Yield.” (Accessed September 10, 2026)

6.

The Wall Street Journal, “U.S. Retail Diesel Prices Hit Record High as Global Supply Tightens.” (September 4, 2026)

7.

EIA, “How Do I Calculate Diesel Fuel Surcharges?” (Accessed September 11, 2026)

Connect with a Wealth Advisor

Reach out to your Wealth Advisor to discuss any considerations for your current portfolio. If you don’t have a Wealth Advisor, click here to tell us about your needs and we’ll reach out to you.

Connect now

IMPORTANT INFORMATION

This material is for informational purposes only, and may inform you of certain products and services offered by J.P. Morgan’s wealth management businesses, part of JPMorgan Chase & Co. (“JPM”). Products and services described, as well as associated fees, charges and interest rates, are subject to change in accordance with the applicable account agreements and may differ among geographic locations. Not all products and services are offered at all locations. If you are a person with a disability and need additional support accessing this material, please contact your J.P. Morgan team or email us at accessibility.support@jpmorgan.com for assistance. Please read all Important Information.

Equities: The price of equity securities may rise or fall due to the changes in the broad market or changes in a company's financial condition, sometimes rapidly or unpredictably. Equity securities are subject to 'stock market risk' meaning that stock prices in general may decline over short or extended periods of time. 

Commodities: Changes in economic and market conditions, interest rate risk, and lack of liquidity may affect equity performance. Investments in equity structures entail certain risk factors and investments in commodities may have greater volatility than investments in traditional securities. The value of commodities may be affected by changes in overall market movements, commodity index volatility, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. Investing in commodities creates an opportunity for increased return but, at the same time, creates the possibility for greater loss. 

Bonds: In general, the bond market is volatile and bond prices rise when interest rates fall and vice versa. Longer term securities are more prone to price fluctuation than shorter term securities. Any fixed income security sold or redeemed prior to maturity may be subject to substantial gain or loss. Dependable income is subject to the credit risk of the issuer of the bond. If an issuer defaults no future income payments will be made.

Diversification does not ensure a profit or protect against loss.


GENERAL RISKS & CONSIDERATIONS
Any views, strategies or products discussed in this material may not be appropriate for all individuals and are subject to risks. Investors may get back less than they invested, and past performance is not a reliable indicator of future results. Asset allocation/diversification does not guarantee a profit or protect against loss. Nothing in this material should be relied upon in isolation for the purpose of making an investment decision. You are urged to consider carefully whether the services, products, asset classes (e.g. equities, fixed income, alternative investments, commodities, etc.) or strategies discussed are suitable to your needs. You must also consider the objectives, risks, charges, and expenses associated with an investment service, product or strategy prior to making an investment decision. For this and more complete information, including discussion of your goals/situation, contact your J.P. Morgan representative.

NON-RELIANCECertain information contained in this material is believed to be reliable; however, JPM does not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which are provided for illustration/reference purposes only. The views, opinions, estimates and strategies expressed in this material constitute our judgment based on current market conditions and are subject to change without notice. JPM assumes no duty to update any information in this material in the event that such information changes. Views, opinions, estimates and strategies expressed herein may differ from those expressed by other areas of JPM, views expressed for other purposes or in other contexts, and this material should not be regarded as a research report. Any projected results and risks are based solely on hypothetical examples cited, and actual results and risks will vary depending on specific circumstances. Forward-looking statements should not be considered as guarantees or predictions of future events.

Nothing in this document shall be construed as giving rise to any duty of care owed to, or advisory relationship with, you or any third party. Nothing in this document shall be regarded as an offer, solicitation, recommendation or advice (whether financial, accounting, legal, tax or other) given by J.P. Morgan and/or its officers or employees, irrespective of whether or not such communication was given at your request. J.P. Morgan and its affiliates and employees do not provide tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transactions.

Legal Entity and Regulatory Information.

J.P. Morgan Wealth Management is a business of JPMorgan Chase & Co., which offers investment products and services through J.P. Morgan Securities LLC (JPMS), a registered broker-dealer and investment adviser, member FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. Certain custody and other services are provided by JPMorgan Chase Bank, N.A. (JPMCB). JPMS, CIA and JPMCB are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.

Bank deposit accounts and related services, such as checking, savings and bank lending, are offered by JPMorgan Chase Bank, N.A. Member FDIC.

This document may provide information about the brokerage and investment advisory services provided by J.P. Morgan Securities LLC (“JPMS”). The agreements entered into with JPMS, and corresponding disclosures provided with respect to the different products and services provided by JPMS (including our Form ADV disclosure brochure, if and when applicable), contain important information about the capacity in which we will be acting. You should read them all carefully. We encourage clients to speak to their JPMS representative regarding the nature of the products and services and to ask any questions they may have about the difference between brokerage and investment advisory services, including the obligation to disclose conflicts of interests and to act in the best interests of our clients.

J.P. Morgan may hold a position for itself or our other clients which may not be consistent with the information, opinions, estimates, investment strategies or views expressed in this document.  JPMorgan Chase & Co. or its affiliates may hold a position or act as market maker in the financial instruments of any issuer discussed herein or act as an underwriter, placement agent, advisor or lender to such issuer.
Check the background of our firm and investment professionals on FINRA's BrokerCheck

To learn more about J.P. Morgan Wealth Management’s investment business, including our accounts, products and services, as well as our relationship with you, please review our J.P. Morgan Securities LLC Form CRS and Guide to Investment Services and Brokerage Products.

This website is for informational purposes only, and not an offer, recommendation or solicitation of any product, strategy service or transaction. Any views, strategies or products discussed on this site may not be appropriate or suitable for all individuals and are subject to risks. Prior to making any investment or financial decisions, an investor should seek individualized advice from a personal financial, legal, tax and other professional advisors that take into account all of the particular facts and circumstances of an investor's own situation. 

This website may provide information about the brokerage and investment advisory services provided by J.P. Morgan Securities LLC ("JPMS"). When JPMS acts as a broker-dealer, a client's relationship with us and our duties to the client will be different in some important ways than a client's relationship with us and our duties to the client when we are acting as an investment advisor. A client should carefully read the agreements and disclosures received (including our Form ADV disclosure brochure, if and when applicable) in connection with our provision of services for important information about the capacity in which we will be acting.

INVESTMENT AND INSURANCE PRODUCTS ARE:
• NOT FDIC INSURED • NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY • NOT A DEPOSIT OR OTHER OBLIGATION OF, OR GUARANTEED BY, JPMORGAN CHASE BANK, N.A. OR ANY OF ITS AFFILIATES • SUBJECT TO INVESTMENT RISKS, INCLUDING POSSIBLE LOSS OF THE PRINCIPAL AMOUNT INVESTED

J.P. Morgan Wealth Management is a business of JPMorgan Chase & Co., which offers investment products and services through J.P. Morgan Securities LLC (JPMS), a registered broker-dealer and investment adviser, member FINRA and SIPC Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. Certain custody and other services are provided by JPMorgan Chase Bank, N.A. (JPMCB). JPMS, CIA and JPMCB are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.

Please read additional Important Information in conjunction with these pages.