Version 1 - Primary Nav Search

Contributors

Kriti Gupta

Executive Director, Global Investment Strategist, J.P. Morgan Private Bank

Chris Baggini

Global Head of Equity Strategy

At the start of 2026, few investors expected an energy shock, a monetary policy pivot and the highest level of interest rates since 2002. Fewer still expected the S&P 500 to climb roughly 15% despite those headwinds. The reason is simple: Earnings have been far stronger than anyone anticipated.

The earnings supercycle remains intact. And more importantly, it’s becoming broader. Even as investors focus on valuation, policy debates or macroeconomic risks, over longer periods of time, it’s corporate earnings that ultimately drive the equity markets. And today, that backdrop remains the strongest in almost two decades.

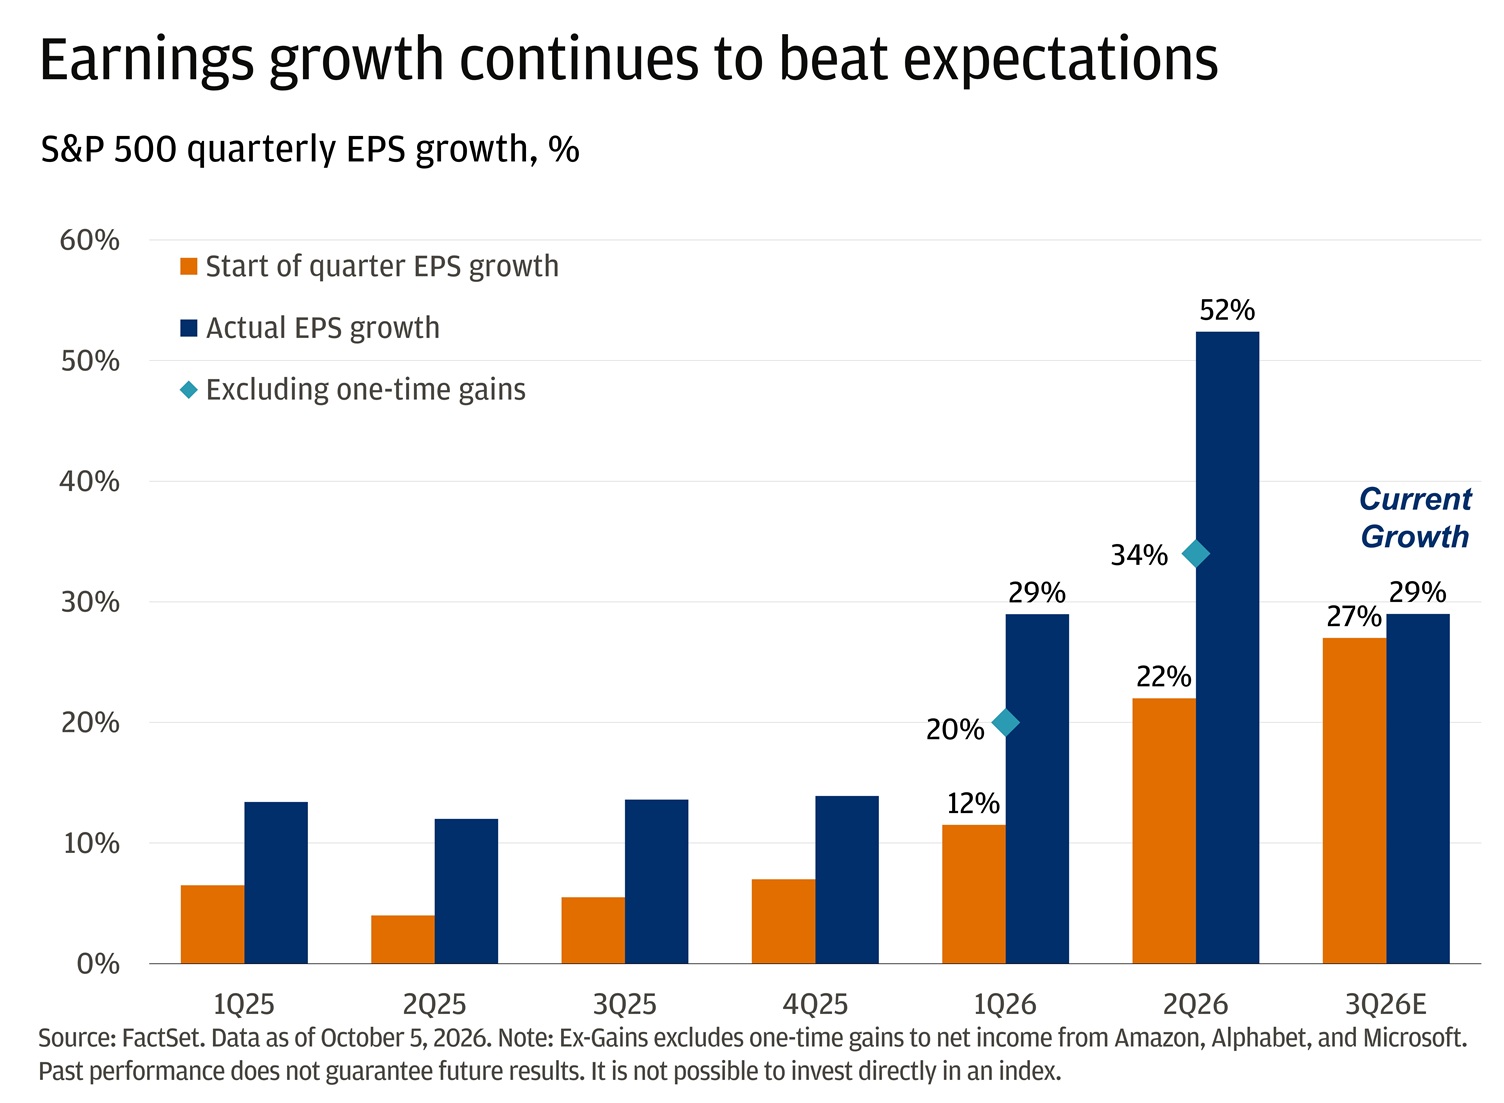
S&P 500 earnings growth is expected to increase approximately 29% year-over-year in the third quarter. If realized, it would mark eight consecutive quarters of double-digit earnings growth, the longest streak since the rebound that followed the global financial crisis.

Driving the upside

In the second quarter, S&P 500 earnings per share (EPS) grew 52% year-over-year. Even excluding one-time gains that boosted results for some large technology firms, that figure sits at 34%.

he bar chart compares S&P 500 quarterly EPS growth estimates made at the start of each quarter versus the actual reported growth and also shows an “ex-gains” for select quarters

Despite initial concerns around slowing economic activity, expectations for third-quarter sales growth have steadily moved higher and now sit at 12.1% – an estimate that’s only increased during the course of the summer, even as interest rates marched higher. That's well above what would typically be expected with the current pace of nominal economic growth. It reflects continued strength in artificial intelligence (AI) infrastructure spending and technology investment.

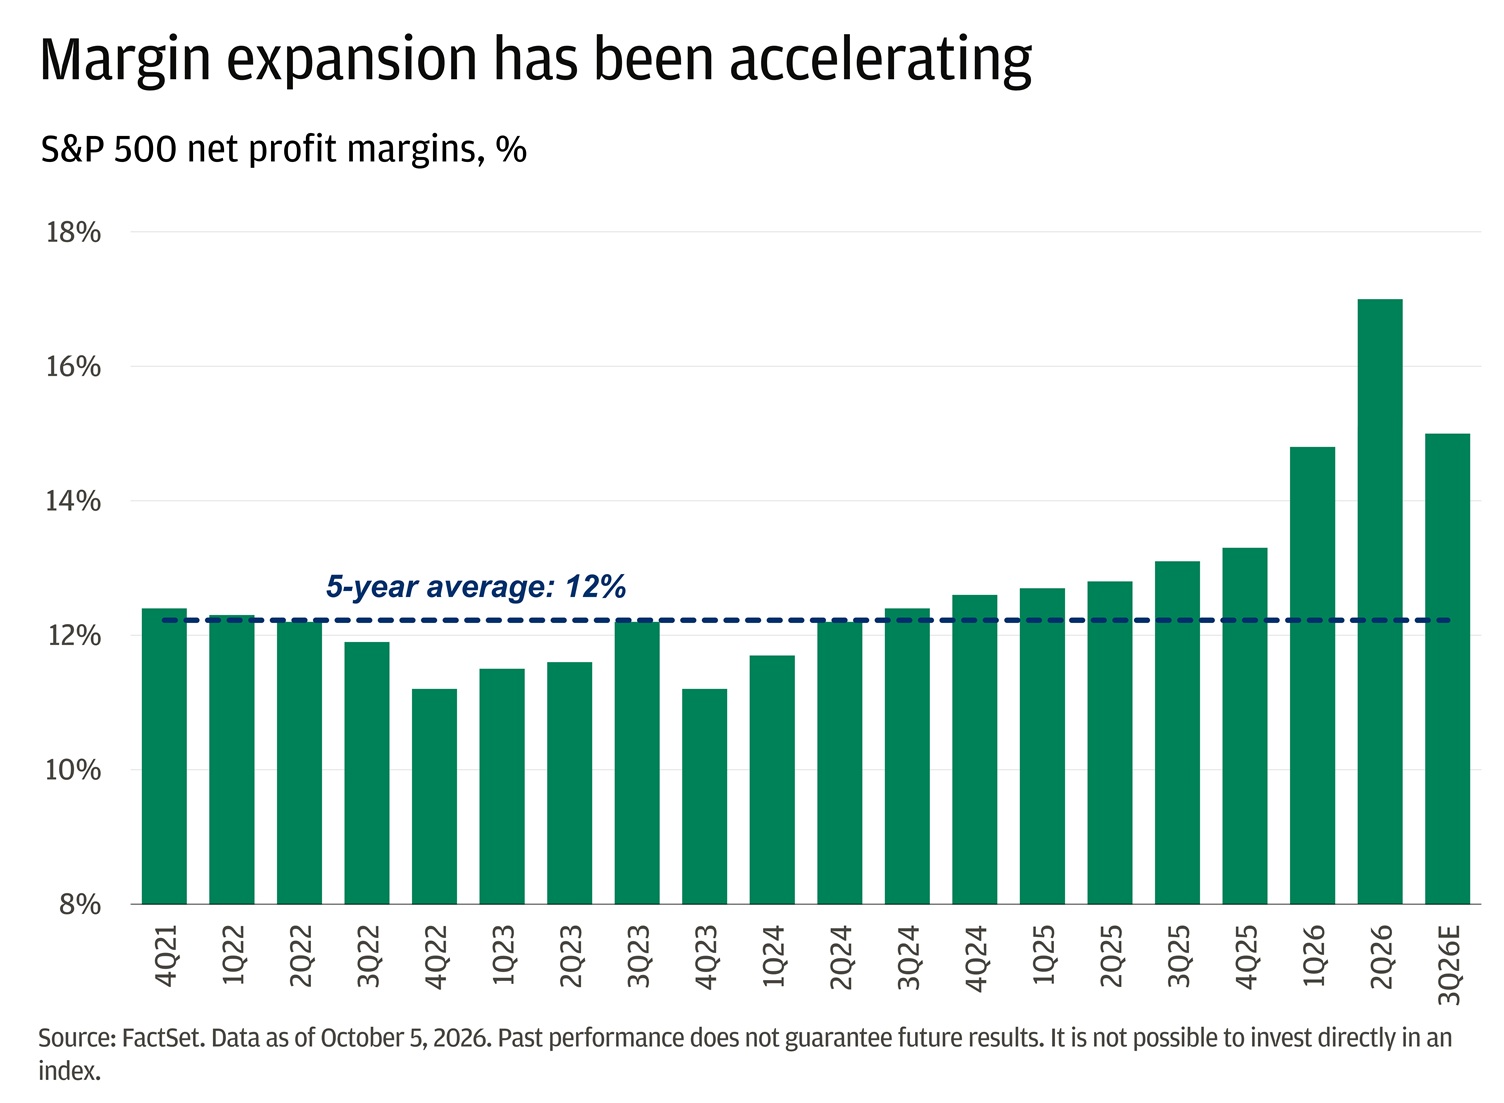
At the same time, companies continue to demonstrate an ability to protect profitability. That’s most visible in corporate margins. In the second quarter, net profit margin sat at 17%. In the third quarter, a modest decrease to 15% is expected, which still leaves profitability well above both last year’s level and the five-year average of 12.6%.

The bar chart shows S&P 500 net profit margins starting in late 2021 to 3rd quarter of 2026 (estimated)

Not just tech

While technology continues to lead the earnings story, it is no longer the only story. The information technology sector now makes up around 40% of the broader S&P 500, so strong tech reports will naturally have an outsized influence on index-level results. But beneath the surface, earnings growth is no longer confined to a small group of winners. While five of the 11 S&P 500 sectors are expected to deliver growth above 10% this quarter, as many as seven sectors have the potential to exceed that threshold.

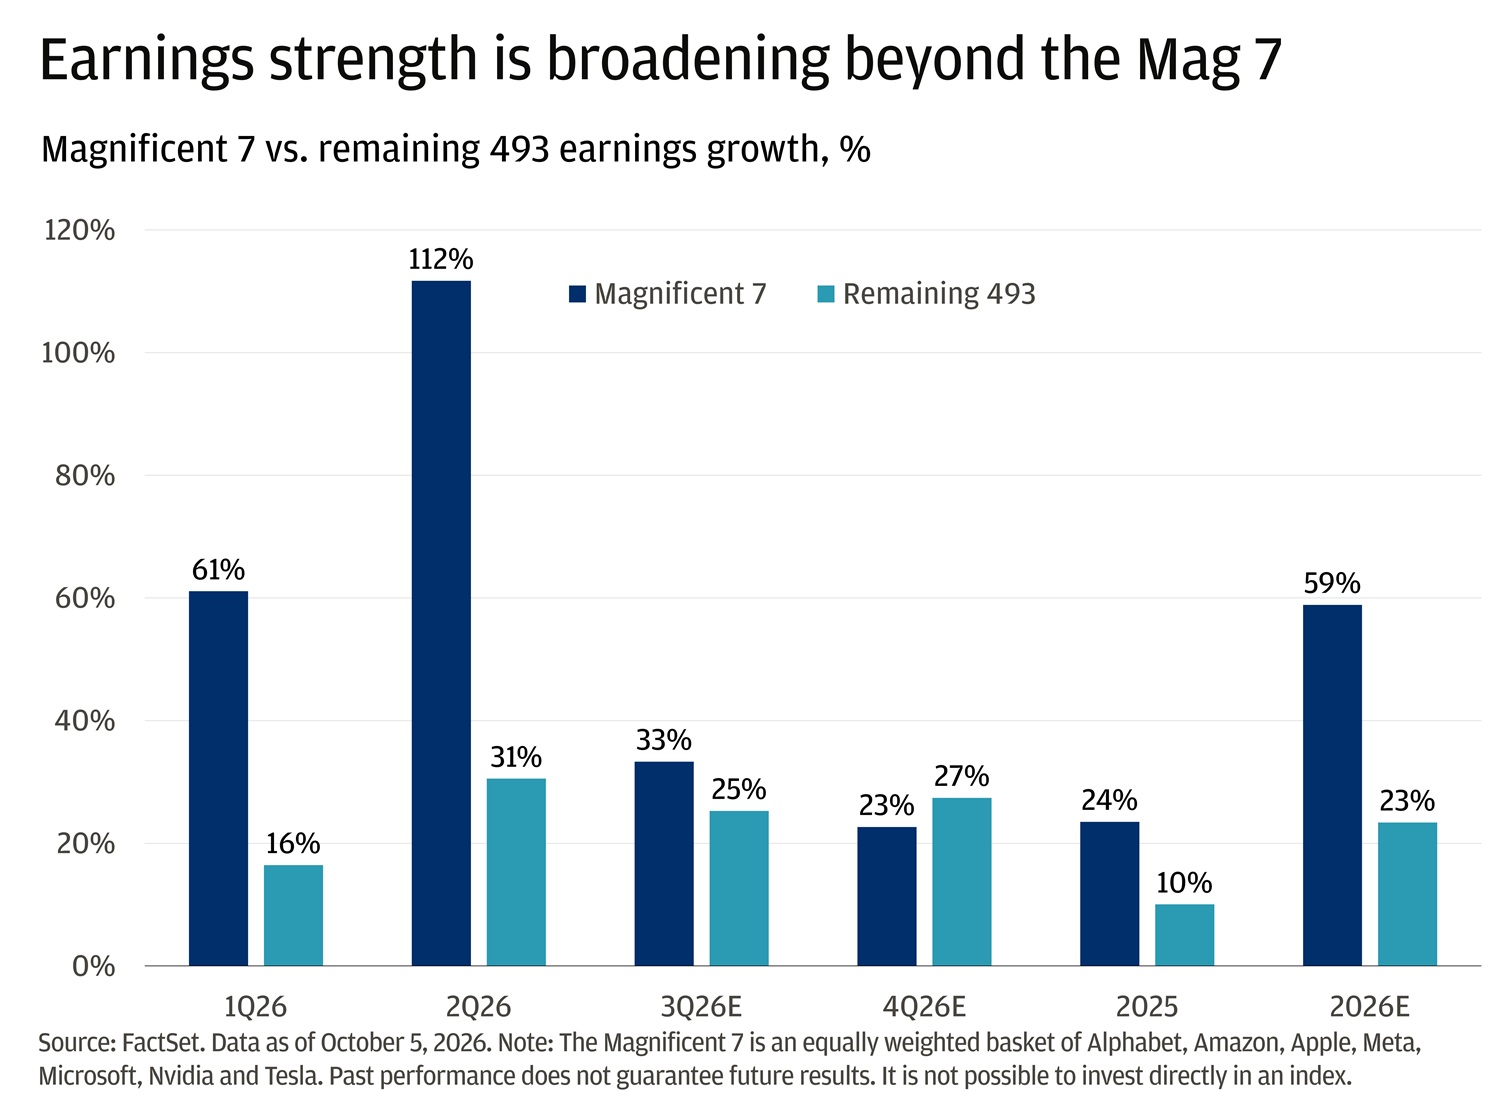
This is especially important as the Magnificent 7 have underperformed the broader market, rising roughly 12% this year compared to the S&P 500’s roughly 15% gain.1 And yet, earnings for the Magnificent 7 are expected to rise approximately 59% this year, while growth for the remaining 493 companies in the index is expected to be about 23%.

That’s still a sizable gap, but the fact that earnings growth is expanding beyond a handful of companies that have dominated index returns and into a broader set of sectors and industries is healthy.


The bar chart compares earnings growth for the “Magnificent 7” versus the remaining 493 companies across several periods.

Estimates and early reporters

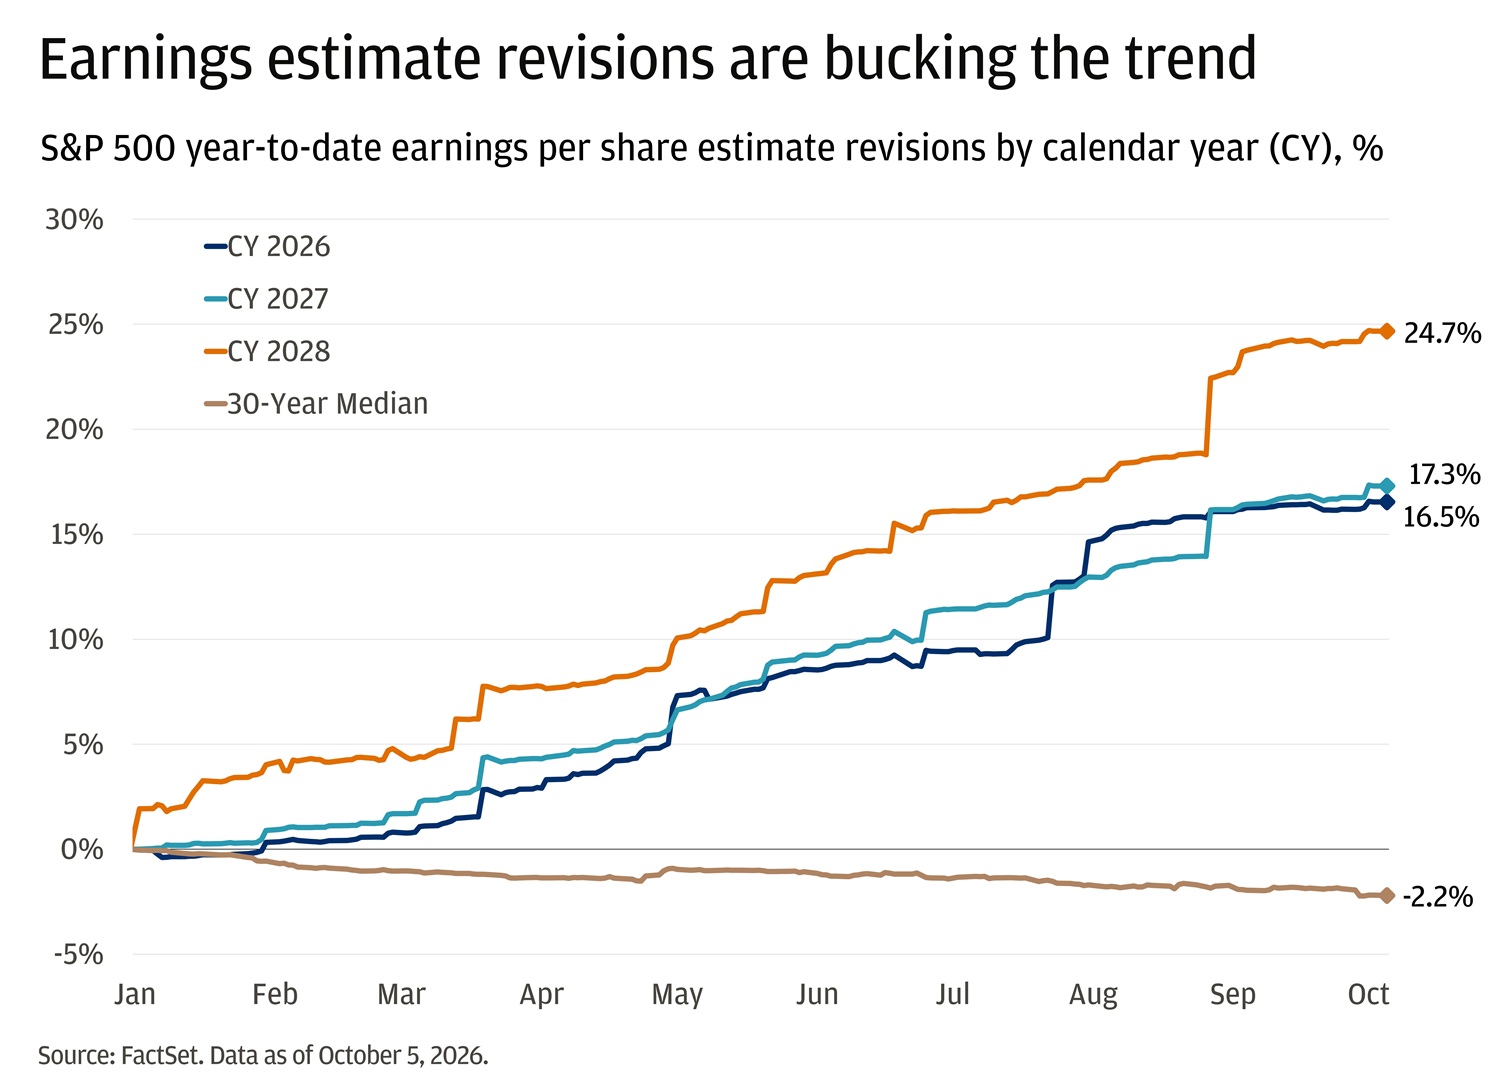
What's perhaps most notable is what’s happened to analyst estimates. The year traditionally begins with optimistic profit forecasts that tend to gradually drift lower as the year progresses. This year has shown the opposite. Earnings expectations have been revised materially higher, not lower, as companies continue to exceed forecasts by significantly wider-than-expected margins.

The line chart shows S&P 500 year-to-date earnings per share revisions by calendar year.


Early earnings results are reinforcing that narrative, with the vast majority already beating estimates. As a leading indicator of what to expect throughout the rest of third-quarter earnings season, it offers an encouraging signal for the broader reporting season ahead.

The third-quarter corporate earnings season will determine whether companies can once again clear a high bar. Expectations have risen, estimates have moved higher and investors are paying close attention to guidance for the remainder of the year. Can the blockbuster gains continue? If the early signals are any indication, the story that has defined the stock market in 2026 will likely remain intact: Corporate America continues to deliver earnings growth that is stronger, broader and more resilient than expected.

All market and economic data as of 10/08/2026 are sourced from Bloomberg Finance L.P. and FactSet unless otherwise stated.

References

1.

The Magnificent 7 is an equally weighted basket of Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla.

Connect with a Wealth Advisor

Reach out to your Wealth Advisor to discuss any considerations for your current portfolio. If you don’t have a Wealth Advisor, click here to tell us about your needs and we’ll reach out to you.

Connect now


Important Information

Index definitions:

The S&P 500 Index is an unmanaged broad-based index that is used as representation of the U.S. stock market. It includes 500 widely held common stocks. Total return figures reflect the reinvestment of dividends. “S&P500” is a trademark of Standard and Poor’s Corporation.

We believe the information contained in this material to be reliable but do not warrant its accuracy or completeness. Opinions, estimates, and investment strategies and views expressed in this document constitute our judgment based on current market conditions and are subject to change without notice.

The views, opinions, estimates and strategies expressed herein constitutes the author's judgment based on current market conditions and are subject to change without notice, and may differ from those expressed by other areas of J.P. Morgan. This information in no way constitutes J.P. Morgan Research and should not be treated as such. You should carefully consider your needs and objectives before making any decisions. For additional guidance on how this information should be applied to your situation, you should consult your advisor.

Any companies referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by J.P. Morgan in this context.

JPMorgan Chase & Co., its affiliates, and employees do not provide tax, legal or accounting advice. Information presented on these webpages is not intended to provide, and should not be relied on for tax, legal and accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transaction.

RISK CONSIDERATIONS 

  • Past performance is no guarantee of future results. It is not possible to invest directly in an index.
  • The price of equity securities may rise or fall due to the changes in the broad market or changes in a company's financial condition, sometimes rapidly or unpredictably. Share values can rise with strong earnings or positive market expectations, but they can also fall due to weak earnings or negative sentiment, and dividends are not guaranteed.
  • Investing in fixed income products (such as bonds) is subject to certain risks, including, but not limited to, interest rate, credit, inflation, call, default, prepayment and reinvestment risk. Any fixed income security sold or redeemed prior to maturity may be subject to substantial gain or loss.
  • Investors should carefully read the prospectus or other offering documents which include information on the investment objectives, risks, charges and expenses along with other information about the fund before investing.
  • Investors should understand the potential tax liabilities surrounding a municipal bond purchase. Certain municipal bonds are federally taxed if the holder is subject to alternative minimum tax. Capital gains, if any, are federally taxable. The investor should note that the income from tax-free municipal bond funds may be subject to state and local taxation and the alternative minimum tax (AMT).
  • International investments may not be suitable for all investors. International investing involves a greater degree of risk and increased volatility. Some international markets may not be politically or economically stable. Foreign holdings are subject to currency risk, as fluctuations in exchange rates between the investment’s foreign currency and the holder’s domestic currency can affect the value of the investment.           
  • Investing in emerging markets involves a greater degree of risk and increased volatility compared to developed markets. Changes in currency exchange rates and differences in accounting and taxation policies outside the investor’s jurisdiction can raise or lower returns. Some markets may not be as politically and economically stable, in addition to differences in taxation policies, and legal systems outside the investor’s jurisdiction may create additional risks. Investors should carefully consider these risks and consult with financial and legal advisors before investing in emerging markets.
  • Investments in commodities may have greater volatility than investments in traditional securities, particularly if the instruments involve leverage. The value of commodity-linked derivative instruments may be affected by changes in overall market movements, commodity index volatility, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. Use of leveraged commodity-linked derivatives creates an opportunity for increased return but, at the same time, creates the possibility for greater loss.     
  • Real Estate Investment Trusts (REITs) are subject to risks such as fluctuations in property values and changes in economic conditions. Additionally, REITs may face risks from interest rate changes, regulatory shifts, and limited diversification if concentrated in specific sectors or geographic areas.
  • Investing in alternative assets involves higher risks than traditional investments, including, without limitation, limited liquidity and valuation risk, and is suitable only for investors with sufficient knowledge and sophistication to evaluate the merits and risks of such investments. Alternative investments should not be deemed a complete investment program and distributions are not guaranteed. They may not be tax efficient, and an investor should consult with their tax professional prior to investing. Alternative investments often have higher fees than traditional investments and they may also be highly leveraged and engage in speculative investment techniques, which can magnify the investment loss or gain--including risk of loss of the entire investment. For comprehensive details around unique set of risks for specific alternative investments, please consult the offering memorandum.
  • Structured product involves derivatives and intended for experienced and sophisticated investors who are willing to bear the high economic risks of the investment. The most common risks include, but are not limited to, risk of adverse or unanticipated market developments, issuer credit quality risk, risk of lack of uniform standard pricing, risk of adverse events involving any underlying reference obligations, risk of high volatility, risk of illiquidity/little to no secondary market, and conflicts of interest. Any payments on a structured product are subject to the credit risk of the issuer and/or guarantor. Investors may lose their entire investment, i.e., incur an unlimited loss. Before investing in a structured product, investors should review the accompanying offering document, prospectus or prospectus supplement to understand the actual terms and key risks associated with each individual structured product. For a more comprehensive list of the risks involved with a particular product, please refer to the relevant risk disclosure booklet or speak to your J.P. Morgan team.  If you are in any doubt about the risks involved in the product, you may clarify with the intermediary or seek independent professional advice.
  • Private investment funds (including, without limitation, hedge funds, funds of hedge funds, private equity funds, real estate funds, etc.) are subject to special risks, including risk of loss of the entire investment and is suitable only for investors with sufficient knowledge and sophistication to evaluate the merits and risks of such investments. As a reminder, private investment funds often engage in leveraging and other speculative investment practices that may increase the risk of investment loss. These investments can be highly illiquid, and may not be required to provide periodic pricing or valuation information to investors, and may involve complex tax structures and delays in distributing important tax information. Distributions are not guaranteed and may be modified at the Fund Board’s discretion. These investments are not subject to the same regulatory requirements as mutual funds; and often charge high fees (performance fees in addition to management fees). Further, any number of conflicts of interest may exist in the context of the management and/or operation of any such fund. For comprehensive details around unique set of risks for specific alternative investments, please refer to the applicable offering memorandum.
  • Investments in digital assets and cryptocurrencies, or other investment vehicles holding or referencing digital assets, are highly speculative and involve significant risks, including, but not limited to, increased volatility, ongoing regulatory uncertainty including lack of clear precedent in various jurisdictions surrounding digital assets, cybersecurity risk relating to digital asset holdings, and increased sensitivity to news, speculation and manipulation. Likewise, various digital assets may differ from one another in their technological characteristics, regulatory treatment, market convention and performance. There is limited data on the performance of digital assets and products referencing digital assets (although in no case should historical performance be taken as an indication of future performance). You should consider these unique characteristics and whether these assets are suitable for you when making an investment decision.
  • The prices and rates of return are indicative, as they may vary over time based on market conditions.
  • Additional risk considerations exist for all strategies.
  • The information provided herein is not intended as a recommendation of or an offer or solicitation to purchase or sell any investment product or service.
  • Opinions expressed herein may differ from the opinions expressed by other areas of J.P. Morgan. This material should not be regarded as investment research or a J.P. Morgan investment research report.


GENERAL RISKS & CONSIDERATIONS
. 
Any views, strategies or products discussed in this material may not be appropriate for all individuals and are subject to risks. Investors may get back less than they invested, and past performance is not a reliable indicator of future results. Asset allocation/diversification does not guarantee a profit or protect against loss. Nothing in this material should be relied upon in isolation for the purpose of making an investment decision. You are urged to consider carefully whether the services, products, asset classes (e.g. equities, fixed income, alternative investments, commodities, etc.) or strategies discussed are suitable to your needs. You must also consider the objectives, risks, charges, and expenses associated with an investment service, product or strategy prior to making an investment decision. For this and more complete information, including discussion of your goals/situation, contact your J.P. Morgan representative.

NON-RELIANCE. Certain information contained in this material is believed to be reliable; however, JPM does not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which are provided for illustration/reference purposes only. The views, opinions, estimates and strategies expressed in this material constitute our judgment based on current market conditions and are subject to change without notice. JPM assumes no duty to update any information in this material in the event that such information changes. Views, opinions, estimates and strategies expressed herein may differ from those expressed by other areas of JPM, views expressed for other purposes or in other contexts, and this material should not be regarded as a research report. Any projected results and risks are based solely on hypothetical examples cited, and actual results and risks will vary depending on specific circumstances. Forward-looking statements should not be considered as guarantees or predictions of future events.

Nothing in this document shall be construed as giving rise to any duty of care owed to, or advisory relationship with, you or any third party. Nothing in this document shall be regarded as an offer, solicitation, recommendation or advice (whether financial, accounting, legal, tax or other) given by J.P. Morgan and/or its officers or employees, irrespective of whether or not such communication was given at your request. J.P. Morgan and its affiliates and employees do not provide tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transactions.

Legal Entity and Regulatory Information.

J.P. Morgan Wealth Management is a business of JPMorgan Chase & Co., which offers investment products and services through J.P. Morgan Securities LLC (JPMS), a registered broker-dealer and investment adviser, member FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. Certain custody and other services are provided by JPMorgan Chase Bank, N.A. (JPMCB). JPMS, CIA and JPMCB are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.

Bank deposit accounts and related services, such as checking, savings and bank lending, are offered by JPMorgan Chase Bank, N.A. Member FDIC.

This document may provide information about the brokerage and investment advisory services provided by J.P. Morgan Securities LLC (“JPMS”). The agreements entered into with JPMS, and corresponding disclosures provided with respect to the different products and services provided by JPMS (including our Form ADV disclosure brochure, if and when applicable), contain important information about the capacity in which we will be acting. You should read them all carefully. We encourage clients to speak to their JPMS representative regarding the nature of the products and services and to ask any questions they may have about the difference between brokerage and investment advisory services, including the obligation to disclose conflicts of interests and to act in the best interests of our clients.

J.P. Morgan may hold a position for itself or our other clients which may not be consistent with the information, opinions, estimates, investment strategies or views expressed in this document. JPMorgan Chase & Co. or its affiliates may hold a position or act as market maker in the financial instruments of any issuer discussed herein or act as an underwriter, placement agent, advisor or lender to such issuer.