Key takeaways
- Total consumer spending increased by 6.8% in September, even as inflation and living costs climbed.
- Consumers are increasingly dipping into their savings to sustain their spending despite anemic income growth.
- Some are also relying on credit to cover costs, as seen in the growth in payday loans, short-term installment loans and Buy Now, Pay Later (BNPL) usage.
Consumer spending in the U.S. remains remarkably resilient despite renewed inflation concerns and soaring living costs — a paradox that continues to sustain the American economy. The Personal Consumption Expenditures (PCE) price index, which tracks inflation, rose 3.6% year over year in September, up from 3.4% in August. Yet Chase card data shows that total consumer spending increased by 6.8% in September, up from August’s 5.3%.1
Beneath the surface, though, financial strain is building: purchasing power is squeezed and income gains aren’t keeping pace. How much more pressure can the U.S. consumer withstand?
Why are prices rising?
The ongoing Middle East conflict has disrupted crude oil supplies, sending energy prices sharply higher — and this has in turn cascaded across the economy by driving up production, transport and operating expenses.
Diesel prices recently reached all-time highs, while gas prices continue to hover above $4 per gallon. “We estimate that average gas prices were up around 40.4% through October 21 versus the same period in 2025. Given the regressive impact of spending at the pump, we see a headwind for lower- and middle-income consumers,” said Richard Shane, head of Consumer and Specialty Finance at J.P. Morgan.
In the same vein, grocery prices have increased. According to the Bureau of Labor Statistics, U.S. food prices increased 2.5% year over year in September 2026, with coffee up 7.1%, fish and seafood up 6.9% and fresh fruit and vegetables up 3.7%.
Additionally, broad import tariffs have increased the cost of incoming goods. Recent research from the Federal Reserve notes that for every 1 percentage point increase in tariffs, consumer prices increase by about 0.25% after one year.
“Despite anemic income growth, real consumption growth has generally held up. The only way to make this math work is through a reduction in the personal saving rate.”
Abiel Reinhart
Economist, J.P. Morgan
What’s sustaining consumer spending?
With higher prices eroding paychecks, consumers are increasingly drawing down savings to support their spending. “Real personal disposable income has only grown 1% annualized year to date. Despite this anemic income growth, real consumption growth has generally held up, growing above 2% and probably closer to 3.5% in the middle half of the year. The only way to make this math work is through a reduction in the personal saving rate,” observed Abiel Reinhart, an economist at J.P. Morgan.
Indeed, data from the Bureau of Economic Analysis show the U.S. personal saving rate fell to 3.8% in September, down from 4.0% in August — the lowest level in nearly four years and well below the pre-pandemic five-year average of roughly 6.2%. “Our forecast looks for a further decline of 0.6 percentage points over the second half of 2026,” said Joseph Lupton, co-head of Economic Research at J.P. Morgan.
The fall in savings coincides with a surge in household wealth, driven in part by strong equity market performance. Looking at household balance sheets, net worth jumped $13 trillion in the second quarter of 2026 alone and is up $21 trillion over the last four quarters.
This behavioral dynamic reflects the “wealth effect” — an economic phenomenon whereby consumers increase their spending when the value of their assets goes up, even if their regular income doesn’t change. “We estimate that the increase in wealth over the last year has the potential to lower the saving rate by about 0.5 to 2.0 percentage points,” Reinhart added.
Optimism is also evident in the “expected income effect,” which is further fueling spending. “Part of the fall in saving rates also owes to the willingness of households to smooth through the current weakness in income growth in anticipation of a recovery in jobs and fading inflation,” Lupton explained. However, J.P. Morgan Global Research expects core PCE inflation to remain elevated in the near term, exceeding 2.5% on a Q4/Q4 basis in 2027; on the other hand, the unemployment rate is forecast to fall to 4.0% next year, down slightly from the current rate of 4.2%.
Disposable income and savings have fallen
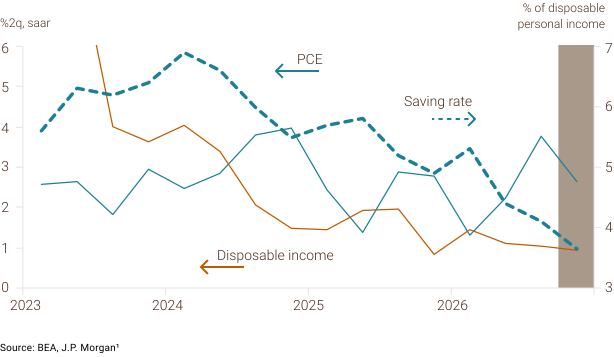
U.S. consumers have less disposable income and savings, while PCE remains elevated.
Are consumers borrowing more?
As their savings cushion wears thin, some consumers are turning to credit to cover everyday costs. According to J.P. Morgan Global Research, credit card loan growth in the U.S. was up 6.1% year over year in the second quarter of 2026, versus 4.9% in the first quarter. “Similarly, there has been very sharp growth in payday loans, short-term installment loans and Buy Now, Pay Later (BNPL) usage — all indicative of consumers getting stretched,” said Vivek Juneja, a senior analyst covering Large-Cap U.S. Banks at J.P. Morgan. “In particular, BNPL is being used for a wide array of use cases including groceries, restaurants and clothing, with about half of users saying they would not be able to make ends meet without the loan.”
Some consumers are feeling the pinch more than others. Data from the Federal Reserve Bank of New York shows that serious credit card delinquencies (90+ days past due) have surged among the 70+ age cohort and have also increased somewhat among 18–29s. However, they are down among the 30–39, 40–49 and 60–69 age cohorts. This divergence suggests that the U.S. economy remains K-shaped, with older and younger borrowers facing greater affordability and debt pressures than those in their prime working years.
“There has been very sharp growth in payday loans, short-term installment loans and Buy Now, Pay Later (BNPL) usage — all indicative of consumers getting stretched.”
Vivek Juneja
Senior analyst covering Large-Cap U.S. Banks, J.P. Morgan
The bottom line
Overall, rising prices, tepid income growth and a dwindling savings cushion are stretching consumers, many of whom are relying on wealth gains and credit usage to fund their spending — a pattern that is unsustainable over the long term. As such, J.P. Morgan Global Research anticipates a spending slowdown in the coming months as consumers have little choice but to rein in their outlays. “With the benefits of wealth fading and a new purchasing power squeeze building, we look for spending gains to cool to an annualized rate of 1.5% this quarter,” said Michael Feroli, chief U.S. economist at J.P. Morgan.
References
JPMorgan Chase Bank, NA, JPMC Index File 2.0, select Chase credit and debit card transaction data. See https://www.jpmm.com/research/content/publication/9002054 for disclaimers and methodology.
Related insights
-
Global Research
US tariffs: What’s the impact on global trade and the economy?
September 09, 2026
J.P. Morgan Global Research brings you the latest updates and analysis of President Trump’s tariff proposals and their economic impact.
-
Global Research
Chronic supply-demand imbalances, elevated mortgage rates and rising ownership costs are straining housing affordability across many markets — a global problem that demands localized solutions.
-
Global Research
Global bond yields have repriced higher on hawkish “higher-for-longer” policy expectations, elevated energy prices and geopolitical uncertainty, reshaping markets into year-end.
This material (Material) is provided for your information only and does not constitute: (i) an offer to sell, a solicitation of an offer to buy, or a recommendation for any investment product or strategy, or (ii) any investment, legal or tax advice. The information contained herein is as of the date and time referenced in the Material and J.P. Morgan does not undertake any obligation to update such information. J.P. Morgan disclaims any responsibility or liability, whether in contract, tort (including, without limitation, negligence), equity or otherwise, for the quality, accuracy or completeness of the information contained in this Material, and for any reliance on, or uses to which, this Material, is put, and you are solely responsible for any use to which you put such information. Without limiting any of the foregoing, to the fullest extent permitted by applicable law, in no event shall J.P. Morgan have any liability for any special, punitive, indirect, or consequential damages (including lost profits or lost opportunity), in connection with the information contained in this Material, even if notified of the possibility of such damages. Any comments or statements made herein do not necessarily reflect those of J.P. Morgan, its subsidiaries or its affiliates.
All materials and information shared with you are, unless otherwise indicated to you, proprietary and confidential to J.P. Morgan. You are hereby notified that any disclosure, dissemination, copying, distribution, or use of the information provided to you, in whole or in part, other than as expressly permitted by J.P. Morgan, is STRICTLY PROHIBITED. You are permitted to disclose the materials and information to your officers and employees on a need to know basis. Should you have any questions regarding this, please contact your usual J.P. Morgan contact. For further information please visit: https://www.jpmorgan.com/pages/disclosures/materialdisclaimer.
© 2025 JPMorgan Chase & Co. All rights reserved. J.P. Morgan is a marketing name for businesses of JPMorgan Chase & Co. and its subsidiaries and affiliates worldwide. JPMorgan Chase Bank N.A. (member of FDIC), J.P. Morgan Securities LLC (member of FINRA, NYSE and SIPC), J.P. Morgan Securities plc (member of the London Stock Exchange and authorized by the Prudential Regulation Authority (PRA) and regulated by the Financial Conduct Authority and the PRA) and J.P. Morgan SE (authorised by the BaFin and regulated by the BaFin, the German Central Bank and the European Central Bank) are principal subsidiaries of JPMorgan Chase & Co. For legal entity and regulatory disclosures, visit: www.jpmorgan.com/disclosures. For additional regulatory disclosures, please consult: www.jpmorgan.com/disclosures.