Version 1 - Primary Nav Search

Contributors

Justin Biemann

Global Investment Strategist


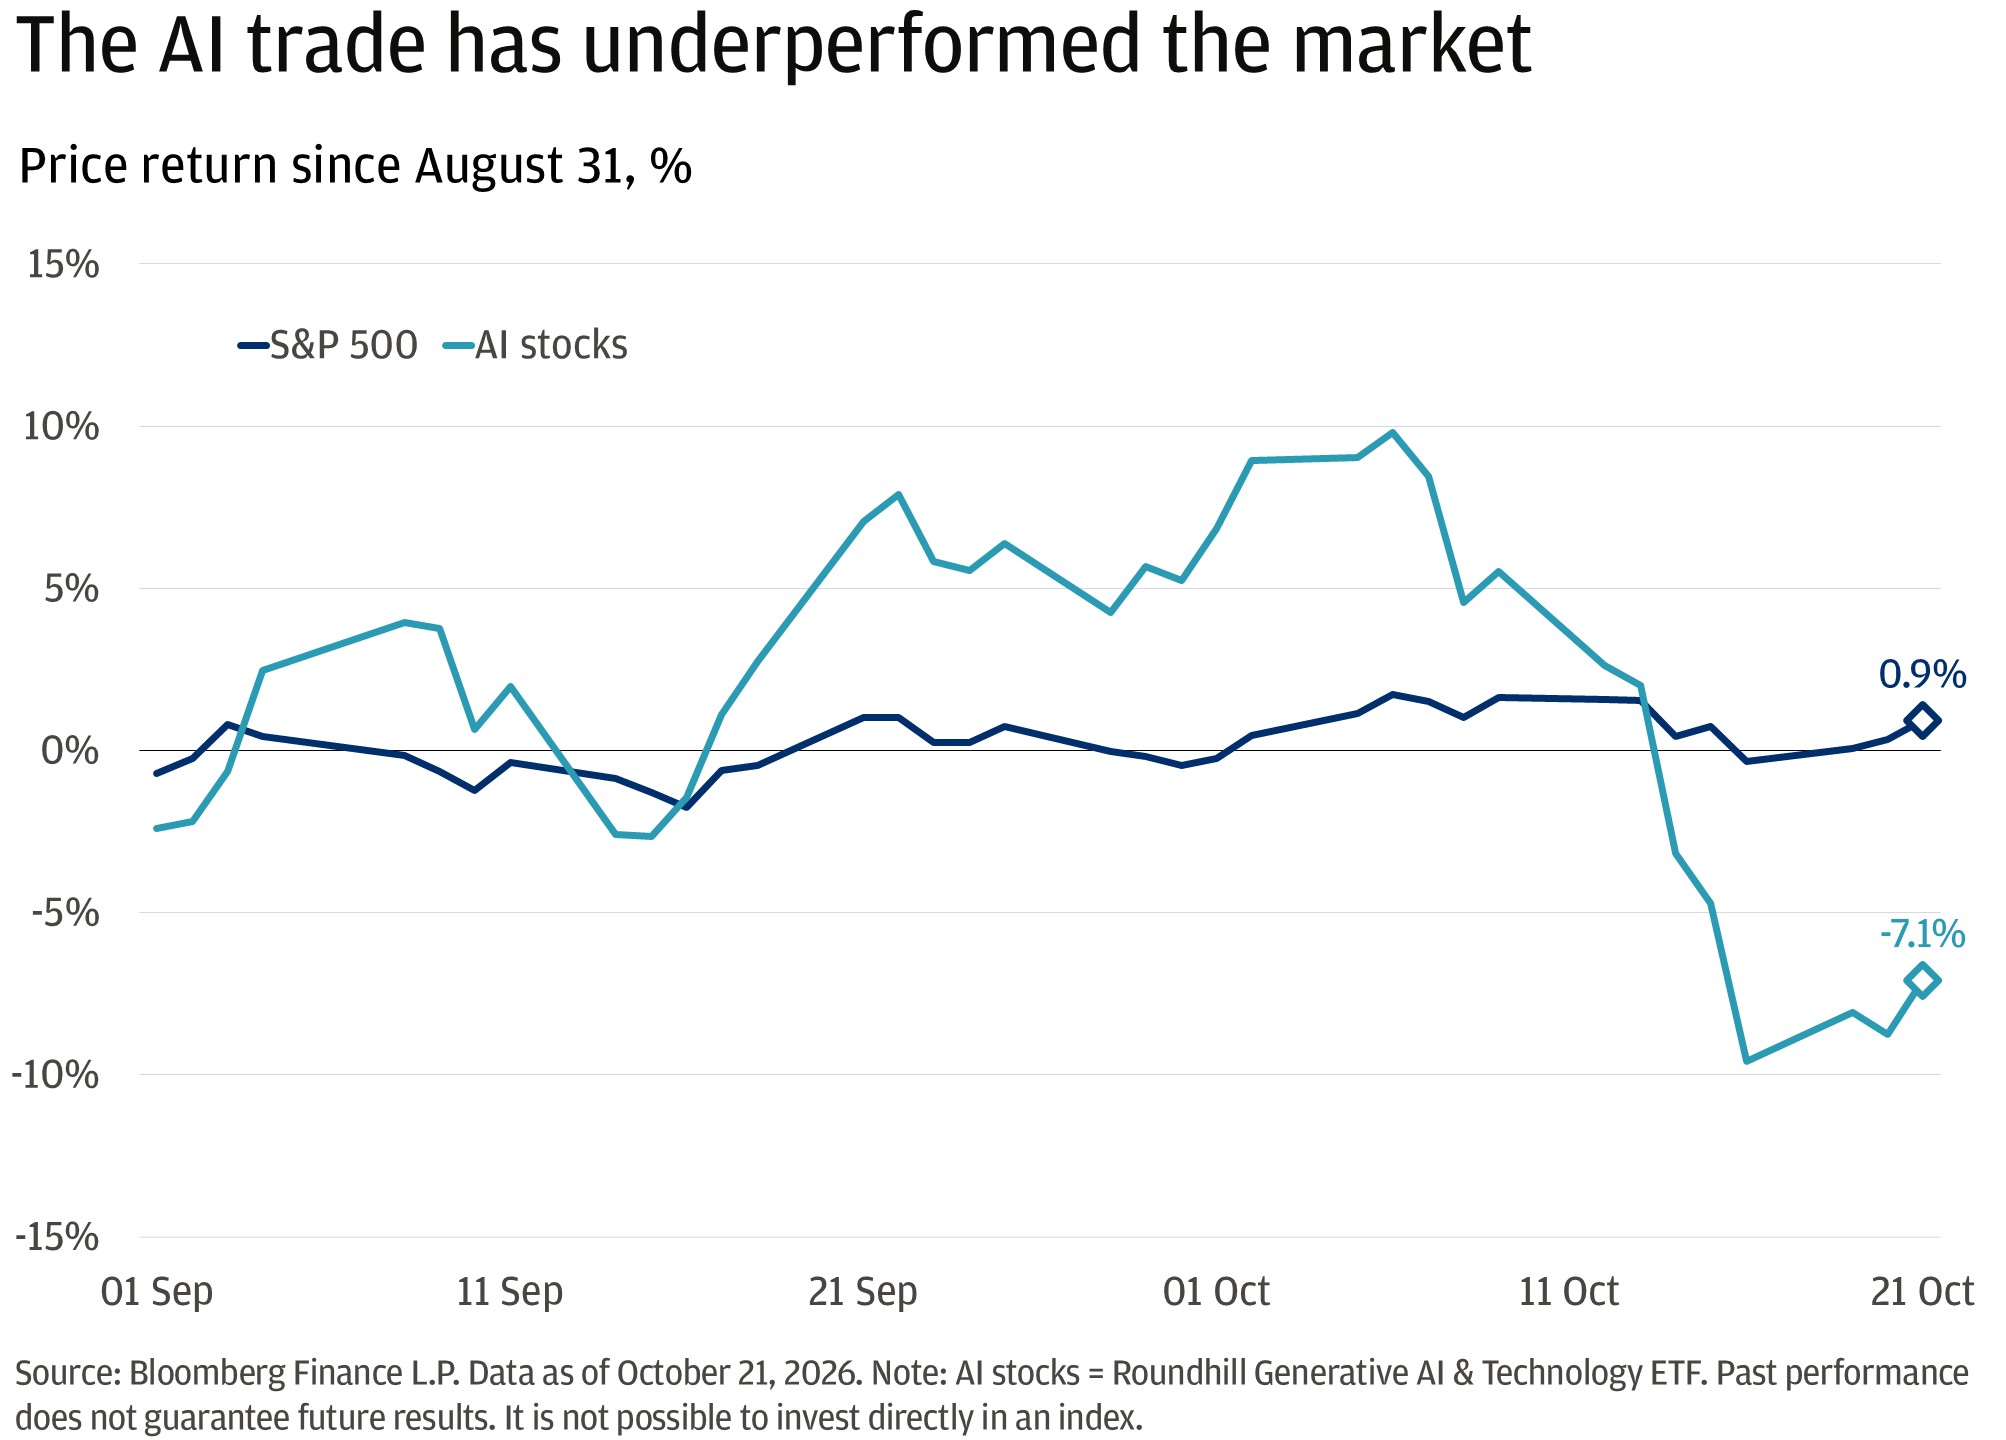
The artificial intelligence (AI) trade has hit turbulence over the past few weeks. AI-related stocks have fallen much more sharply than the broader market as investors reconsider the financing costs of building data centers, buying chips and supplying the electricity needed to run them.

Still, investors have seen rotations out of AI before. What makes this episode different is the simultaneous action in credit markets. The cost of insuring the debt of several AI-linked companies has reached record levels as the sector grows more reliant on debt financing.

This line chart shows the price return since August 31st for the S&P 500 and for AI stocks (represented by the Roundhill Generative AI & Technology ETF).


But rather than a blanket vote against the ecosystem, the rising cost of default protection reflects a targeted reassessment of repayment risk. In other words, credit markets are taking a hard look at the AI buildout and asking who can afford to keep at it.

What does default insurance tell investors?

Credit default swaps (CDS) act like insurance on a company’s debt. CDS buyers pay a recurring premium and, if the borrower experiences a major credit event, such as bankruptcy or failure to pay, the buyer will receive a large payout.

The premium is quoted in basis points. A CDS spread of 100 basis points broadly means that insuring $10 million of debt costs $100,000 per year. At 1,000 basis points, the annual cost rises to roughly $1 million. 1

Credit default swaps can provide a measure of market sentiment. A wider CDS spread does not necessarily signal an expected failure. It can also reflect greater hedging demand, heavy debt issuance or uncertainty about future financing. The level, speed and confirmation from other markets help distinguish routine insurance from genuine distress.

One trade, several credit stories

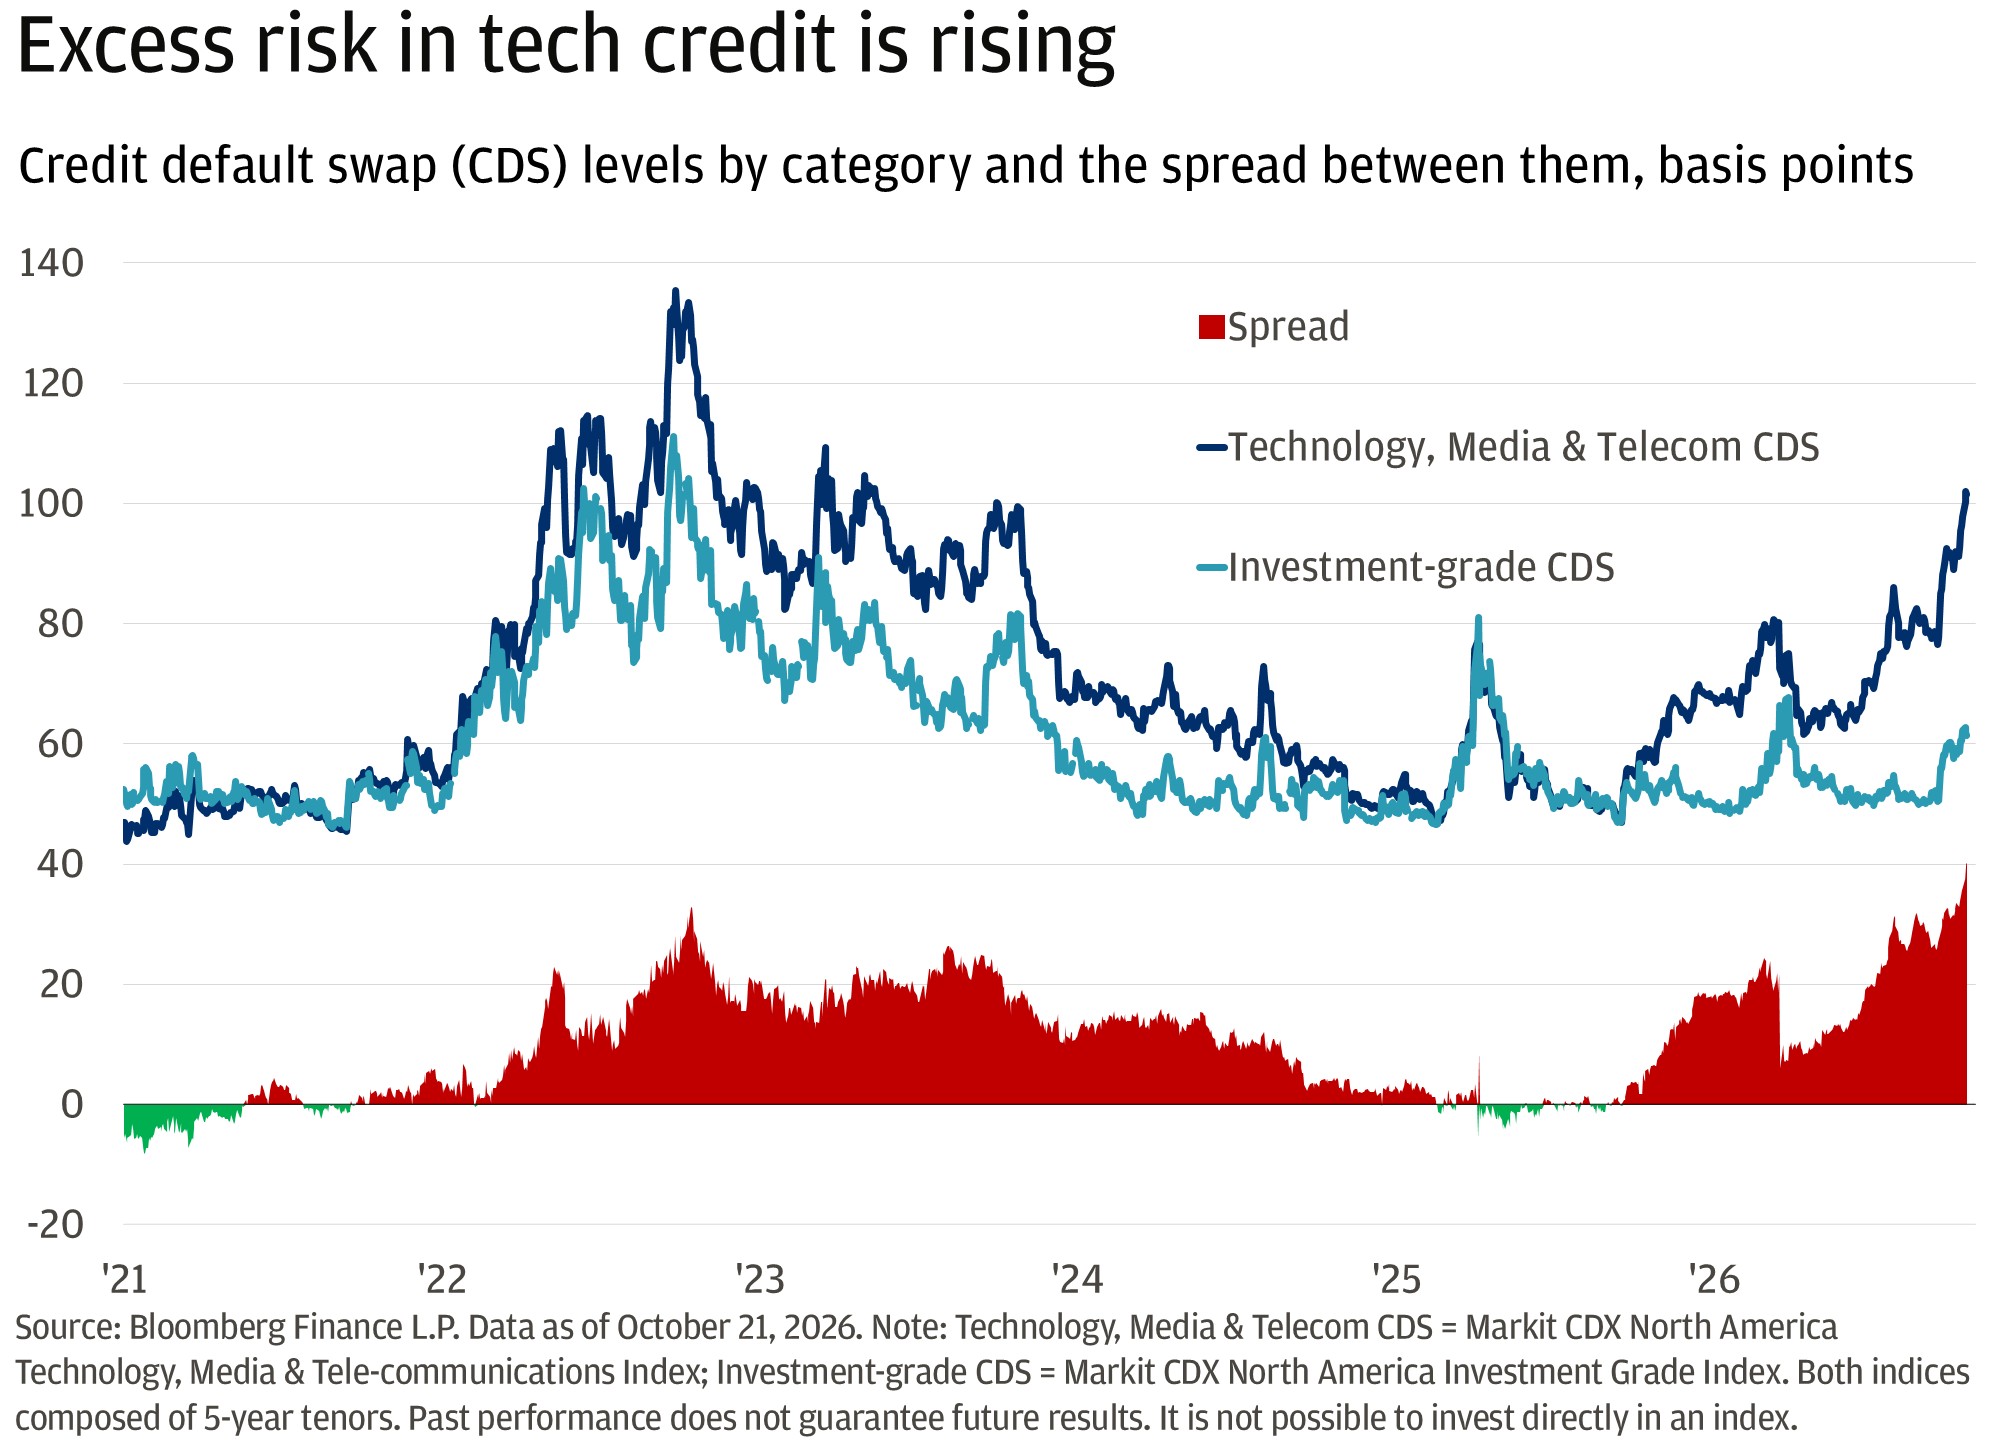
Credit spreads have widened over the past month, but technology-related borrowers have moved much more sharply than the broader investment-grade market. The spread between the two has spiked higher than even during the tech-driven downturn of 2022.

This line chart shows Technology, Media & Telecom credit default swap (CDS) levels, broad investment-grade CDS levels, and the spread between the two (tech minus investment grade).


Going one level deeper, AI-related CDS have risen even more rapidly in the past month, but not all in parallel. For large, cash-generative AI leaders, five-year CDS spreads range from 50 to 120 basis points. These are elevated levels for companies with strong balance sheets, but they still look more like the price of portfolio insurance than a prediction of financial distress. These companies still have far lower leverage and higher interest coverage ratios than the average investment-grade borrower.  

The picture changes as debt becomes more important to the business model. Default protection on some established investment-grade infrastructure borrowers has climbed toward 300 basis points. That represents a meaningful reassessment of credit risk.

At the weak end of the spectrum, one financing-dependent AI infrastructure borrower has taken on tens of billions of dollars in debt and other obligations. Its five-year CDS shot up to 1,100 basis points this week, so insuring $10 million of its debt would cost more than $1 million per year. Pricing at these levels implies near or above a 50% probability of default over five years, up from below 30% a year ago. That is not a forecast, but it is difficult to dismiss.2

Put together, investors are demanding roughly 10 times as much to insure the weakest AI borrowers as the strongest companies in the ecosystem. Yet broad investment-grade protection remains comparatively contained. If markets were losing confidence in corporate balance sheets generally, that would not be the case. The concern is confined to business models that require debt markets to remain open while spending stays high and cash flow remains limited.

Credit can be an early signal

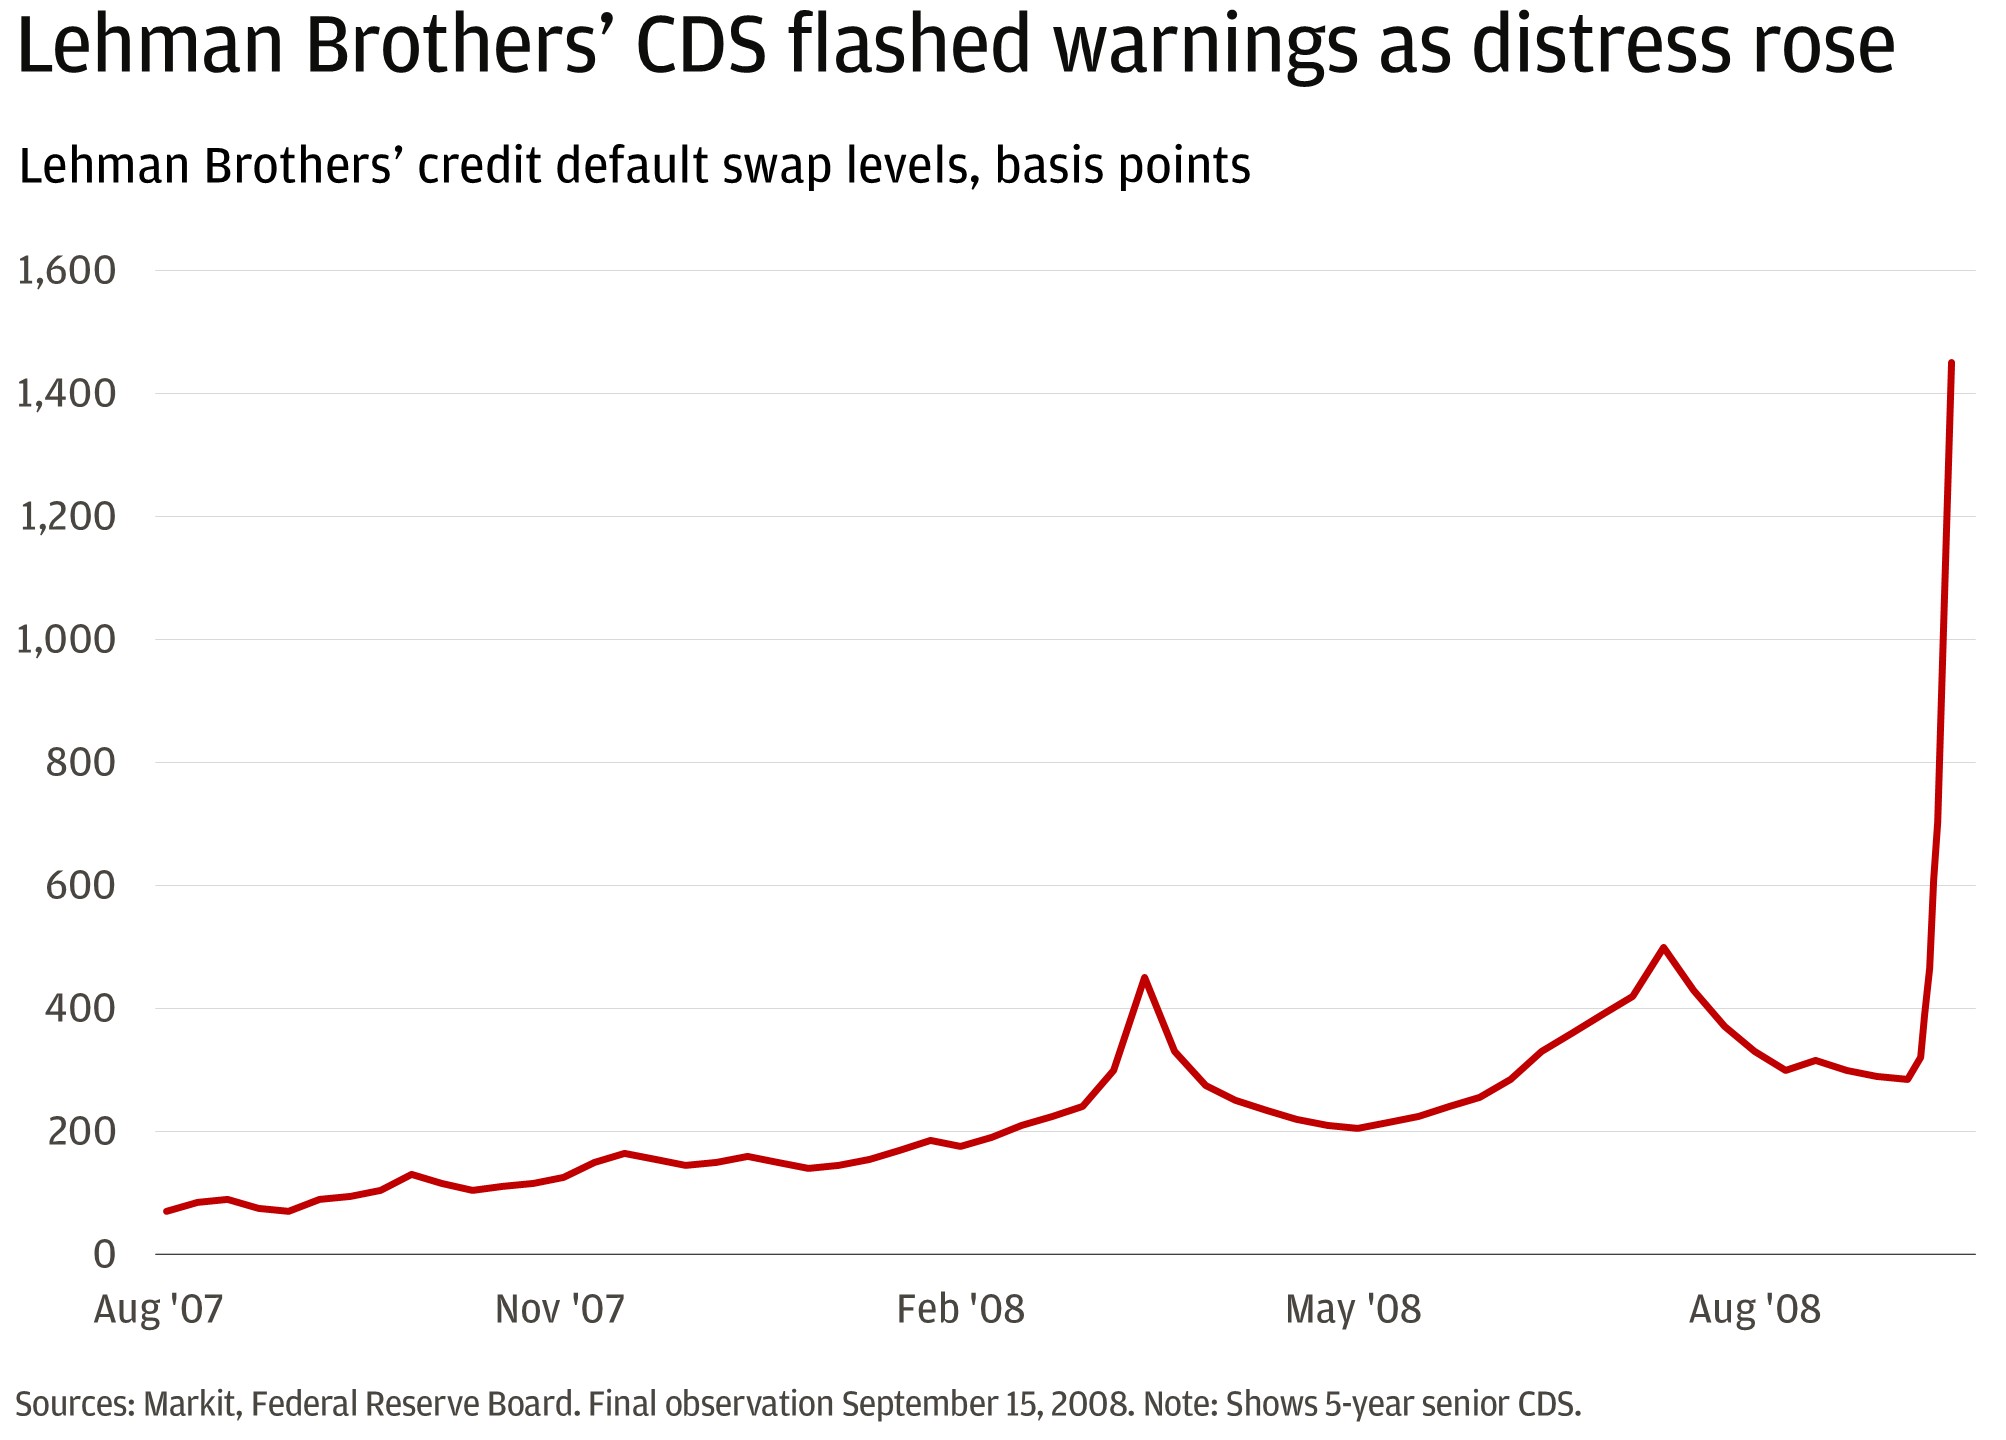
Lehman Brothers’ CDS averaged less than 100 basis points in the third quarter of 2007. By mid-September 2008, they had risen to over 1,400 basis points and the firm had filed for bankruptcy.

This line chart shows Lehman Brothers’ CDS levels in basis points over time.


CDS did not predict the exact moment when Lehman would run out of options. But the steady rise in protection costs, reinforced by falling bond and equity prices and mounting funding pressure, clearly showed that the market was losing confidence in the firm’s ability to pay its debts.

Not every warning ends the same way. In 2005, default protection on a major U.S. automaker rose sharply ahead of its downgrade to high yield. The company’s financial pressure was real, but it raised liquidity, restructured and avoided bankruptcy.

That is how investors can view CDS today – as warning lights rather than countdown clocks.

What does this mean for the AI trade?

As long as broad investment-grade spreads remain contained and stronger borrowers retain access to capital, stress among the riskiest issuers is unlikely to derail the broader AI buildout.

However, the AI label alone is no longer enough to reassure lenders. Companies must show that they can finance investment, service their debt and eventually turn spending into cash flow. Credit markets are scrutinizing the AI buildout and deciding who is financially equipped to finish it.

All market and economic data as of 10/22/2026 are sourced from Bloomberg Finance L.P. and FactSet unless otherwise stated.

References

1.

Contracts for distressed borrowers may also require an upfront payment.

2.

Annual insurance cost is approximated by multiplying the CDS spread by the protected notional amount. Implied default probabilities use a standard CDS model and assumed recovery rate; they include liquidity and risk premiums and should not be interpreted as forecasts.

Connect with a Wealth Advisor

Reach out to your Wealth Advisor to discuss any considerations for your current portfolio. If you don’t have a Wealth Advisor, click here to tell us about your needs and we’ll reach out to you.

Connect now


Important Information

Index definitions:

The S&P 500 Index is an unmanaged broad-based index that is used as representation of the U.S. stock market. It includes 500 widely held common stocks. Total return figures reflect the reinvestment of dividends. “S&P500” is a trademark of Standard and Poor’s Corporation.

We believe the information contained in this material to be reliable but do not warrant its accuracy or completeness. Opinions, estimates, and investment strategies and views expressed in this document constitute our judgment based on current market conditions and are subject to change without notice.

The views, opinions, estimates and strategies expressed herein constitutes the author's judgment based on current market conditions and are subject to change without notice, and may differ from those expressed by other areas of J.P. Morgan. This information in no way constitutes J.P. Morgan Research and should not be treated as such. You should carefully consider your needs and objectives before making any decisions. For additional guidance on how this information should be applied to your situation, you should consult your advisor.

Any companies referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by J.P. Morgan in this context.

JPMorgan Chase & Co., its affiliates, and employees do not provide tax, legal or accounting advice. Information presented on these webpages is not intended to provide, and should not be relied on for tax, legal and accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transaction.

RISK CONSIDERATIONS 

  • Past performance is no guarantee of future results. It is not possible to invest directly in an index.
  • The price of equity securities may rise or fall due to the changes in the broad market or changes in a company's financial condition, sometimes rapidly or unpredictably. Share values can rise with strong earnings or positive market expectations, but they can also fall due to weak earnings or negative sentiment, and dividends are not guaranteed.
  • Investing in fixed income products (such as bonds) is subject to certain risks, including, but not limited to, interest rate, credit, inflation, call, default, prepayment and reinvestment risk. Any fixed income security sold or redeemed prior to maturity may be subject to substantial gain or loss.
  • Investors should carefully read the prospectus or other offering documents which include information on the investment objectives, risks, charges and expenses along with other information about the fund before investing.
  • Investors should understand the potential tax liabilities surrounding a municipal bond purchase. Certain municipal bonds are federally taxed if the holder is subject to alternative minimum tax. Capital gains, if any, are federally taxable. The investor should note that the income from tax-free municipal bond funds may be subject to state and local taxation and the alternative minimum tax (AMT).
  • International investments may not be suitable for all investors. International investing involves a greater degree of risk and increased volatility. Some international markets may not be politically or economically stable. Foreign holdings are subject to currency risk, as fluctuations in exchange rates between the investment’s foreign currency and the holder’s domestic currency can affect the value of the investment.           
  • Investing in emerging markets involves a greater degree of risk and increased volatility compared to developed markets. Changes in currency exchange rates and differences in accounting and taxation policies outside the investor’s jurisdiction can raise or lower returns. Some markets may not be as politically and economically stable, in addition to differences in taxation policies, and legal systems outside the investor’s jurisdiction may create additional risks. Investors should carefully consider these risks and consult with financial and legal advisors before investing in emerging markets.
  • Investments in commodities may have greater volatility than investments in traditional securities, particularly if the instruments involve leverage. The value of commodity-linked derivative instruments may be affected by changes in overall market movements, commodity index volatility, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. Use of leveraged commodity-linked derivatives creates an opportunity for increased return but, at the same time, creates the possibility for greater loss.     
  • Real Estate Investment Trusts (REITs) are subject to risks such as fluctuations in property values and changes in economic conditions. Additionally, REITs may face risks from interest rate changes, regulatory shifts, and limited diversification if concentrated in specific sectors or geographic areas.
  • Investing in alternative assets involves higher risks than traditional investments, including, without limitation, limited liquidity and valuation risk, and is suitable only for investors with sufficient knowledge and sophistication to evaluate the merits and risks of such investments. Alternative investments should not be deemed a complete investment program and distributions are not guaranteed. They may not be tax efficient, and an investor should consult with their tax professional prior to investing. Alternative investments often have higher fees than traditional investments and they may also be highly leveraged and engage in speculative investment techniques, which can magnify the investment loss or gain--including risk of loss of the entire investment. For comprehensive details around unique set of risks for specific alternative investments, please consult the offering memorandum.
  • Structured product involves derivatives and intended for experienced and sophisticated investors who are willing to bear the high economic risks of the investment. The most common risks include, but are not limited to, risk of adverse or unanticipated market developments, issuer credit quality risk, risk of lack of uniform standard pricing, risk of adverse events involving any underlying reference obligations, risk of high volatility, risk of illiquidity/little to no secondary market, and conflicts of interest. Any payments on a structured product are subject to the credit risk of the issuer and/or guarantor. Investors may lose their entire investment, i.e., incur an unlimited loss. Before investing in a structured product, investors should review the accompanying offering document, prospectus or prospectus supplement to understand the actual terms and key risks associated with each individual structured product. For a more comprehensive list of the risks involved with a particular product, please refer to the relevant risk disclosure booklet or speak to your J.P. Morgan team.  If you are in any doubt about the risks involved in the product, you may clarify with the intermediary or seek independent professional advice.
  • Private investment funds (including, without limitation, hedge funds, funds of hedge funds, private equity funds, real estate funds, etc.) are subject to special risks, including risk of loss of the entire investment and is suitable only for investors with sufficient knowledge and sophistication to evaluate the merits and risks of such investments. As a reminder, private investment funds often engage in leveraging and other speculative investment practices that may increase the risk of investment loss. These investments can be highly illiquid, and may not be required to provide periodic pricing or valuation information to investors, and may involve complex tax structures and delays in distributing important tax information. Distributions are not guaranteed and may be modified at the Fund Board’s discretion. These investments are not subject to the same regulatory requirements as mutual funds; and often charge high fees (performance fees in addition to management fees). Further, any number of conflicts of interest may exist in the context of the management and/or operation of any such fund. For comprehensive details around unique set of risks for specific alternative investments, please refer to the applicable offering memorandum.
  • Investments in digital assets and cryptocurrencies, or other investment vehicles holding or referencing digital assets, are highly speculative and involve significant risks, including, but not limited to, increased volatility, ongoing regulatory uncertainty including lack of clear precedent in various jurisdictions surrounding digital assets, cybersecurity risk relating to digital asset holdings, and increased sensitivity to news, speculation and manipulation. Likewise, various digital assets may differ from one another in their technological characteristics, regulatory treatment, market convention and performance. There is limited data on the performance of digital assets and products referencing digital assets (although in no case should historical performance be taken as an indication of future performance). You should consider these unique characteristics and whether these assets are suitable for you when making an investment decision.
  • The prices and rates of return are indicative, as they may vary over time based on market conditions.
  • Additional risk considerations exist for all strategies.
  • The information provided herein is not intended as a recommendation of or an offer or solicitation to purchase or sell any investment product or service.
  • Opinions expressed herein may differ from the opinions expressed by other areas of J.P. Morgan. This material should not be regarded as investment research or a J.P. Morgan investment research report.


GENERAL RISKS & CONSIDERATIONS
. 
Any views, strategies or products discussed in this material may not be appropriate for all individuals and are subject to risks. Investors may get back less than they invested, and past performance is not a reliable indicator of future results. Asset allocation/diversification does not guarantee a profit or protect against loss. Nothing in this material should be relied upon in isolation for the purpose of making an investment decision. You are urged to consider carefully whether the services, products, asset classes (e.g. equities, fixed income, alternative investments, commodities, etc.) or strategies discussed are suitable to your needs. You must also consider the objectives, risks, charges, and expenses associated with an investment service, product or strategy prior to making an investment decision. For this and more complete information, including discussion of your goals/situation, contact your J.P. Morgan representative.

NON-RELIANCE. Certain information contained in this material is believed to be reliable; however, JPM does not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which are provided for illustration/reference purposes only. The views, opinions, estimates and strategies expressed in this material constitute our judgment based on current market conditions and are subject to change without notice. JPM assumes no duty to update any information in this material in the event that such information changes. Views, opinions, estimates and strategies expressed herein may differ from those expressed by other areas of JPM, views expressed for other purposes or in other contexts, and this material should not be regarded as a research report. Any projected results and risks are based solely on hypothetical examples cited, and actual results and risks will vary depending on specific circumstances. Forward-looking statements should not be considered as guarantees or predictions of future events.

Nothing in this document shall be construed as giving rise to any duty of care owed to, or advisory relationship with, you or any third party. Nothing in this document shall be regarded as an offer, solicitation, recommendation or advice (whether financial, accounting, legal, tax or other) given by J.P. Morgan and/or its officers or employees, irrespective of whether or not such communication was given at your request. J.P. Morgan and its affiliates and employees do not provide tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transactions.

Legal Entity and Regulatory Information.

J.P. Morgan Wealth Management is a business of JPMorgan Chase & Co., which offers investment products and services through J.P. Morgan Securities LLC (JPMS), a registered broker-dealer and investment adviser, member FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. Certain custody and other services are provided by JPMorgan Chase Bank, N.A. (JPMCB). JPMS, CIA and JPMCB are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.

Bank deposit accounts and related services, such as checking, savings and bank lending, are offered by JPMorgan Chase Bank, N.A. Member FDIC.

This document may provide information about the brokerage and investment advisory services provided by J.P. Morgan Securities LLC (“JPMS”). The agreements entered into with JPMS, and corresponding disclosures provided with respect to the different products and services provided by JPMS (including our Form ADV disclosure brochure, if and when applicable), contain important information about the capacity in which we will be acting. You should read them all carefully. We encourage clients to speak to their JPMS representative regarding the nature of the products and services and to ask any questions they may have about the difference between brokerage and investment advisory services, including the obligation to disclose conflicts of interests and to act in the best interests of our clients.

J.P. Morgan may hold a position for itself or our other clients which may not be consistent with the information, opinions, estimates, investment strategies or views expressed in this document. JPMorgan Chase & Co. or its affiliates may hold a position or act as market maker in the financial instruments of any issuer discussed herein or act as an underwriter, placement agent, advisor or lender to such issuer.