Version 1 - Primary Nav Search

Contributors

Kriti Gupta

Executive Director, Global Investment Strategist, J.P. Morgan Private Bank

Justin Biemann

Global Investment Strategist


The artificial intelligence (AI) buildout has powered the stock market to record highs. From document creation and rapid coding to mass adoption and efficiency, investors are pricing in a world where the technology becomes a greater part of everyday life and yields never-before-seen growth and productivity.

But for most Americans living through this period, the innovation cycle has been far from comfortable. Some tech executives and pundits have predicted large-scale worker displacement, and the risk of cyberattacks on corporations and households has increased as the AI capabilities of bad actors grow in tandem.1 In a call to “pace the frontier,” top AI executives themselves have called for regulation to curb risks posed by the rapid development of the technology.2 It’s no wonder that nearly 40% of Americans say AI does more harm than good.3

While most of this impact is still theoretical, one element is tangible: the effects of an influx of data centers around the country – something the public and politicians are growing more skeptical of.

The buildout

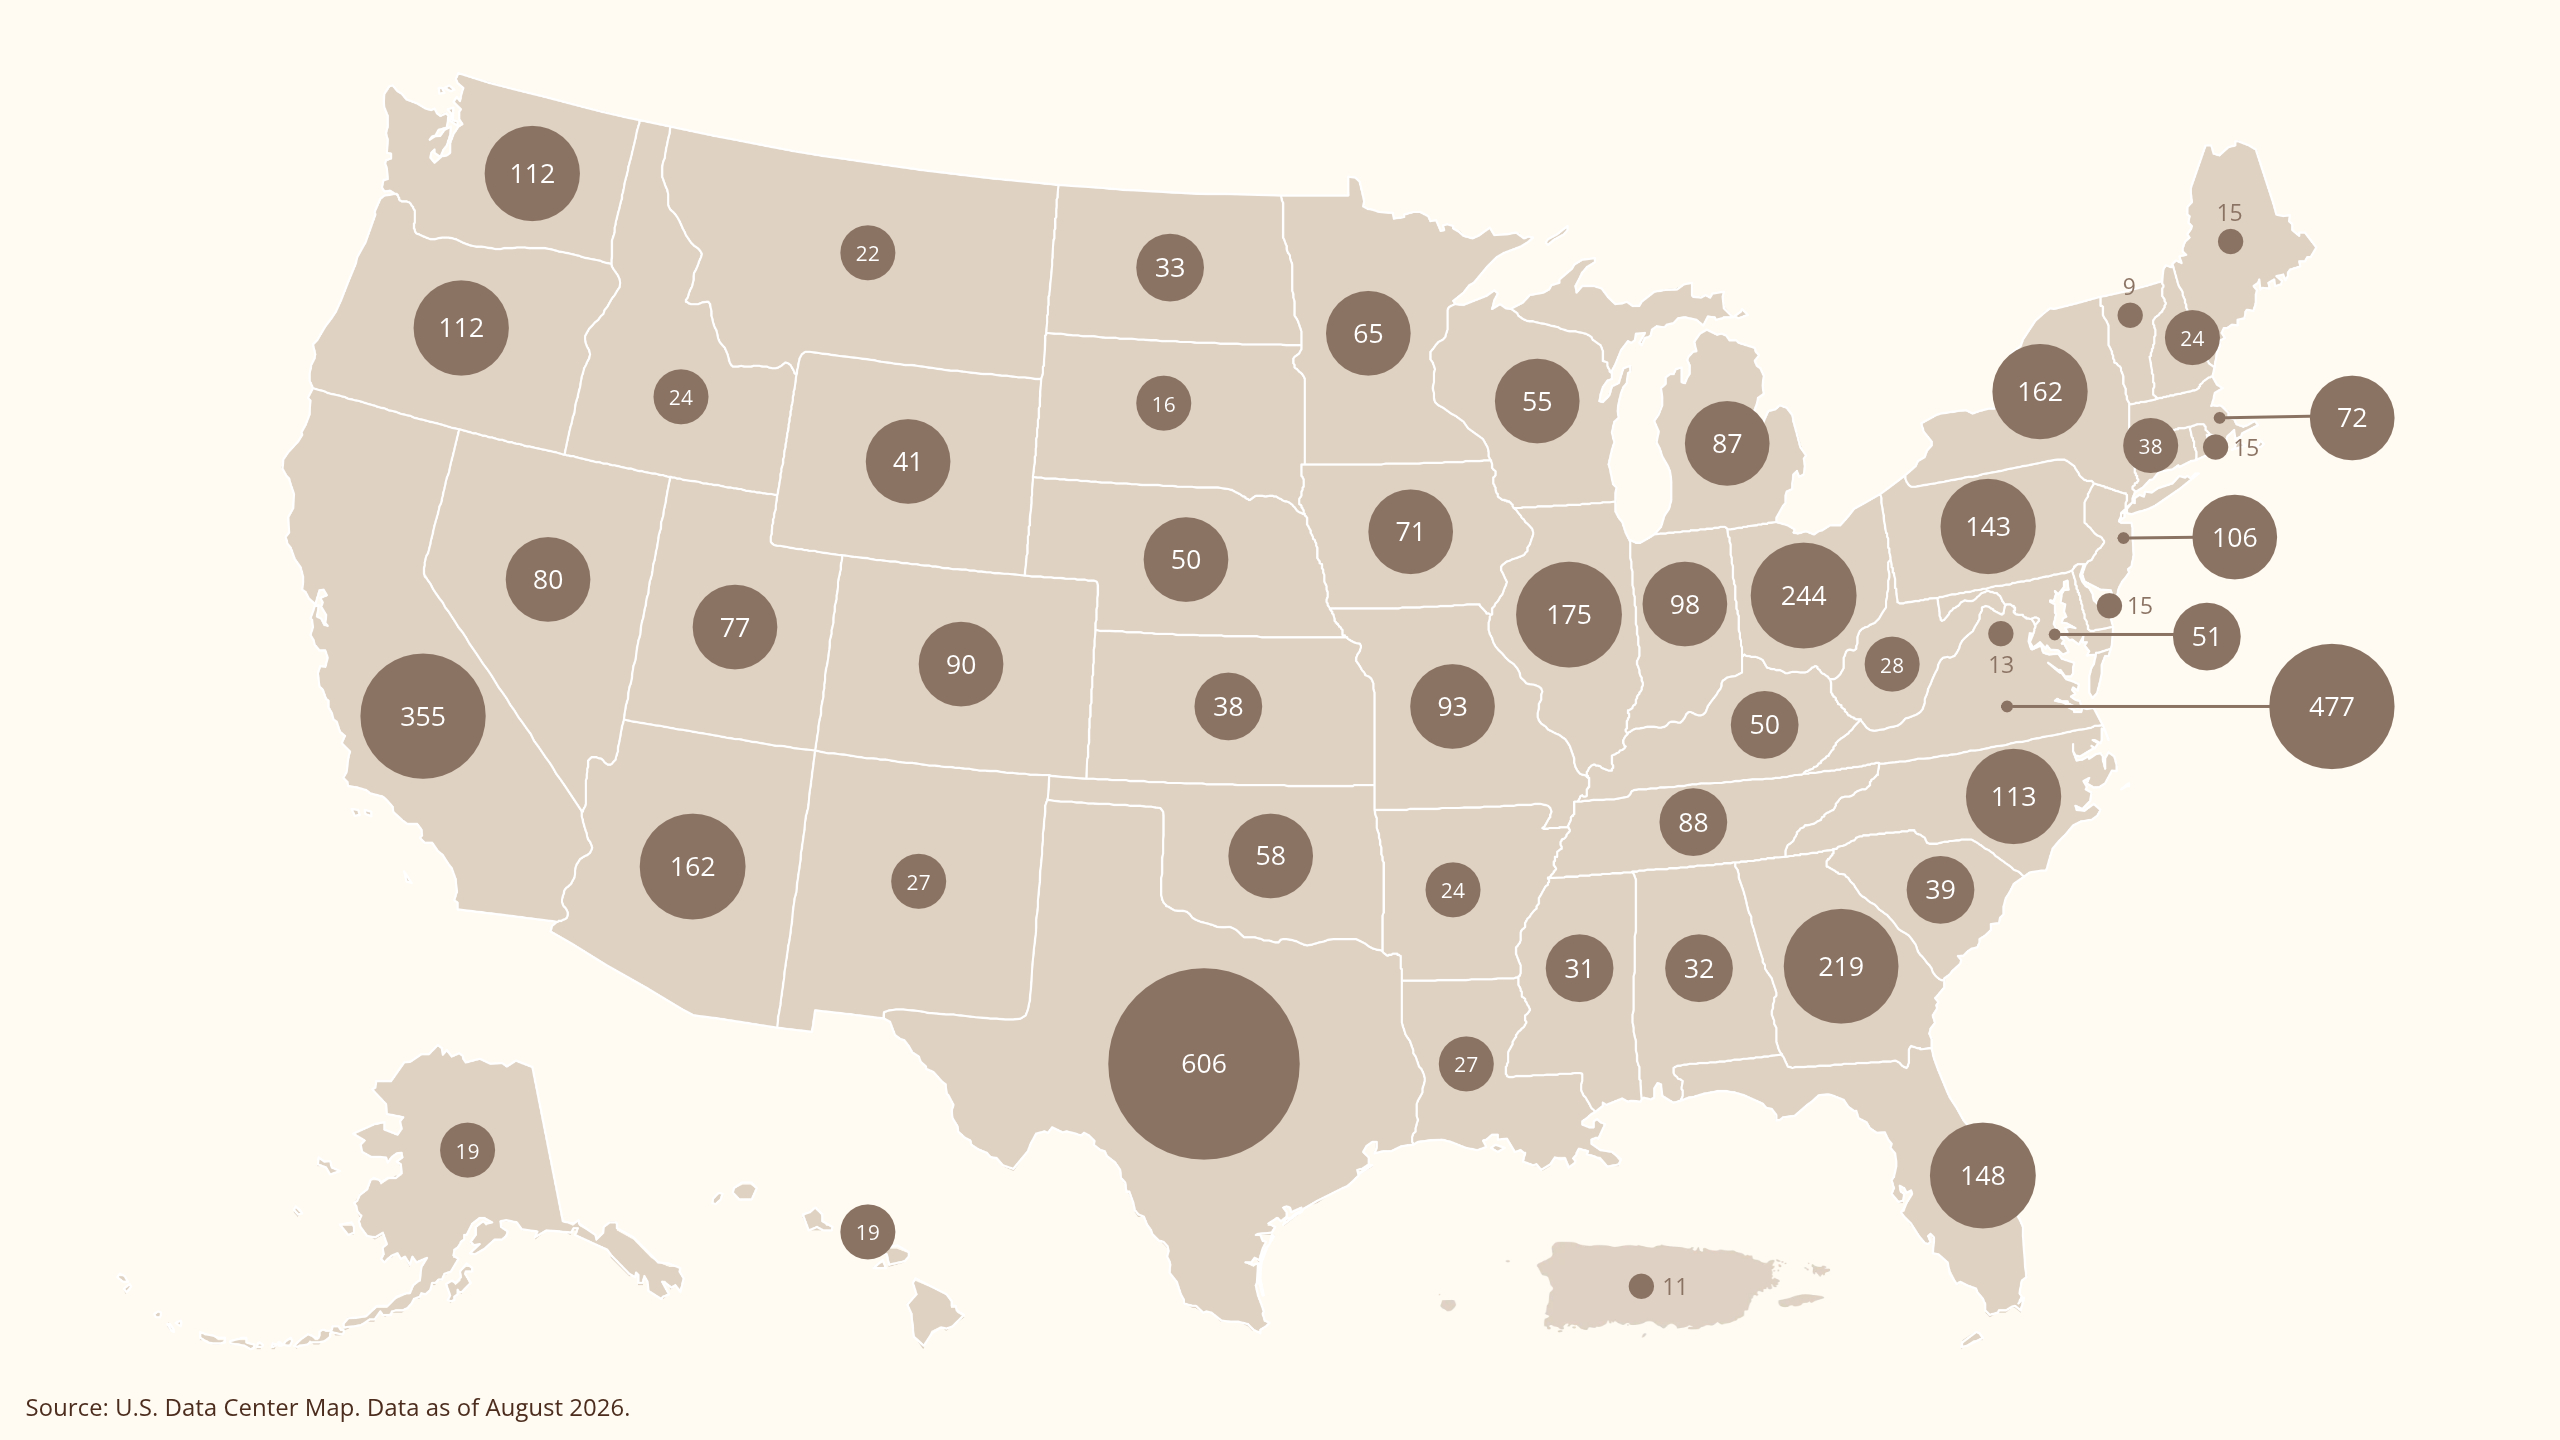
The United States is experiencing an extraordinary data center construction boom, driven initially by cloud computing and now increasingly by AI. While development began in established hubs like Virginia and California, it has spread rapidly into the South and Midwestern parts of the country. States like Texas, Georgia, Arizona, Ohio and Illinois have seen the largest concentration of the over 4,700 data centers across the United States, thanks to business-friendly regulation, fiber infrastructure, power access and affordable land.

Hundreds of data centers are in operation across the country and many more are in the works

The map shows the number of operational data centers in each U.S. state, with the number in each circle representing that state’s value.


Data centers represent the bedrock of the AI buildout, providing the computing power to process large language model (LLM) requests from the industry’s biggest players. That’s why any speedbumps are important for investors to consider – including the current political environment and its ramifications for access to resources.

With the accelerated buildout, those demands are substantial. Data centers consume enormous quantities of electricity and require new power transmission and generation capacity. One 100-megawatt data center has the electricity consumption of approximately 83,000 average U.S. homes.4 Most new hyperscaler data centers are being designed in the 100-megawatt to 1-gigawatt range.5 That has kicked off competition among developers to secure land, electricity, water and cooling technology, among other inputs.

As the buildout ramps up, supply chains and energy solutions have lagged. One of the key hurdles is access to power. Estimates suggest the United States will reach a power shortfall as early as 2029 as demand grows at 3.2% per year over the next decade – driven by data centers, industrialization and electrification.

For consumers, the growing imbalance between power supply and demand is already pushing prices higher. One example is a capacity auction by grid operator PJM, which supplies nearly half of U.S. data center power demand. In July 2025, the auction – which creates a forward market that pays for generator availability in the future – hit a record $329.17 per megawatt per day.6 That auction marked a 1,000% rise in prices over the last two years. Given affordability’s position as the top voter concern in the upcoming midterm elections, the election’s verdict could set the tone.

The pushback

Data centers are by far the most tangible component of the AI buildout, drawing the public’s questions, concerns and pushback. This trend has ramped up in the past few months, just in time for election season.

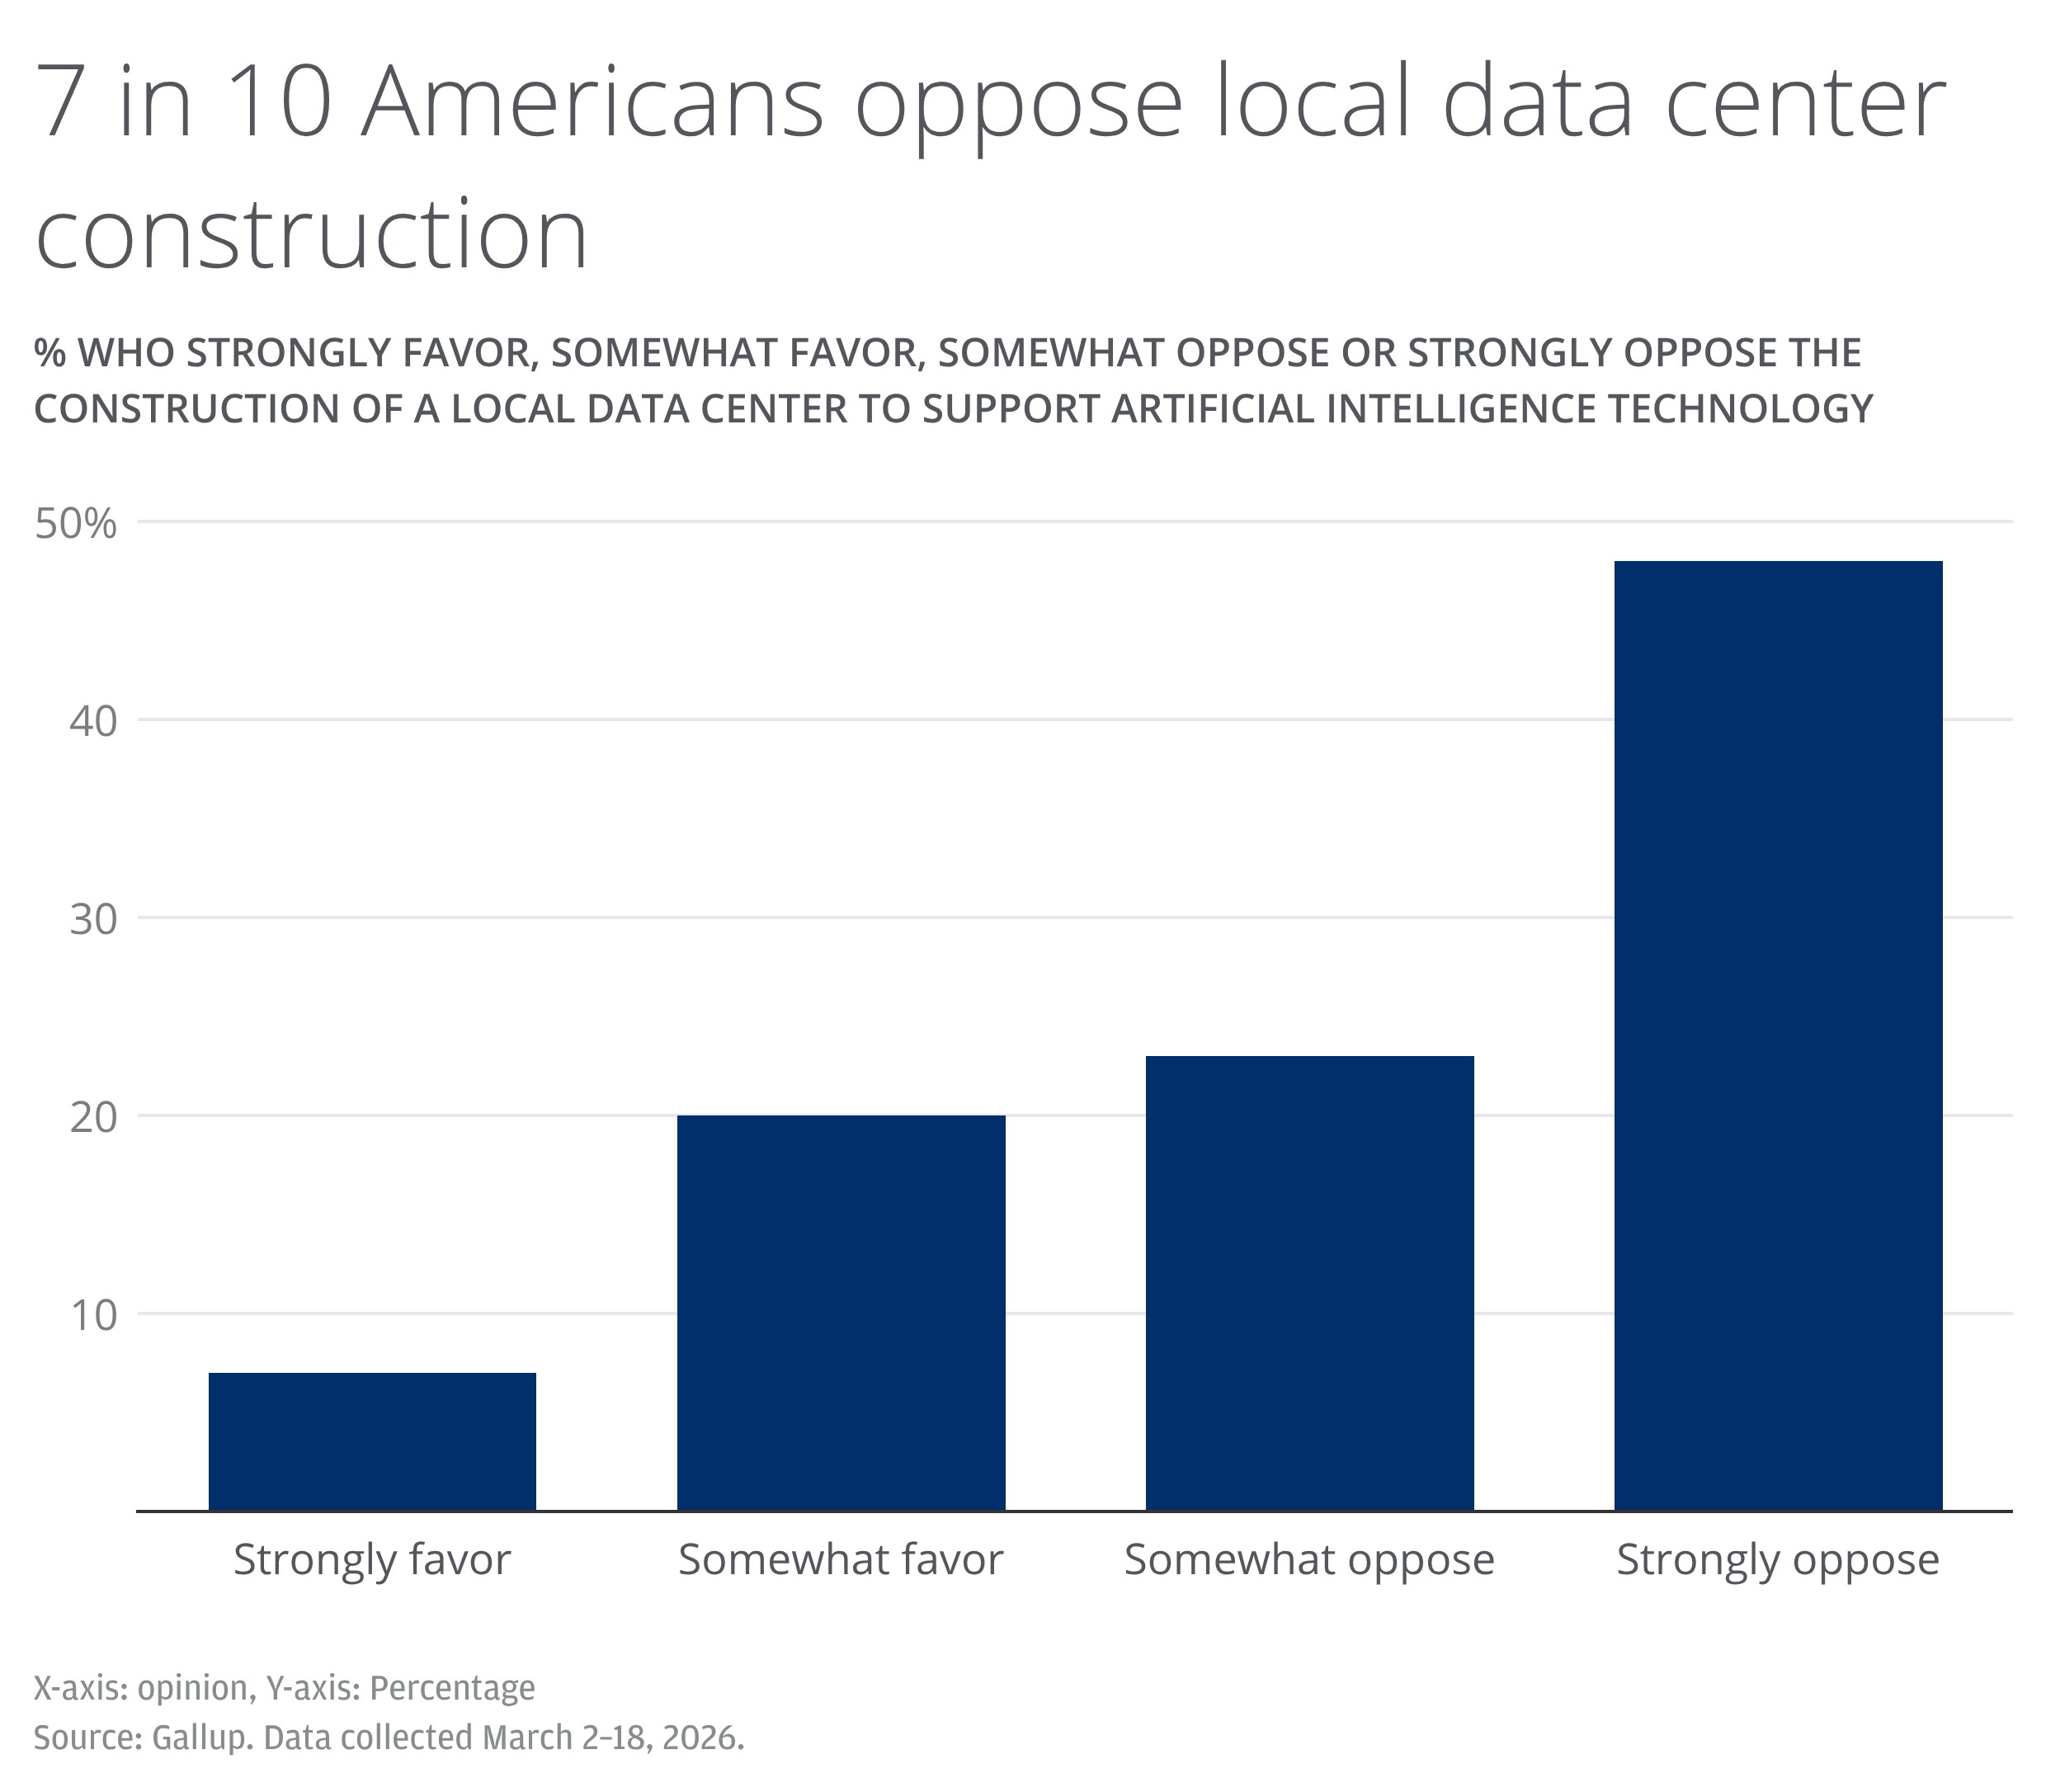
Polling data shows this is a top issue for Americans, with three-quarters of the country saying they would oppose the construction of a data center near their home. And it’s more than just talk: Disputes over data center construction have more than tripled this year.7

Politicians are listening. The surge in public interest and advocacy around data centers has already made an impact on campaign rhetoric. In line with the negative shift in public opinion, the loudest voices on the campaign trail tend to be neutral or negative on data centers, creating an unusual amount of bipartisan agreement in today’s politically polarized environment.

The bar chart shows the percentage of Americans who either favor or oppose building a local data center to support artificial intelligence technology.


Until recently, Democrats were the main critics of the AI buildout. The party’s traditional focus on labor and consumer safety aligns with skepticism toward a technology that some fear will displace large numbers of workers. If Democrats win control of the House and Senate, they could pursue stricter environmental reviews and place a greater responsibility for data center costs on developers – although any bill would likely require the support of the executive branch.

As recently as a few months ago, Republicans supported faster permitting and AI infrastructure expansion, so a Republican majority in the House and Senate was the most bullish scenario for the data center buildout. But now, a growing number of Republicans have staked positions further from the Trump administration’s enthusiasm for AI.

Growing voter backlash, and signs of bipartisan consensus, could still force developers to absorb more of the infrastructure-related expenses. These signs suggest the AI infrastructure buildout will continue, but who bears the costs will change. And that rulebook is likely to vary by state.

The policy divide

In the absence of a national framework on the data center buildout, state-level legislation is falling into three broad approaches.

  • The Texas approach: Initially an attractive destination for the data center buildout because of its independent electricity grid, the Electric Reliability Council of Texas (ERCOT), a greater-than-expected backlog of proposed electricity demand has resulted in Texas’s governor halting new data center grid connections as the state audits the requests and ensures the costs don’t fall on ordinary ratepayers.
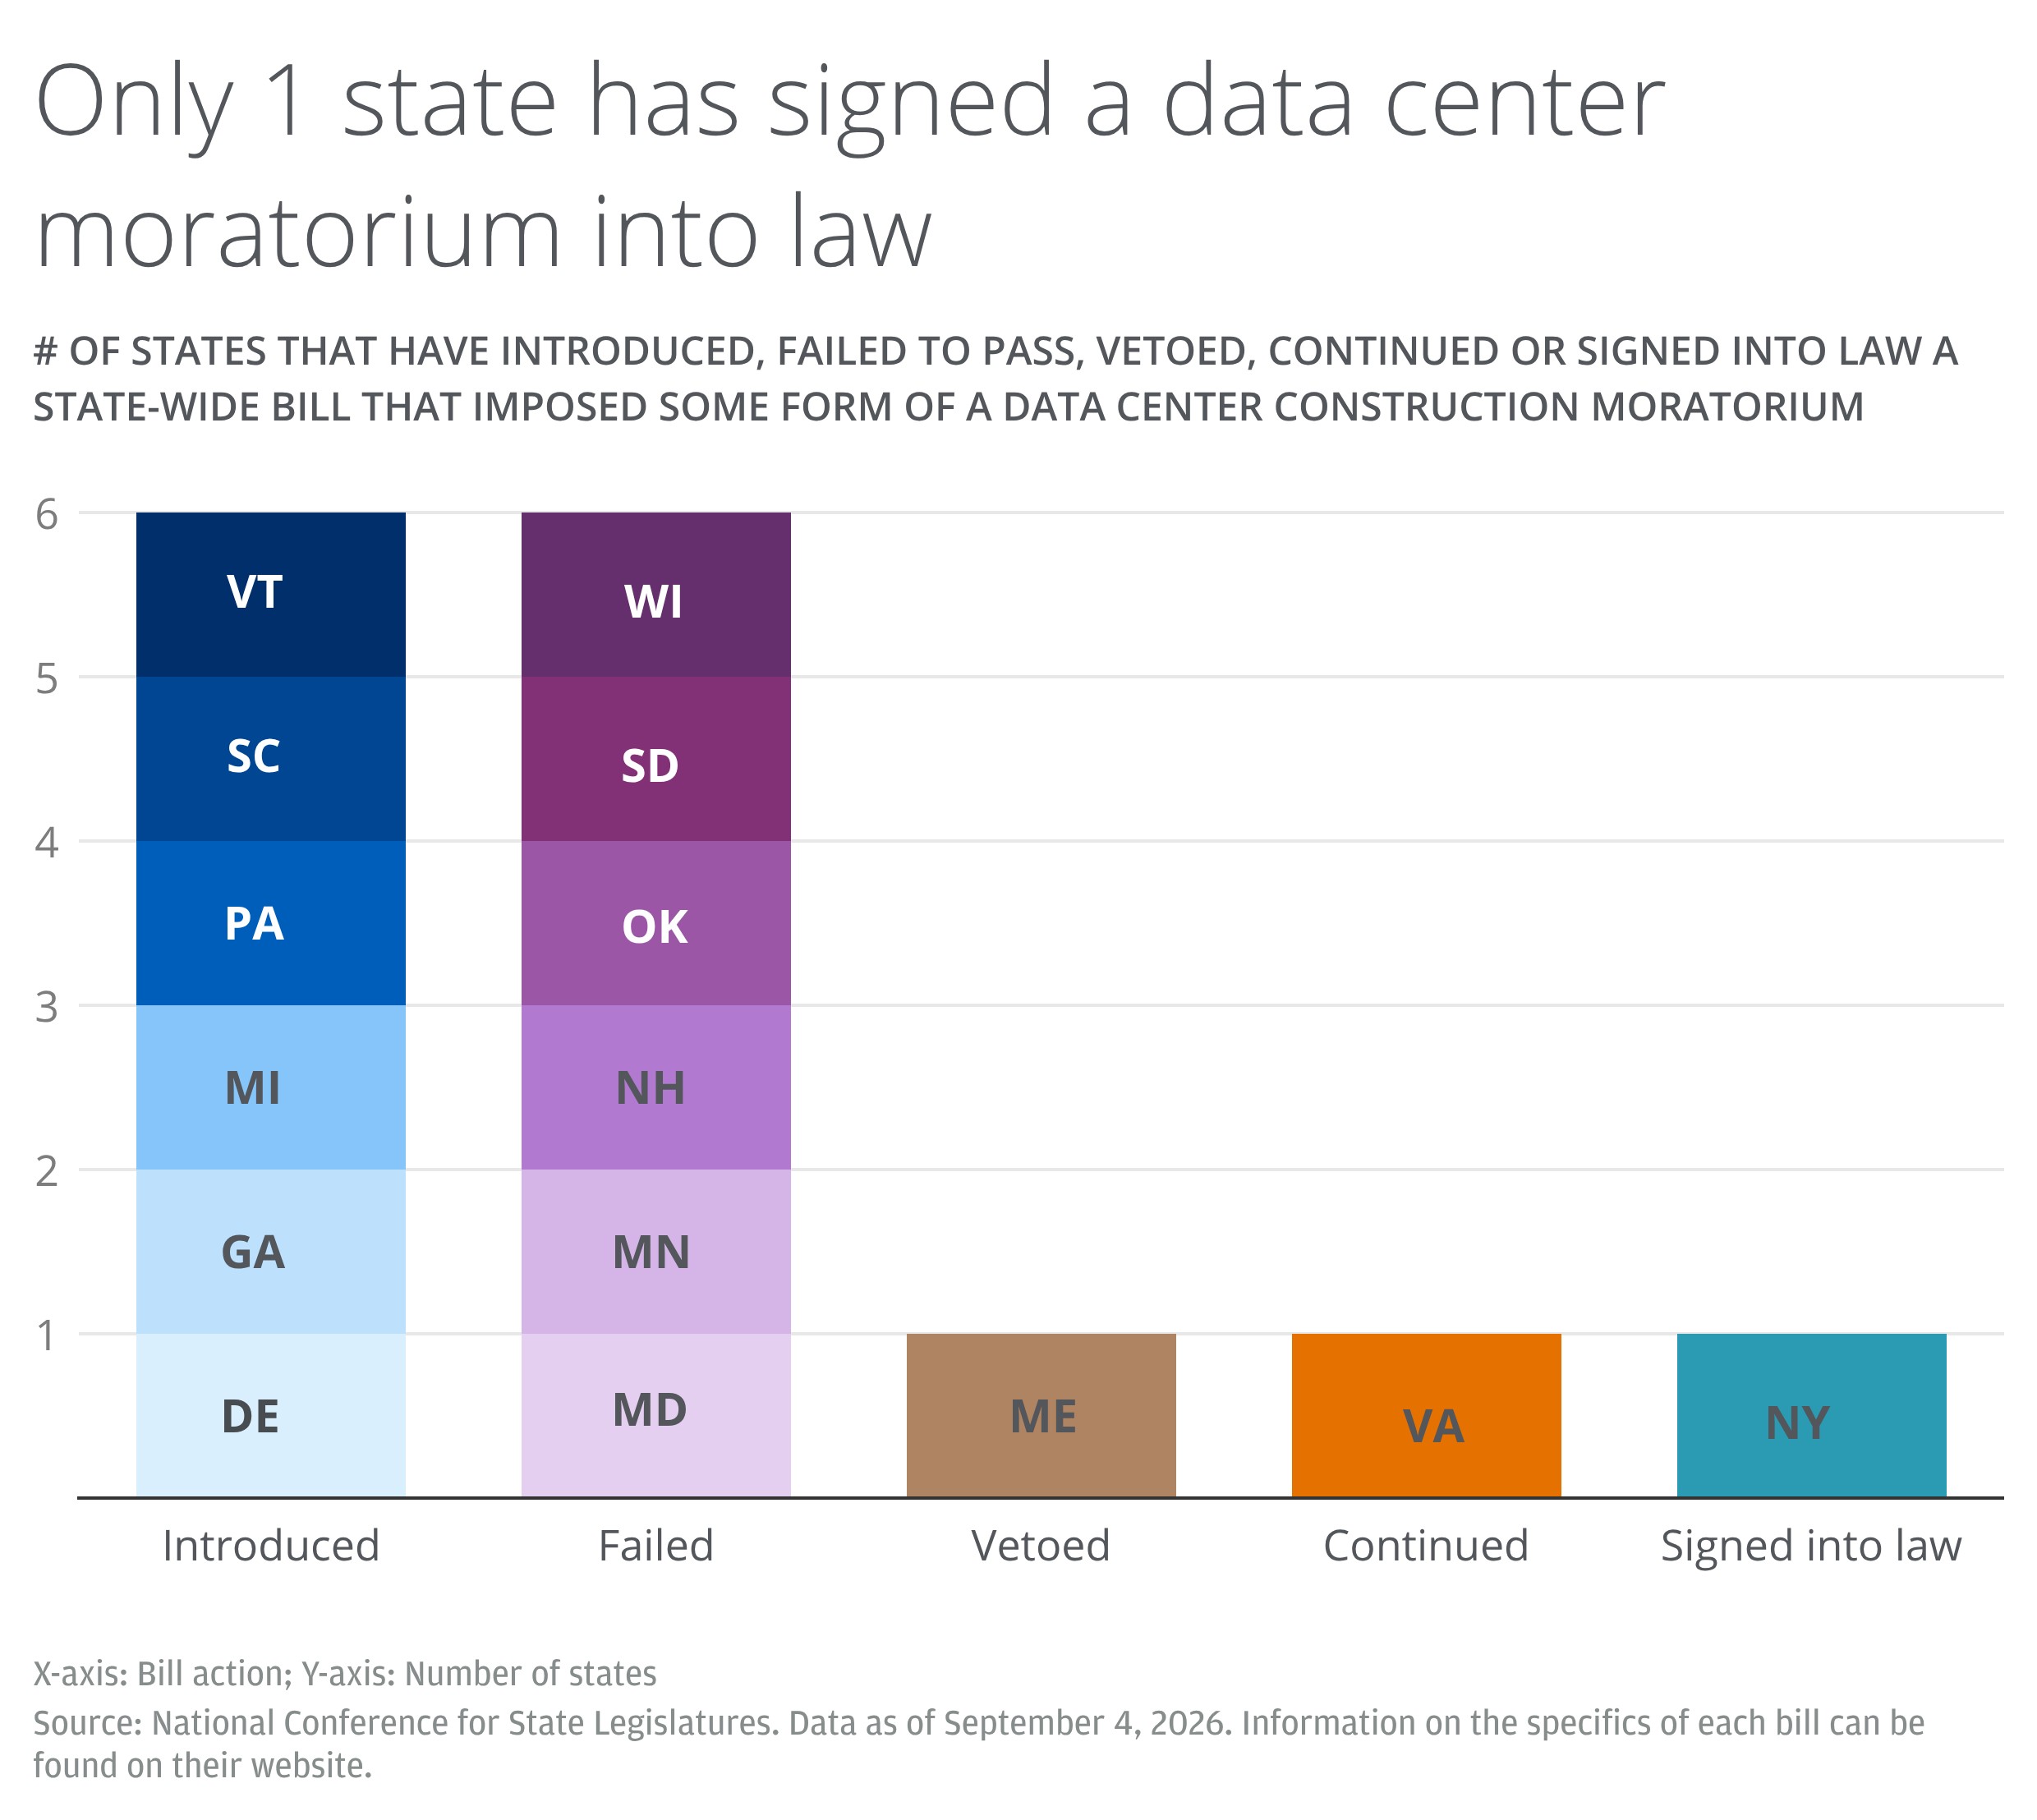
  • The New York approach: The state has created a temporary moratorium on new projects, temporarily stopping the buildout while the state establishes rules to navigate the growth. Proposals have included shifting the incremental electricity and infrastructure costs to the data center developer rather than equally with households who share the same access to power. Other controls include noise limits, water restrictions, environmental regulation and zoning concerns.
  • The Pennsylvania approach: Using a conditional incentive structure, data center developers in the state can receive government support for the buildout, but only if they demonstrate benefits to communities, workers, ratepayers and the environment.
This chart shows the six states that have at least introduced a state-wide bill that imposed some form of data center construction moratorium.


The larger political question has begun to shift from “Should America build data centers?” to “Who should pay for them, where can they be built, and what protections must communities receive in return?”

Shifting policies could mean rising costs of building and operating data centers, squeezing profit margins for both tech giants and the companies contracted to construct these facilities. Given the reliance of data centers on power grids, utility stocks in particular have become tied to the AI trade, benefiting from the rallies, but also underperforming as concerns on the buildout arise.

The announcements of data center moratoriums from New York and Texas have created a particular overhang on the Utilities sector, with its share price underperforming the broader S&P 500 since the announcements. This is especially significant in Texas where widespread support for the data center buildout, supported by affordable land and an independent electricity grid, faced an unexpected roadblock. The move is evidence that investors are beginning to price in a reality where the AI data center buildout could face hurdles beyond just capacity and supply constraints. The politics may matter too for financial markets more directly than they have in previous cycles.

Conclusion

Public opinion can impact future policy even if it doesn’t immediately change activity or regulation. Americans are starting to think about what data centers are doing to their energy bills with a sensitivity akin to the way they watch gas prices or the housing market. The question that still needs an answer is how this issue will determine voters’ choices. Because of this, politicians and parties strategizing for future elections will be watching the results very closely. For investors, the most important measure to look for on November 3 may not be whether the Democrats or Republicans notch more wins, but how well candidates do on either side of the data center issue.

If politicians who criticize the AI buildout win races across the board, more politicians will be incentivized to take similarly strict positions in the future. This outcome could prompt an uptick in proposed regulatory legislation or even lead to federal regulation becoming a priority for the next Congress.

If the results are mixed, or exit polls show that voters prioritized other issues, politicians will have a different takeaway. They may see it as too risky to stake out a firm position on such a rapidly evolving issue without the guarantee of public support. The result would be a majority of both state and federal lawmakers who put additional regulations on the back burner.

The 2026 midterm elections won’t determine whether the U.S. builds AI infrastructure but may shift timing, who pays and where it gets built.

We can help

For more information about what the AI buildout and the evolving regulatory landscape might mean for your portfolio, contact your J.P. Morgan team.

References

1.

We do not think this will transpire, as AI capabilities, physical infrastructure limits, and political and regulatory concerns should slow the AI buildout. J.P. Morgan Private Bank, “Job destroyer? Here’s what you need to know about AI and labor markets.” (April 21, 2026)

2.

Dario Amodei. (September 12, 2026)

3.

Gallup. (July 2026)

4.

IEA. (Data as of 2026)

5.

Epoch AI. (Data as of September 2026)

6.

J.P. Morgan Private Bank, “Here’s how scarce electricity could hamper the AI investing boom.” (July 29, 2026)

7.

DataCenterTracker.org. (As of August 2026)

Connect with a Wealth Advisor

Reach out to your Wealth Advisor to discuss any considerations for your current portfolio. If you don’t have a Wealth Advisor, click here to tell us about your needs and we’ll reach out to you.

Connect now

IMPORTANT INFORMATION

This material is for informational purposes only, and may inform you of certain products and services offered by J.P. Morgan’s wealth management businesses, part of JPMorgan Chase & Co. (“JPM”). Products and services described, as well as associated fees, charges and interest rates, are subject to change in accordance with the applicable account agreements and may differ among geographic locations. Not all products and services are offered at all locations. If you are a person with a disability and need additional support accessing this material, please contact your J.P. Morgan team or email us at accessibility.support@jpmorgan.com for assistance. Please read all Important Information.


GENERAL RISKS & CONSIDERATIONS
. 
Any views, strategies or products discussed in this material may not be appropriate for all individuals and are subject to risks. Investors may get back less than they invested, and past performance is not a reliable indicator of future results. Asset allocation/diversification does not guarantee a profit or protect against loss. Nothing in this material should be relied upon in isolation for the purpose of making an investment decision. You are urged to consider carefully whether the services, products, asset classes (e.g. equities, fixed income, alternative investments, commodities, etc.) or strategies discussed are suitable to your needs. You must also consider the objectives, risks, charges, and expenses associated with an investment service, product or strategy prior to making an investment decision. For this and more complete information, including discussion of your goals/situation, contact your J.P. Morgan representative.

NON-RELIANCE. Certain information contained in this material is believed to be reliable; however, JPM does not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which are provided for illustration/reference purposes only. The views, opinions, estimates and strategies expressed in this material constitute our judgment based on current market conditions and are subject to change without notice. JPM assumes no duty to update any information in this material in the event that such information changes. Views, opinions, estimates and strategies expressed herein may differ from those expressed by other areas of JPM, views expressed for other purposes or in other contexts, and this material should not be regarded as a research report. Any projected results and risks are based solely on hypothetical examples cited, and actual results and risks will vary depending on specific circumstances. Forward-looking statements should not be considered as guarantees or predictions of future events.

Nothing in this document shall be construed as giving rise to any duty of care owed to, or advisory relationship with, you or any third party. Nothing in this document shall be regarded as an offer, solicitation, recommendation or advice (whether financial, accounting, legal, tax or other) given by J.P. Morgan and/or its officers or employees, irrespective of whether or not such communication was given at your request. J.P. Morgan and its affiliates and employees do not provide tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transactions.

Legal Entity and Regulatory Information.

J.P. Morgan Wealth Management is a business of JPMorgan Chase & Co., which offers investment products and services through J.P. Morgan Securities LLC (JPMS), a registered broker-dealer and investment adviser, member FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. Certain custody and other services are provided by JPMorgan Chase Bank, N.A. (JPMCB). JPMS, CIA and JPMCB are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.

Bank deposit accounts and related services, such as checking, savings and bank lending, are offered by JPMorgan Chase Bank, N.A. Member FDIC.

This document may provide information about the brokerage and investment advisory services provided by J.P. Morgan Securities LLC (“JPMS”). The agreements entered into with JPMS, and corresponding disclosures provided with respect to the different products and services provided by JPMS (including our Form ADV disclosure brochure, if and when applicable), contain important information about the capacity in which we will be acting. You should read them all carefully. We encourage clients to speak to their JPMS representative regarding the nature of the products and services and to ask any questions they may have about the difference between brokerage and investment advisory services, including the obligation to disclose conflicts of interests and to act in the best interests of our clients.

J.P. Morgan may hold a position for itself or our other clients which may not be consistent with the information, opinions, estimates, investment strategies or views expressed in this document. JPMorgan Chase & Co. or its affiliates may hold a position or act as market maker in the financial instruments of any issuer discussed herein or act as an underwriter, placement agent, advisor or lender to such issuer.